Borrow between $2,350 - $5,000 today.

Apply now Apply now

Tag: <span>Everyday Expenses</span>

image

5 Low Cost Hobbies To Take Up In 2026

As Aussies continue to navigate the growing costs of living, many of us are looking for ways to have fun in the new year without spending too much money. That's why more and more people are pursuing affordable hobbies and interests in 2026.

Guide 23 January 2026

In this article:

    Calculate your loan repayments

    How much would you like to borrow?

    Simply. Transparent. Tailored to you.

    Loan amount:
    $
    $2,350 $5,000
    Repayment frequency:
    Weekly repayment:

    (Over 12 month loan term)

    $0.00
    • Loan term 12 months
    • Interest & Fees $1,072
    • Total to pay $3,172
    arrow
      image

      As Aussies continue to navigate the growing costs of living, many of us are looking for ways to have fun in the new year without spending too much money. That’s why more and more people are pursuing affordable hobbies and interests in 2026.

      1. DIY Crafts And Upcycling

      These are two classic low-cost hobbies that let you make something useful and potentially valuable out of scraps and discarded items you already have.

      DIY crafts and upcycling encourage creativity over consumption, whether it’s by repainting old furniture, making gifts by hand, or finding new uses for items around the house. Many people like the feeling of accomplishment that comes with finishing small projects, especially when they can follow free online tutorials.

      What Is Upcycling?

      We’re all very aware of recycling as a way of reducing waste, but how does it differ from upcycling?

      Simply put, upcycling is the process of transforming old or discarded materials or items into something new that is of greater value or quality. It differs from recycling by not breaking down materials to produce something new, like recycled paper or plastics. Instead, you’re simply “upgrading” the item in its current state through design or creative repurposing. For example, you might make a candle holder out of an empty jam jar rather than throwing it out in the recycling bin.

      If you have to pay for small purchases up front and keep track of your household expenses, knowing how personal loans for everyday expenses work can help you plan with more confidence.

      2. Exploring Local Hiking Trails On The Weekend

      Australia has some wonderful walking trails and hiking spots across the country, from the Heysen Trail in South Australia (the country’s longest marked trail, spanning 1200 kilometres) to a variety of tracks in Victoria’s Wilsons Promontory. And thankfully, for most people, walking is one of the easiest low-cost hobbies you can take up in 2026.

      Many of us see the new year as the perfect time to get fit and active, but don’t always want to commit to going to the gym to achieve that goal. Australia is rich with national parks, beaches and other hiking trails that mean you don’t have to shell out for memberships or expensive equipment to get the heart rate up.

      Walking regularly is a hobby that can easily become a part of your routine if you try out new routes or invite friends to join you. If you’re travelling long distances to test out some new trails, be sure to service or repair your car in advance. The last thing you want is to find yourself stranded out in the middle of nowhere.

      3. Reading And Exchanging Books

      If you love to travel to new places but don’t have the time to take advantage of a holiday loan at the moment, reading is an easy and low-cost way to explore new worlds from the comfort of your home.

      No matter how much money you have, you can read by going to the library, buying used books, downloading free eBooks, or swapping books with other people in your community. Many Australians also like to join book clubs or online reading groups. These groups add a social aspect without over-the-top additional expenses.

      4. Gardening (Even In Small Spaces)

      When done right, gardening can become a low-cost hobby for homeowners and renters alike. Better yet, you don’t even need a lot of outdoor space to make it work.

      Growing herbs on a windowsill or vegetables in containers (possibly even upcycled ones) can help you save money on groceries over time and become a relaxing pastime, regardless of the season. Starting with seeds and recycled pots can lower costs and help you slowly get accustomed to the “green thumb” lifestyle.

      Make Your Home Gardening-Friendly

      One essential factor of gardening is natural light, whether it’s outdoors in the sun or through an installed skylight in your home. To maximise the amount of sunlight you can enjoy indoors, a Red Tree Finance online loan can help you make any essential improvements to your home.

      5. Photography

      One of the great things about taking up photography as an interest is that you can spend as much or as little on it as you like. Though some people will apply for a $5000 loan to purchase the very best camera, lens, tripod and other equipment, you can get just as much enjoyment from the hobby by using your smartphone camera.

      As a low-cost hobby, photography is easy to fit into a busy schedule. Photo opportunities can come from anywhere, whether it’s on the walk to the train station or a classic summer sunset over the beach. There is also a plethora of free instructional videos on YouTube to get you started.

      Five Additional Low-Cost Hobbies To Consider

      Looking for some other inexpensive interests to pursue this year? Here are 5 more to think about:

      • Creative writing
      • Home yoga or stretching
      • Cooking
      • Puzzles and brain-training games
      • Volunteering in the local community

      Like photography, some of these will have free how-to videos online, so you won’t need to pay for expensive courses if you don’t want to. All of these can potentially bring fulfilment and colour to your life in ways you may not have imagined. And if you’re looking at secured loans to get your new hobby underway, Red Tree Finance is here to help.

      Enjoy Life More Without Spending More!

      Low-cost hobbies show that you don’t have to spend a lot of money to have fun. You can improve your health without adding to your financial stress by picking activities that fit your lifestyle and budget. Small, cheap habits can make a big difference over time, whether you like doing creative things, moving around outside, or learning something new.

      Whether you’re looking at a weekend loan to fund a quick hiking trip in the Aussie bushland, or an instant loan to buy a new camera, Red Tree Finance lets you look at and apply for short-term loans online whenever you need them.

      Frequently Asked Questions

      View all FAQs View all FAQs

      In many cases, the most inexpensive hobbies are those that:

      • Make use of the skills or resources you already have.
      • Require very little specialised tools or equipment.
      • You can do at home or in the local community.

      These can include activities such as weekend walks, DIY crafts, gardening and reading.

      This is a widely-regarded personal development concept that suggests people should pursue hobbies in five specific areas in order to live a balanced life. Those categories include hobbies to:

      • Make money (e.g. photography, blogging)
      • Stay fit and in shape (running, competitive sport)
      • Express your creativity (playing an instrument, creative writing)
      • Build knowledge (learning a new language, reading)
      • Evolve your mindset (meditation, mindfulness practices)

      If you’re looking for some funds to start your new hobbies in 2026, Red Tree Finance has loans from $2350 to get you started.

      There are many hobbies you can take up that don’t cost the earth, from neighbourhood walks to designated hiking trails, to free online courses, smartphone photography or learning a language.

      The information provided in this blog is of a general nature and is provided without considering your specific objectives, financial situation, or needs. It is intended for informational purposes only and should not be relied upon as financial, investment, or other professional advice.Before making any financial decisions or taking action based on the information presented, you are strongly encouraged to assess its appropriateness in light of your individual circumstances. Red Tree Finance does not intend to provide personalised financial advice, and you should seek independent financial, legal, tax, and other relevant advice tailored to your unique situation.
      image
      img
      image
      img
      Apply now

      Ready to apply for a loan?

      Apply to borrow up to $5,000 fast. Complete your online application in under 5 minutes.

      image
      image
      image

      How To Budget For A Family Income

      Grocery shopping. School supplies and sports team fees. Utility bills. Day-to-day costs for Australian families certainly add up fast. Therefore, you cannot overstate the importance of knowing how to budget for a family income.

      Budgeting 15 October 2025

      In this article:

        Calculate your loan repayments

        How much would you like to borrow?

        Simply. Transparent. Tailored to you.

        Loan amount:
        $
        $2,350 $5,000
        Repayment frequency:
        Weekly repayment:

        (Over 12 month loan term)

        $0.00
        • Loan term 12 months
        • Interest & Fees $1,072
        • Total to pay $3,172
        arrow
          image

          Grocery shopping. School supplies and sports team fees. Utility bills. Day-to-day costs for Australian families certainly add up fast. Therefore, you cannot overstate the importance of knowing how to budget for a family income.

          What Is A 50/30/20 Budget?

          If there is one rule that makes knowing how to budget for a family income significantly easier, it’s the 50/30/20 budget.

          It’s a fairly straightforward system that divides your income into three key categories. You split up your pay like this:

          • 50% goes to essential living expenses (e.g. food, rent, bills, transport)
          • 30% goes to “wants” and lifestyle expenses such as clothing, movies, restaurants, etc
          • 20% goes towards your savings and short/medium/long-term goals

          The 50/30/20 budget system provides a straightforward and structured approach to creating an achievable family budget. It enables you to prioritise the immediate financial needs and wants of your family, while not neglecting any long-term goals you may also have.

          To put this system into action, you’ll need to track the money coming in and the money going out. This is how to go about it.

          Assess The Family Income (Money In)

          The all-important first step is to record the money coming into the household. This might include anything from wages or salary payments to share dividends, pensions or Government benefits.

          You’ll want to record how much income you receive, where that income comes from and how frequently you receive it (i.e. weekly, monthly, annually).

          Calculate Your Expenses (Money Out)

          Once you’ve recorded the money coming in, you need to record your expenses. They typically fall under three categories:

          • Fixed expenses – rent or mortgage payments, utility bills, council rates, food and groceries.
          • Debt expenses – credit card payments, loan repayments.
          • Unplanned expenses – medical bills, car repairs, etc.

          You’ll want to record information like the amount of the expense, the frequency with which you pay it (weekly, fortnightly, monthly) and the day or date it comes out. An Excel spreadsheet can be an effective visual tool for this. You can see the money coming in, the money going out, and let Excel do all the necessary calculations that will help you put the 50/30/20 system into practice.

          Why You Need A Budget In Place

          Knowing how to budget for a family income will help you to see how much money you have coming into the household and how much money you have going out. That way, you have the financial information in front of you to better plan for the immediate and long-term future.

          Budgeting helps you meet short and long-term financial goals. When you set these goals, whether it’s to save up for an overseas trip or a down payment on a house, it

          pays to take the SMART approach to goal setting.

          You’ll see everyone from the big four banks to the Australian Government’s MoneySmart website using this acronym; it stands for goals that are:

          • Specific
          • Measurable
          • Achievable
          • Realistic or relevant
          • Time-bound

          Also important and something that will largely determine your budgeting approach is whether you’re setting short, medium or long-term goals.

          Setting and Meeting Short, Medium and Long Term Family Budget Goals

          How to budget for a family income can differ depending on whether you’re setting short-term goals or looking at the bigger, long-term picture.

          Let’s put the five SMART components into common examples for each end of the scale.

          Short-term goals are typically those that you’ll achieve within 0-2 years. So, whether you’re saving $700 for a PlayStation or $7000 for a holiday, this is the easiest way to go about it.

          • Specifics – The family wants to save $7000 for an overseas holiday.
          • Measurable – They set up a new savings account to save that money.
          • Achievable – Both income earners create an automatic transfer that deducts $50 from their weekly or fortnightly pay and deposits it into the new account.
          • Realistic – They know to keep the goal achievable and relevant, and make any necessary changes should financial circumstances change. That may involve increasing or decreasing your automatic payment to keep within your family budget.
          • Time-bound – The family sets a time frame in which they aim to achieve their goal (e.g. “We want to save $7000 within 12 months / by the end of the year).

          Medium-term goals typically sit within the 3-5 year timeframe and may include saving for a house deposit, paying off a credit card debt, or buying a new car. In this situation, you might follow a similar process to the one above. For medium-term goals, consider opening a higher interest-earning account, increasing the amount of your regular payments and keeping the goal within reach, depending on your income and budget needs.

          One of the most common long-term goals for families, taking five or more years, is paying off credit card debt. This is how you might put a long-term SMART goal into action while still maintaining a comfortable day-to-day lifestyle.

          • S – I want to pay off my credit card balance in two years.
          • M – I will make more than just the minimum monthly payments.
          • A – Instead of monthly payments of $200, I will increase those payments to $300.
          • R – I will keep this goal within reach depending on my income and budget circumstances.
          • T – The timeframe may vary depending on the value of the debt and the minimum repayment amounts.

          Whether your goals are at the short-term end of the spectrum or you’re looking more long-term, it’s important to keep yourself accountable. Don’t get too down if you stray from the path or find you can’t maintain the pace. Make any necessary changes to your SMART goals that help you get back on track.

          4 Essential Tips For Sticking To The Family Budget

          Now your family budget is in place, how will you stick to it? It will take some discipline, but some proven tips can help make it easier.

          • Monitor the budget regularly – Keep track of your income and expenses every month to gauge whether your current budget plan still works for you. Changes to your income and expenses might warrant a revision of your plan.
          • Look for ways to trim the expenses – If it’s been months since you actually used your premium Netflix account, or you can’t remember the last time you reviewed your energy bills, these might present good opportunities to save money.
          • Make changes to your savings plan when necessary – Don’t feel like you’re locked in to putting aside $100 a week into your savings account forever. Changes to employment or life circumstances may require you to tweak your savings plan once in a while.
          • Celebrate your wins! – Sticking to a budget is an achievement worth celebrating! Once you reach a financial goal, enjoy the moment!

          There are plenty of online budget tools and smartphone apps that can help you track your spending and maintain your commitment to your budget.

          Budgeting For Family Emergencies

          One important factor to consider regarding how to budget for a family income is the possibility of emergencies. They happen to any family, whether it’s unplanned medical bills, a sudden loss of employment, or unexpected damage to the house.

          Saving for an emergency fund is well worth factoring into your family budget. Here’s what you need to do.

          Determine How Much You Want To Set Aside

          Working out how much you need in your emergency fund is the first step.

          The general rule of thumb is to look towards keeping enough in your fund to cover two to three months of regular expenses. This is the typical waiting period to access your superannuation or insurance in the event that you cannot work. Of course, you may want to consider having enough in there for a longer period.

          Determine What Counts As An Emergency To You

          Set a clear definition as to what constitutes an emergency and stick to it. Replacing a broken toaster, while inconvenient, may be better suited to a “rainy day” fund.

          Open A Savings Account

          Just as you set up an account to reach your savings goals, doing the same for an emergency account will help immensely. Factor this into your 50% part of your budget.

          Consider A Loan

          As we’ve said before, a loan is never a replacement for a savings plan. However, it can be especially useful when you find yourself in an emergency situation. Red Tree Finance has quick and helpful loan options available to help you out when you need it most.

          Take The First Steps Towards A Better Financial Future

          Whether you already have a family budget or creating one is on the to-do list, structure and flexibility go a long way towards securing a better financial future. It enables you to set and achieve small or large financial goals while also maintaining a comfortable day-to-day lifestyle.

          Red Tree Finance can also help you with our household-friendly cash loan options. Whether you’re planning a holiday or fixing up the house, or simply want to cut up your credit card once and for all, speak to us to see how we can assist.

          FAQ – Common Family Budget Questions

          View all FAQs View all FAQs

          The 50/30/20 rule is an easy-to-follow household budgeting system that helps families manage their finances with relative ease. The idea is that you set aside 50% of your after-tax income for essential expenses like food, rent or mortgage payments, and utility bills. You put 30% of your income towards lifestyle expenses that are more “want” than “need”, such as eating at restaurants, streaming subscriptions and other hobbies. The remaining 20% of your income goes into a savings account that may be used as an emergency fund or to achieve a savings goal.

          The 70/20/10 rule is effectively the same as the 50/30/20 rule, but with the percentages adjusted for families that want to set more realistic goals. They may come from more expensive neighbourhoods or be operating on a lower income. You use 70% of your net income for essential expenses and 20% for lifestyle expenses, with the remaining 10% going into savings.

          First and foremost, what you need to do is get a comprehensive understanding of your household finances by listing the money coming in (your income) and the money going out (your expenses). The expenses should include anything that is fixed and consistent, like utility costs, house payments and council rates, and any variable payments. Once you’ve listed your expenses, separate them into essentials and non-essential payments, and work out where you may be able to reduce those expenses. It’s also a good idea to set up a savings account and create clear financial goals using the SMART method.

          The information provided in this blog is of a general nature and is provided without considering your specific objectives, financial situation, or needs. It is intended for informational purposes only and should not be relied upon as financial, investment, or other professional advice.

          Before making any financial decisions or taking action based on the information presented, you are strongly encouraged to assess its appropriateness in light of your individual circumstances. Red Tree Finance does not intend to provide personalised financial advice, and you should seek independent financial, legal, tax, and other relevant advice tailored to your unique situation.
          image
          img
          image
          img
          Apply now

          Ready to apply for a loan?

          Apply to borrow up to $5,000 fast. Complete your online application in under 5 minutes.

          image
          image
          image

          10 Last Minute Date Ideas: On A Budget

          Life can get busy, but planning a last-minute date on a budget doesn’t have to be stressful. Sometimes, a little extra support, like a fast loan, can help you create those special experiences but there are plenty of affordable ways to spend quality time with your partner in Australia.

          Budgeting 13 August 2025

          In this article:

            Calculate your loan repayments

            How much would you like to borrow?

            Simply. Transparent. Tailored to you.

            Loan amount:
            $
            $2,350 $5,000
            Repayment frequency:
            Weekly repayment:

            (Over 12 month loan term)

            $0.00
            • Loan term 12 months
            • Interest & Fees $1,072
            • Total to pay $3,172
            arrow
              image

              Life can get busy, but planning a last-minute date on a budget doesn’t have to be stressful. Sometimes, a little extra support, like a fast loan, can help you create those special experiences but there are plenty of affordable ways to spend quality time with your partner in Australia.

              10 Last Minute Date Ideas: On A Budget

              1. Sunset picnic at the beach

              You don’t need to plan a romantic getaway for your partner when the weather’s warm – you can just head to the closest beach! Pack snacks from home, a blanket, and some cold drinks for a simple and romantic picnic by the ocean. It’s free, and the beach offers a beautiful backdrop for conversations and relaxation. Ideal for mornings, sunsets, or lazy afternoons.

              2. Outdoor movie night in the park

              Not every date needs to be out of the house! If you’re low on income or wanting to save money why not opt for a cosy and affordable date, turn your living room into a home theatre. Choose a movie you’ve both wanted to watch, grab some popcorn, and create a cinema-like experience at home. You can stream movies for free or rent them online, making it a great option when time and money are tight. Perfect for evening wind-downs.

              3. Hiking adventure

              To create a memorable last-minute date, a hiking adventure is an excellent choice. Not only is it budget-friendly – it’s often free if you choose local trails. Hiking also offers a chance to connect with nature and each other. Grab your hiking shoes, pack some water, and set off for a nearby trail.
              This date is perfect for a spontaneous weekend outing or even a weekday evening if you have time to catch the sunset. Plus, the physical activity can release serotonin, boosting mood and energy levels, making it a great date when you want to make a good impression.

              4. Local farmers market

              On the weekend, why not check out a nearby farmers market? It’s free to walk around, and you can grab inexpensive snacks, explore local crafts, and enjoy a relaxed outdoor atmosphere.
              If you’re in Melbourne and looking for a cheap but fun date, you can visit the Queen Victoria market or South Melbourne market. It’s a fun and budget-friendly way to spend a few hours while supporting local producers, you can even save money on your weekly grocery shop at the same time.

              5. Coffee date

              Something super simple but affordable is a cute coffee date. If you’re looking for something quick and easy, find a local café, order your favourite coffee or tea, and sit outside for some people-watching. It’s a low-cost way to enjoy each other’s company, chat, and soak up the local atmosphere. Great for mornings or early afternoons when the world is bustling around you.

              6. Board games or card night

              If you’re in the mood to stay in, challenge your partner to a fun board game or card game. You likely already have a deck of cards or a game at home, making this a zero-cost date idea that can bring out a playful side in both of you. Perfect for a relaxed evening or lazy Sunday afternoon.

              7. Ice cream trip

              Who doesn’t love ice cream? When you’re low on time and looking for a quick, affordable date idea, a spontaneous ice cream or gelato run is perfect. Head to your favourite local spot and enjoy a few scoops together.
              It’s budget-friendly, as ice cream or gelato rarely costs more than a few dollars per person, making it an ideal treat for those on a tight budget.

              Many Australian cities offer free or donation-based entry to museums and galleries. This is a perfect last-minute date when you’re looking for something cultural and interesting to do. You’ll have a chance to explore new exhibits together and spark interesting conversations, all without spending much.
              If you’re in South Australia, both the museum and art gallery are free to explore and are in close proximity to each other, so you can visit both for no cost at all if it fits into your schedule.

              9. Bike ride around town

              A bike ride around your local area is a great last-minute and budget-friendly date idea. If you both have bikes, this date is essentially free! It’s a fun way to explore new parts of town or revisit favourite spots.
              You can pack a small snack or stop at a local park for a rest. This is an ideal daytime date for weekends or evenings when the weather is pleasant, giving you both the chance to enjoy some light exercise and fresh air together without spending much. Plus, it’s flexible – you can adjust the ride length to suit your schedule.

              10. Wine and cheese night

              Create a fancy wine and cheese night at home with supermarket bargains. Buy a budget-friendly bottle of wine and some affordable cheese, crackers, and fruit. Set it up on the dining table or your balcony for an intimate and low-cost evening in.
              This is perfect for a spontaneous evening date when you want to feel indulgent without spending too much.

              Splurge on romance with Red Tree Finance

              You don’t need to spend a fortune to have a memorable time with your partner. These date ideas prove that romance can thrive on a budget but if you are looking to spoil yourself to your partner with a cheap vacation in Australia or fun weekend out, Red Tree Finance is here to help.
              With a small cash loan of up to $5,000, you can cover any unexpected expenses while staying on top of your budget. Apply now for a personal loan and enjoy more stress-free moments with your loved ones.

              Yes, last-minute dates can be a great idea! They add spontaneity and excitement to your relationship, showing that you don’t need elaborate plans to have fun or create meaningful memories.

              Planning a last-minute date is all about keeping it simple. Choose activities that don’t require reservations or lots of preparation, such as a coffee date, stargazing, or a home movie night.

              Yes! Red Tree Finance offers small loans up to $5,000 that can be used for a variety of personal expenses, including treating your partner to a special date.

              The information provided in this blog is of a general nature and is provided without considering your specific objectives, financial situation, or needs. It is intended for informational purposes only and should not be relied upon as financial, investment, or other professional advice.

              Before making any financial decisions or taking action based on the information presented, you are strongly encouraged to assess its appropriateness in light of your individual circumstances. Red Tree Finance does not intend to provide personalised financial advice, and you should seek independent financial, legal, tax, and other relevant advice tailored to your unique situation.
              image
              img
              image
              img
              Apply now

              Ready to apply for a loan?

              Apply to borrow up to $5,000 fast. Complete your online application in under 5 minutes.

              image
              image
              image

              7 Budget-Friendly Tips To Decorate Your Kid’s Bedroom

              Decorating your kid's bedroom can be a long process, from researching the style and staying within budget. That’s why we’ve made this guide to give you 7 different ideas to decorate your kid's bedroom without breaking the bank.

              Budgeting 5 August 2025

              In this article:

                Calculate your loan repayments

                How much would you like to borrow?

                Simply. Transparent. Tailored to you.

                Loan amount:
                $
                $2,350 $5,000
                Repayment frequency:
                Weekly repayment:

                (Over 12 month loan term)

                $0.00
                • Loan term 12 months
                • Interest & Fees $1,072
                • Total to pay $3,172
                arrow
                  image

                  Decorating your kid’s bedroom can be a long process, from researching the style and staying within budget. That’s why we’ve made this guide to give you 7 different ideas to decorate your kid’s bedroom without breaking the bank.

                  Creating A Budget

                  Decorating your kid’s bedroom can be a fun and exciting weekend project but it can also be expensive. That’s why you have to create a budget!

                  Before you start visualising how you want to decorate your kid’s bedroom, it is important to create a budget. Creating a budget allows you to understand how much money you plan on spending and how much the materials will cost. If you find yourself just short of cash, a personal loan may help you purchase the needed materials.

                  Wants and Needs

                  When listing out the materials you will need for your project, consider what is a necessity and what items you could do without. Consider whether there are any cheaper alternatives or if you could repurpose other items from the house, or even buy second-hand instead.

                  If you have an old bookcase you no longer need, could it fit the aesthetic of the new room? If it does not, could you create a newly loved piece of furniture and upcycle the old one? If you decide you do not want to do either then consider if you can sell it for some quick cash to put towards the room.

                  Now that you have created your budget and decided what your wants and needs are, let’s dive into the 7 budget-friendly tips to inspire you to decorate your kid’s bedroom.

                  7 Budget-Friendly Tips To Decorate Your Kid’s Bedroom

                  1. How To Decorate The Walls?

                  When you are planning on painting the walls of your kid’s bedroom, consider whether you want a solid colour, a mix of colours or if you want a picture painted on the wall. Search around for pricing when you are looking for paint to get the best pricing.

                  Painting ideas:

                  • What is their favourite colour?
                  • Do they have a favourite cartoon character that you could theme the wall around?

                  There are so many options to choose from. The wall can be painted in a solid colour or you can paint the wall from light to dark giving it a gradient effect.

                  Whether you want to put stickers, wallpaper or paint pictures on the wall – wall decor is a fantastic way to add character to any room.

                  Wall Decor Ideas:

                  • Do they have a favourite cartoon character that you can paint on the wall?
                  • Do they love to swim? Can you paint sea life on the wall?
                  • Paint a beautiful beach
                  • ABC’s on the wall.

                  Adding characters, sea life, beaches or ABCs gives the room extra detail and a “feature wall”.

                  2. What Furniture To Get?

                  The most important furniture to get in your kid’s bedroom are bookshelves a rocking chair (if they are very young), or items for a play area if they are a little older.

                  When you are researching bookshelves, think about how many children’s books you have and how many you think you might purchase. Look for bookcases that have other shelves that can add more storage options to the room.

                  A rocking chair is one of the most important pieces of furniture to get if you are decorating for a baby. The rocking chair can be used to help get your baby to sleep, whilst also giving more character to the room.

                  If you do not have a built-in wardrobe, then look to get storage cubes that you can separate all the different types of clothes into.

                  3. What Type Of Bed And Linen To Get?

                  Deciding what type of bed and linen to put in the bedroom is important because it takes up so much space. If you are purchasing a bed, look to get a high-quality frame and mattress as these items will last for a long time.

                  A kid’s bedroom only needs a smaller bed, which leaves plenty of room for other furniture. Consider getting a single bed, maybe even a themed bed that is made into the shape of cartoon characters. Save money and look on different marketplace platforms such as Facebook or Gumtree to pick up a second-hand bed frame. In your budget, allocate a larger amount of money towards a mattress and buy brand new. This is because a brand-new mattress lasts for many years and is laid on for 8+ hours a night. If you are getting to the top of your budget and are worried that you may be just short of being able to purchase a new mattress, try these tips to save money fast.

                  The quilt cover and pillowcases should match the theme that you decide to paint the wall. You can save money and search online for these items to compare pricing and different styles.

                  4. Incorporating A Play Area

                  A play area can be as simple as “the corner where the toys go” or you can add things to make the room feel like a fun zone like a ball pit or a drawing station. A play area gives the room some extra life and separates the room between relaxing and playing.

                  5. What Decorations To Hang On The Walls

                  There are many different ways to add temporary decorations to the wall like decor of animals or cartoon characters or simple decorations like love hearts. Adding decorations is an inexpensive idea to give the room extra detail and make the room look incredible. Plus, you can easily update them as your child grows.

                  6. Ideas For The Floor

                  Decorating the floors of your kid’s bedroom will not only add to the design and aesthetics of the room but also save any spillages from leaking into the carpet.

                  To decorate the floor you can add plain carpet to match the colours that you painted the wall in. These act as a barrier so any food, drink or paint will not spill on the bedroom carpet and make the room look gorgeous.

                  Another interactive idea is to add a kid’s city rug. These rugs have a city printed onto them which makes for a ton of fun. All you have to do is get small matchbox toy cars and watch them have fun with their imagination for hours.

                  7. Use Lighting For A Finishing Touch

                  There are so many cheap and affordable lighting options that you can add to a kid’s bedroom for fun or that can be dimmed for lower lighting.

                  The first cheap alternative is to look at LED strip lighting that can be added to the cornices in the bedroom. These LED strip lights can be controlled from a smartphone and can be set to warm, cold or multiple different colours. Adding these lights is a very cheap expense and can give you so much fun together.

                  Another alternative for lighting is to add fairy lights across the ceiling. Fairy lights are very inexpensive and make the room feel magical.

                  Need Help Decorating Your Kid’s Bedroom?

                  Made your budget, find yourself going over and need some extra? The team at Red Tree Finance can help! We offer same-day loans up to $5,000 that can help you transform your kid’s bedroom. If you have any questions or would like to enquire, contact our team today!

                  Designing a kid’s bedroom on a budget is simple. Some budget-friendly ideas include:

                  • Painting a picture on the wall.
                  • Purchasing second-hand furniture or upcycling old unused furniture.
                  • Search for beds on marketplaces.
                  • Create a small play area.
                  • Add LED strip lighting or fairy lights.

                  To decorate your bedroom with a smaller budget, consider looking for second-hand goods. Look for clearance items at hardware and electronics stores that can help add character to your room. Another option is to DIY all of your furniture like bookcases, shelves or drawers.

                  To style a child’s bedroom you should look to:

                  • Decorate the walls with either paint or stickers.
                  • Add furniture like rocking chairs, cabinets, drawers and mirrors.
                  • Match the bedding to the theme of the room.
                  • Add a play area.
                  • Hang up decorations on the wall.
                  • Add a rug or playmat to the floor.
                  • Add LED strip lighting or fairy lights.

                  The information provided in this blog is of a general nature and is provided without considering your specific objectives, financial situation, or needs. It is intended for informational purposes only and should not be relied upon as financial, investment, or other professional advice.Before making any financial decisions or taking action based on the information presented, you are strongly encouraged to assess its appropriateness in light of your individual circumstances. Red Tree Finance does not intend to provide personalised financial advice, and you should seek independent financial, legal, tax, and other relevant advice tailored to your unique situation.

                  image
                  img
                  image
                  img
                  Apply now

                  Ready to apply for a loan?

                  Apply to borrow up to $5,000 fast. Complete your online application in under 5 minutes.

                  image
                  image
                  image

                  Decorating on a Budget: Refresh Your Space Without Draining Your Savings

                  Creating a beautiful home doesn't have to cost a fortune. But sometimes it can be hard to get the cash together for a weekend of redecorating. If you're short on cash but eager to get started on your decorating, our budget-friendly ideas will help you transform your living space while keeping your finances in check.

                  Budgeting 29 July 2025

                  In this article:

                    Calculate your loan repayments

                    How much would you like to borrow?

                    Simply. Transparent. Tailored to you.

                    Loan amount:
                    $
                    $2,350 $5,000
                    Repayment frequency:
                    Weekly repayment:

                    (Over 12 month loan term)

                    $0.00
                    • Loan term 12 months
                    • Interest & Fees $1,072
                    • Total to pay $3,172
                    arrow
                      image

                      Creating a beautiful home doesn’t have to cost a fortune. But sometimes it can be hard to get the cash together for a weekend of redecorating. If you’re short on cash but eager to get started on your decorating, our budget-friendly ideas will help you transform your living space while keeping your finances in check. Whether you’re a first-time homeowner, a renter looking to personalise your space, or simply wanting to refresh your current décor, there are plenty of ways to achieve a stylish look without overspending.

                      Why Budget-Friendly Home Décor Matters

                      Your home is your sanctuary, and how it looks and feels can significantly impact your daily life. However, overspending on décor can lead to financial stress, which is counterproductive to creating a relaxing home environment.

                      As with any financial decision, planning is key to avoid overspending. Determine how much you can comfortably spend and create a budget for your home décor project. You can try setting aside a specific amount each month for home improvements, or a personal loan might fit into your budget if you need extra funds sooner.

                      Affordable Ways to Update Your Home’s Décor

                      There are a variety of budget-friendly strategies that can breathe new life into your living spaces without emptying your wallet. Whether you want to refresh a single room or give your entire home a makeover, these affordable solutions will help you achieve a stylish and inviting atmosphere. Get ready to discover how small changes can make a big impact!

                      Embrace the Power of Paint

                      One of the most cost-effective ways to dramatically change the look of a room is with a fresh coat of paint. Choose light colours to make small spaces feel larger and brighter. Don’t limit yourself to walls – consider painting old furniture pieces for an instant update.

                      Mix High-End and Low-Cost Pieces

                      Creating a stylish home on a budget doesn’t mean everything has to be cheap. The key is to invest wisely in a few statement pieces and complement them with more affordable items. Look for sales at high-end stores or consider second-hand options for quality pieces at reduced prices.

                      DIY Projects

                      Engage in simple DIY projects to add a personal touch to your space. From creating your own wall art to upcycling furniture, these projects can be fun and budget-friendly. Plus, they add a unique character to your home that can’t be bought off the shelf.

                      Thrift Store Treasures

                      Don’t underestimate the potential of thrift stores and online marketplaces. These are goldmines for finding unique and affordable décor items. With a little creativity, you can transform second-hand finds into stylish additions to your home.

                      Where to Find Budget-Friendly Home Décor Items in Australia

                      Whether you’re hunting for decorative accents or essential furnishings, finding stylish home décor on a budget is easier than ever, thanks to a variety of accessible options across Australia.

                      Kmart and Other Budget Retailers

                      Stores like Kmart offer a wide range of affordable home goods, from furniture to decorative items. Keep an eye out for their seasonal sales for even better deals.

                      Online Marketplaces

                      Platforms like Facebook Marketplace are excellent for finding second-hand items at bargain prices. You might stumble upon vintage treasures or barely-used modern pieces that fit your style perfectly.

                      The Base Warehouse

                      This online store is a great resource for discount homewares. You can find stylish items for every room without overspending.

                      H&M Home

                      Known for its trendy and affordable décor, H&M Home offers a variety of items including linens, cushions, and decorative accessories that can quickly update your space.

                      Tips for Mixing High-End and Low-Cost Décor Pieces

                      Creating a beautifully curated space that reflects your personal style doesn’t have to mean sacrificing quality for affordability. By understanding where to splurge and where to save, you can create a harmonious balance that elevates your home’s aesthetic.

                      Start with a Neutral Base

                      Use neutral colours for large furniture pieces. This allows you to add personality through less expensive accessories without clashing styles.

                      Invest in Statement Pieces

                      Choose one or two high-quality items as focal points in a room. These could be artwork, a designer chair, or a unique light fixture. Surround these with more affordable pieces to create a balanced look.

                      Layer Textures and Materials

                      Use cushions, throws, and rugs in various materials to add depth and interest to your space. Mixing textures can create a rich, luxurious feel even with budget-friendly items.

                      Making Small Spaces Look Stylish on a Budget

                      Living in a small space doesn’t mean you have to compromise on style or comfort. Whether you’re dealing with a tiny apartment, a cosy studio, or a minimalist room, there are countless ways to maximise your space while maintaining an inviting atmosphere.

                      Use Mirrors Strategically

                      Mirrors can make a small space feel larger and brighter. Place them opposite windows to maximise natural light.

                      Opt for Multi-Functional Furniture

                      In small spaces, every piece of furniture should earn its keep. Look for items that serve multiple purposes, like a coffee table with storage or a sofa bed.

                      Vertical Storage Solutions

                      Utilise vertical space with wall-mounted shelves or tall bookcases. This keeps the floor clear and draws the eye upward, making the room feel more spacious.

                      Smart Financial Strategies for Home Decorating

                      While updating your home is exciting, it’s important to approach it with a sound financial strategy. Here are some tips to keep your décor dreams aligned with your financial goals:

                      1. Set a Realistic Budget

                      Determine how much you can comfortably spend on home décor without straining your finances. Make sure you account for all bills and other financial responsibilities before allocating money to your decorating budget.

                      2. Find Ways to Save Money

                      When taking a look at your budget try to find ways you can cut costs in other areas. Saving money on your utility bills or consolidating debt to lower your repayments can help free up cash for your project.

                      3. Prioritize Your Purchases

                      Focus on items that will make the biggest impact first. This might mean investing in a quality sofa before splurging on decorative accessories.

                      4. Shop Smart

                      Take advantage of sales, compare prices across different stores, and don’t be afraid to negotiate, especially when buying second-hand items.

                      5. Gradual Updates

                      Instead of trying to redecorate your entire home at once, consider updating one room at a time. This approach can be more manageable financially and allows you to save for higher-quality pieces over time.

                      Your Stylish Home Awaits

                      Creating a beautiful home on a budget is entirely possible with some creativity, smart shopping, and financial planning. The goal is to create a space that reflects your personality and makes you feel comfortable without causing financial stress.

                      By combining these budget-friendly décor ideas with sound financial strategies, you can create a stylish living space that doesn’t break the bank. Start small, plan wisely, and watch as your dream home takes shape – one affordable piece at a time.

                      Remember, whether you’re moving into a new home, or decorating your current space, a beautiful home and financial stability can go hand in hand. If you’re considering a loan for your home improvement project, explore our online loan options or contact our friendly team if you have any questions.

                      You can decorate your house without spending money by repurposing items you already have, creating DIY art, and swapping décor with friends. Bring nature indoors using branches or flowers from your garden, and rearrange your furniture to create a fresh look. Decluttering can also make your space feel more open and inviting.

                      A good budget for interior decorating typically ranges from $1,000 to $5,000 for a single room and $2,000 to $12,000 for multiple rooms. Whole house designs usually start at $5,000 and can exceed $20,000, depending on size and complexity.

                      The 60-30-10 rule is a decorating guideline for achieving a balanced colour scheme. It suggests that 60% of the space should be a primary colour, 30% a secondary colour, and 10% an accent colour. This approach creates a cohesive and visually appealing environment.

                      The information provided in this blog is of a general nature and is provided without considering your specific objectives, financial situation, or needs. It is intended for informational purposes only and should not be relied upon as financial, investment, or other professional advice.Before making any financial decisions or taking action based on the information presented, you are strongly encouraged to assess its appropriateness in light of your individual circumstances. Red Tree Finance does not intend to provide personalised financial advice, and you should seek independent financial, legal, tax, and other relevant advice tailored to your unique situation.
                      image
                      img
                      image
                      img
                      Apply now

                      Ready to apply for a loan?

                      Apply to borrow up to $5,000 fast. Complete your online application in under 5 minutes.

                      image
                      image
                      image

                      Create A Positive Money Mindset: 6 Tips to Rewire Your Brain

                      If you want to create a positive money mindset, it starts with how you think about money and manage it day to day. Every Aussie has a different lifestyle and therefore a different relationship with money, so there’s no single, cookie-cutter solution. But what you can do is reshape your mindset, build better habits, and

                      Guide 26 July 2025

                      In this article:

                        Calculate your loan repayments

                        How much would you like to borrow?

                        Simply. Transparent. Tailored to you.

                        Loan amount:
                        $
                        $2,350 $5,000
                        Repayment frequency:
                        Weekly repayment:

                        (Over 12 month loan term)

                        $0.00
                        • Loan term 12 months
                        • Interest & Fees $1,072
                        • Total to pay $3,172
                        arrow
                          image

                          If you want to create a positive money mindset, it starts with how you think about money and manage it day to day. Every Aussie has a different lifestyle and therefore a different relationship with money, so there’s no single, cookie-cutter solution. But what you can do is reshape your mindset, build better habits, and take control of your financial future.

                          How to Create a Positive Money Mindset

                          Changing your money mindset doesn’t happen overnight. Turning old habits into new, positive ones takes patience and persistence. The good news? There are simple ways to help you build a better relationship with your money. Here are six tips to create a positive money mindset that works in everyday life.

                          1. Understand Your Relationship with Money

                          Start by reflecting on how money makes you feel. Do bills trigger stress, or do you feel confident when you’ve got a budget and a plan in place? Naming those emotions helps you understand your current relationship with money and why you might respond the way you do in different situations.

                          Once you’ve identified where you stand, it’s time to take action. Write down essentials such as rent, rego, fuel and groceries, then separate extras like streaming services, gym memberships and takeaway.

                          A simple budget gives you a clear picture of where your money goes and where you can trim unnecessary spending. Use our How To Create A Household Budget In Excel: A Step-By-Step Guide to help you get started.

                          Understanding both your emotions and your numbers gives you clarity. When you know how money makes you feel and where it actually goes, you’re in a stronger position to make positive changes.

                          2. Learn to Forgive Yourself for any Fast Money Mistakes

                          Everyone has moments they regret when it comes to money. Maybe it was relying too heavily on buy now pay later, maxing out a credit card, or missing a repayment when things were tight. These experiences can weigh heavily on you and shape the way you feel about money.

                          The key is to recognise those mistakes as lessons rather than baggage. Use the experience as a learning opportunity and move forward. When you park the guilt, you free your mind to focus on building stronger habits like planning budgets and repayments, setting reminders for bills, or creating a small buffer to avoid the same stress again in the future.

                          Forgiving yourself lightens the load. It’s easier to move into a positive money mindset when you stop punishing yourself for the past and start shaping a better future.

                          3. Change the Way You Internalise Money Conversations

                          Changing the way you talk to yourself about money is another important mindset shift to take. If you keep telling yourself you are hopeless with money, saving will feel like an impossible feat. Swap it for language that backs your goals, and you’ll see your mindset also change.

                          Celebrate the wins. Pay your rego on time, save as much as you can each week, cook something nice at home and cancel an unused subscription. All of these steps lead to bigger things and once you start noticing that all the small steps lead to bigger goals, you will have a new level of confidence about how you see money.

                          A kinder inner voice makes the journey easier. By changing the way you talk to yourself about money, you create space for patience, encouragement and progress.

                          4. Focus on Your Money Goals

                          Having a positive money mindset isn’t just about how you think. It is also about knowing where you are heading. Clear money goals give your financial choices direction and purpose. Whether it is saving for a deposit, paying down HECS-HELP debt, or putting money aside for a holiday or an emergency, having goals helps you stay motivated.

                          Once your goals are set, break them into smaller milestones you can work towards. For example, saving $100 a week for six months feels more achievable than aiming for a lump sum all at once. Tracking progress this way keeps you accountable and makes each step feel rewarding.

                          Clear financial goals turn everyday actions into progress. Instead of focusing on what you are giving up, you can focus on what you are gaining: stability, confidence and momentum.

                          5. Stop Comparing Your Financial Situation to Others

                          It is easy to feel like you are falling behind when friends post holiday photos on Instagram or when a neighbour buys a new car. These comparisons are a one-way ticket to frustration and make you feel like your own progress is not enough.

                          Instead of looking at others, measure your success against your own goals. Track improvements like paying off a loan, building savings, or sticking to a budget for three months straight. Each step forward is proof that you are moving in the right direction.

                          A positive money mindset comes from focusing on your journey. When you stop comparing yourself to others, you gain back the confidence to focus on your own progress.

                          6. Create Strong Money Habits

                          Your daily habits shape how you feel about money. If every dollar is spent as soon as it arrives, saving will always feel out of reach. Building consistent habits, even in small amounts, is the foundation of long-term confidence.

                          Start by reviewing where your money goes. Essentials like rent, fuel and groceries will always take priority, but extras such as subscriptions, gym memberships or takeaway can often be trimmed. Once you have made some space in your budget, set up an automatic transfer into a savings account each payday. Even a small, regular amount builds momentum over time.

                          Amount saved per week Total saved in exactly one year
                          • $100
                          • $5,200
                          • $200
                          • $10,400
                          • $300
                          • $15,600
                          • $400
                          • $20,800
                          • $500
                          • $26,000

                          A savings habit backed by simple routines makes money management second nature. With consistency, you spend less time worrying about money and more time enjoying the security that comes from having a buffer in place.

                          Create a Positive Money Mindset Through Education

                          Mindset shapes how you feel about money, but knowledge gives you the tools to do something about it. Without a basic understanding of how money works, even the best intentions can fall short, so it’s important to learn the fundamentals to make decisions with more confidence.

                          Start by brushing up on everyday financial concepts such as compound interest, credit scores, debt management and superannuation. Moneysmart provides useful resources to help you understand how to use your finances better. Exploring trusted sources like these gives you practical knowledge you can apply immediately.

                          Education lays the foundation for a positive money mindset by replacing uncertainty with clarity. When you know how money works, it is easier to stay in control and stick to the financial habits that support your goals.

                          Chase your money goals with Red Tree Finance

                          A positive money mindset is about making steady progress and feeling confident about the future. Even with the best habits, unexpected costs can still appear and test your plans. Having flexible support when you need it can make all the difference.

                          Red Tree Finance offers personal loans of up to $5,000 that can be applied for entirely online. The process is fast and straightforward, designed to help you cover essentials such as car repairs, bills or upgrades without derailing your long-term goals.

                          A positive money mindset works best when you balance planning with adaptability. With Red Tree Finance, you can handle today’s challenges while keeping your focus on tomorrow. You can apply online today or, if you prefer, talk with our customer service team about the best way forward for you.

                          Frequently asked questions

                          View all FAQs View all FAQs

                          The first step to creating a positive money mindset is awareness. Look at how you feel about money — whether it stresses you out, motivates you, or leaves you indifferent — and then take a practical step by creating a simple budget. Separate essentials like housing, utilities and groceries from extras such as subscriptions or entertainment. This shows you where your money is going and where changes are possible.

                          Once you’ve mapped things out, set realistic goals and break them into small, achievable steps. For example, saving a set amount each week is more motivating than aiming for a large lump sum. Pair this with positive self-talk and regular check-ins on your progress. Over time, the combination of awareness, planning and habit-building shifts your mindset from feeling controlled by money to feeling in control of it.

                          A negative mindset often shows up as constant stress about bills, guilt after spending, or avoiding looking at bank statements. You might also compare yourself to others, feel like you’ll never get ahead, or carry regret about past financial decisions.

                          These thought patterns can create a cycle that makes managing money harder than it needs to be. Recognising them is the first step in breaking the pattern. By becoming aware of these habits, you open the door to building a more constructive relationship with money.

                          Yes. Big transformations usually start with small, consistent changes. Simple steps like paying bills on time, setting up an automatic transfer into savings, or cooking at home instead of ordering in may feel minor, but over time, they add up to major progress.

                          Each small win helps build confidence and reduces financial stress. As your habits improve, your mindset shifts too — from feeling stuck or overwhelmed to feeling capable and forward-looking.

                          The information provided in this blog is of a general nature and is provided without considering your specific objectives, financial situation, or needs. It is intended for informational purposes only and should not be relied upon as financial, investment, or other professional advice.

                          Before making any financial decisions or taking action based on the information presented, you are strongly encouraged to assess its appropriateness in light of your individual circumstances. Red Tree Finance does not intend to provide personalised financial advice, and you should seek independent financial, legal, tax, and other relevant advice tailored to your unique situation.
                          image
                          img
                          image
                          img
                          Apply now

                          Ready to apply for a loan?

                          Apply to borrow up to $5,000 fast. Complete your online application in under 5 minutes.

                          image
                          image
                          image

                          6 Strategies To Save Money On Back To School Expenses

                          The school holidays are nearly over, and as much fun as they have been, it means it’s time for those yearly back-to-school expenses. These expenses can be stressful for Aussie families, so we have 6 strategies to help you save money when purchasing equipment for school.

                          Budgeting 24 July 2025

                          In this article:

                            Calculate your loan repayments

                            How much would you like to borrow?

                            Simply. Transparent. Tailored to you.

                            Loan amount:
                            $
                            $2,350 $5,000
                            Repayment frequency:
                            Weekly repayment:

                            (Over 12 month loan term)

                            $0.00
                            • Loan term 12 months
                            • Interest & Fees $1,072
                            • Total to pay $3,172
                            arrow
                              image

                              The school holidays are nearly over, and as much fun as they have been, it means it’s time for those yearly back-to-school expenses. These expenses can be stressful for Aussie families, so we have 6 strategies to help you save money when purchasing equipment for school.

                              6 Strategies To Save Money On Back To School Expenses

                              The best place to start planning for your back-to-school expenses is to create a budget and stick to it. Budgets allow you to allocate how much money you expect to spend on each type of expense. Split your expenses into essential and nonessential expenses – this will help you know what to cut if you need to save money.

                              Now that you have your budget made, let’s dive into the 6 strategies to help you save money on your back-to-school expenses.

                              1. Buy Second-Hand Uniforms

                              While your kids are growing up and going through school, their uniforms are going to be a big expense each year. When purchasing school uniforms, look for second-hand items that are in great condition. This can sometimes save you half the cost, giving you a great deal.

                              Kids grow fast, which means that they will outgrow their school uniforms quickly. When purchasing school uniforms, look to go an extra size up. This will give your school uniforms some extra time as your kids are growing, meaning you won’t have to buy them new ones next year.

                              2. Shop The Sales On Equipment and Technology

                              One of your biggest back-to-school expenses is equipment and technology like school bags, books, stationery, and a laptop. There are so many different brands available on the market so it is important to shop around. Look for the best sales and compare different retailers.

                              When you are searching for a laptop, and if your budget allows, make sure you get a mid to high-range laptop. By getting a good laptop, you may get more time out of the laptop, saving you more money than replacing a cheaper one that is likely to break. Get a cover and case as well to keep the device safe during transport from school to home.

                              If you need help purchasing a laptop. a personal loan can help you make sure you get a reliable laptop.

                              3. Plan Lunches For The Week

                              Buying ingredients in bulk and preparing lunches at home for your kids can reduce your food costs. Make a shopping list and avoid purchasing unnecessary food items for snacks. Look to purchase cold meats such as chicken or ham, which are cheap and perfect options to make sandwiches or wraps for lunches.

                              Cooking at home is cheaper and more nutritious than purchasing lunch at the school canteen. Use lunch orders at the canteen as a reward every fortnight or month as a reward for finishing homework. This will help you save money and may even give your kids motivation to put effort into their classes and learning.

                              4. Budget for Extracurricular Activities

                              Extracurricular activities like school camps or excursions can creep up and force you to find extra money fast. In your budget, set aside some extra money that can be used for these activities.

                              These school activities are usually not too expensive but can catch you off guard. The best thing you can do is add more to your budget so you are prepared and no one misses out.

                              5. Label Everything

                              In a busy classroom, kids will typically forget which laptops, stationery or books are theirs and accidentally take the wrong ones home. The easiest way to prevent you from having to purchase these items again is to label everything.

                              Labelling your kid’s equipment and stationery makes it very easy to determine if the items are theirs or not. For parents, repurchasing the same items can add up, especially if it happens frequently.

                              6. Push Back Any Unessential Expenses

                              Sometimes, it becomes a habit to purchase new items like school uniforms, laptops and stationery each year when the old ones are in perfect working condition. Consider if these items need to be purchased or if you could use them for another year. If you have multiple kids in school, repurpose these items and pass them down to your younger children.

                              Tips To Help You Save Ahead Of Time

                              Plan out how much you can save per week to put towards school expenses. Some of the best ways to save some extra money include:

                              • The start of school holidays usually happens right before New Year’s, use this as an indicator to start saving for the back-to-school expenses.
                              • Shop during the Black Friday and Boxing Day sales to get some early deals. If you miss these, retailers will usually do back-to-school sales.
                              • Use big-ticket items like a laptop as a Christmas gift to save money. Because it is such a big purchase, your kids will be very happy.
                              • Budgeting an extra $50 per week would give you an extra $2,600 per year to ease the pressure of school bills.
                              • Search marketplaces like Gumtree, Facebook marketplace or eBay for some great second-hand deals – think uniforms, stationary or unused books.

                              Prepare for back-to-school expenses with Red Tree Finance

                              Now that you are aware of those back-to-school expenses, it is time to start saving and budgeting. If you still need some extra financial help, Red Tree Finance can help. We offer same-day and instant loans up to $5,000 to help you shop those back-to-school sales.

                              Frequently asked questions

                              View all FAQs View all FAQs

                              In 2025, the average amount of money spent on school supplies is $694 for primary school students and $1,149 for secondary school students. The amount of money you will need depends on what items need to be purchased.

                              A good budget for back to school shopping depends on what you plan to reuse. For example, if you just need supplies and school uniforms, then aim for a budget of $500. However, if you need to purchase a laptop, supplies and school uniforms, then you may need to budget around $1,500.

                              In 2025, the average school fees are:

                              For primary school:

                              • $780 in fee/voluntary contributions
                              • $694 in school supplies
                              • $1,197 in other costs

                              For Secondary school:

                              • $2,231 in fee/voluntary contributions
                              • $1,149 in school supplies
                              • $1,663 in other costs

                              The information provided in this blog is of a general nature and is provided without considering your specific objectives, financial situation, or needs. It is intended for informational purposes only and should not be relied upon as financial, investment, or other professional advice.

                              Before making any financial decisions or taking action based on the information presented, you are strongly encouraged to assess its appropriateness in light of your individual circumstances. Red Tree Finance does not intend to provide personalised financial advice, and you should seek independent financial, legal, tax, and other relevant advice tailored to your unique situation.
                              image
                              img
                              image
                              img
                              Apply now

                              Ready to apply for a loan?

                              Apply to borrow up to $5,000 fast. Complete your online application in under 5 minutes.

                              image
                              image
                              image

                              15 Gift Ideas Under $5

                              Here are 15 of the best $5 gift ideas for when you're on a budget! From DIY scrubs to plants and personalised bookmarks. Being generous shouldn’t break the bank!

                              Budgeting 28 January 2025

                              In this article:

                                Calculate your loan repayments

                                How much would you like to borrow?

                                Simply. Transparent. Tailored to you.

                                Loan amount:
                                $
                                $2,350 $5,000
                                Repayment frequency:
                                Weekly repayment:

                                (Over 12 month loan term)

                                $0.00
                                • Loan term 12 months
                                • Interest & Fees $1,072
                                • Total to pay $3,172
                                arrow
                                  image

                                  Here are 15 of the best $5 gift ideas for when you’re on a budget! From DIY scrubs to plants and personalised bookmarks. Being generous shouldn’t break the bank!

                                  15 $5 gift ideas

                                  1. Homemade Baked Goods

                                  Nothing says love like a homemade treat! A batch of cookies or brownies is both affordable and thoughtful, making it a great gift for coworkers, neighbours, or even a great but affordable Easter gift!

                                  You can personalise baked goods by using different ingredients, and flavours, or by adding a handwritten recipe card. Most ingredients like flour, sugar, and chocolate chips are inexpensive or already a pantry staple, and you can bake a large batch to share with multiple people – keeping costs under $5 per serve!

                                  Cheap gift idea under $5: homemade baked goods | Red Tree Finance

                                  2. Handwritten Letter or Card

                                  In today’s digital age, a handwritten letter or card can feel extra special. Expressing your feelings or sharing memories can mean far more than any store-bought item. You can get creative by decorating the card or using materials you already have at home.

                                  This gift is ideal for close friends, partners, or family members and is especially perfect for those who appreciate meaningful gestures. The cost? Almost nothing except some paper, pens, and maybe a postage stamp if you need to mail it.

                                  3. DIY Bath Salts/Sugar Scrub

                                  A luxurious spa experience doesn’t have to come with a hefty price tag. With simple ingredients like Epsom salts, essential oils, and dried flowers, you can create a relaxing bath salt mix.

                                  Another spa DIY is a sugar scrub, with just a few ingredients – sugar, coconut oil and some essential oils, you can give a relaxing experience to someone special. Package it in a jar or small bag and tie it with a ribbon for a personal touch.

                                  This gift is perfect for anyone who could use some self-care, from a stressed-out parent to a busy friend. Best of all, it can easily be made for under $5 and feels much more expensive than it is.

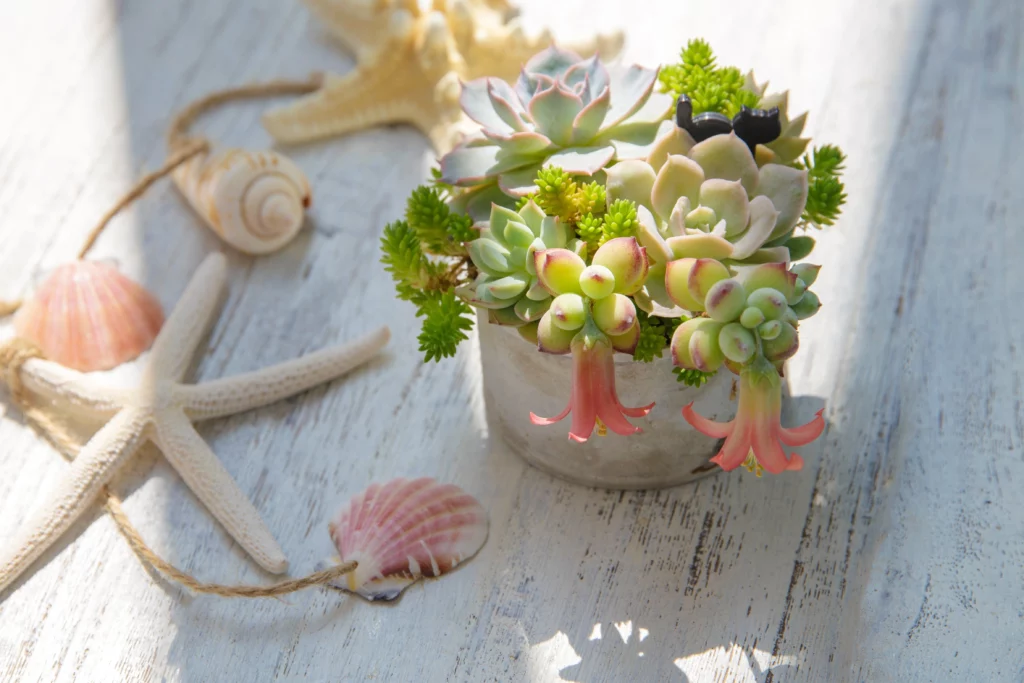
                                  4. Succulent Plant

                                  Succulents are trendy, low-maintenance plants that make for a charming and long-lasting gift. These little green wonders can often be found for $5 or less at nurseries, plant stores, or even supermarkets.

                                  They’re perfect for anyone, especially those who don’t have a green thumb, as they require minimal watering and care. A small potted succulent can brighten up a desk, windowsill, or living room space.

                                  Budget gift idea under five dollars: succulents | Red Tree Finance

                                  5. Second-Hand Books

                                  Thrift stores and second-hand bookstores are gold mines for finding excellent books at super low prices. Whether it’s a novel, self-help book, or a vintage cookbook, you can often find unique gems for under $5.

                                  Books make thoughtful gifts for readers, students, or even someone who’s been talking about picking up a new hobby. Personalise the gift by writing a message inside the front cover, making it extra meaningful.

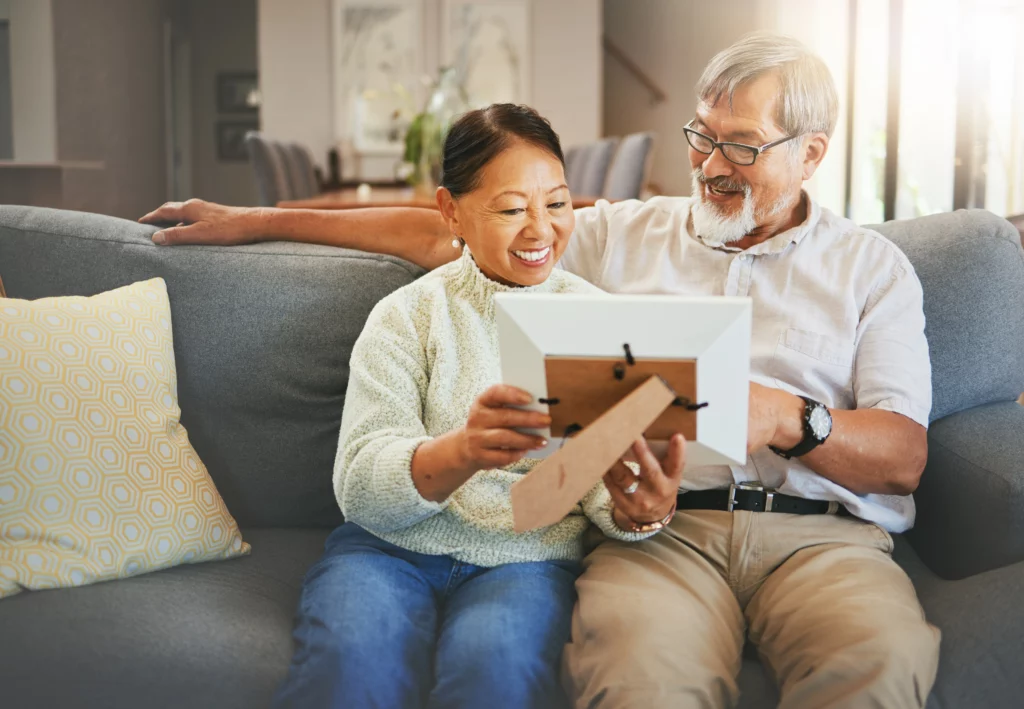
                                  6. Framed Photo

                                  A framed photo is a timeless and sentimental gift. You can print a cherished memory, like a family vacation or a fun day out with friends, and place it in an affordable frame from a dollar store.

                                  This is a great way to celebrate special moments and it’s an excellent gift for grandparents, parents, or close friends. The cost of printing a photo and buying a frame can easily stay under $5, but the sentimental value is priceless.

                                  Low cost give idea under $5: framed photo | Red Tree Finance

                                  7. Fun socks

                                  Fun, quirky socks are a practical and playful gift. You can often find socks with unique patterns, characters, or funny phrases for under $5, either at discount stores or online.

                                  They’re perfect for people who love adding a bit of personality to their wardrobe or for someone who loves cosy socks during the colder months. Plus, everyone can always use a new pair of socks!

                                  8. Personalised Bookmark

                                  If you know someone who loves to read, a personalised bookmark is a thoughtful and budget-friendly gift. You can create your own using craft supplies like cardstock, paint, or markers. Add a personal message, favourite quote, or even some artwork.

                                  It’s a gift that’s practical, creative, and unique. This gift works perfectly for book lovers of all ages, and it’s nearly free to make with materials you likely already have at home.

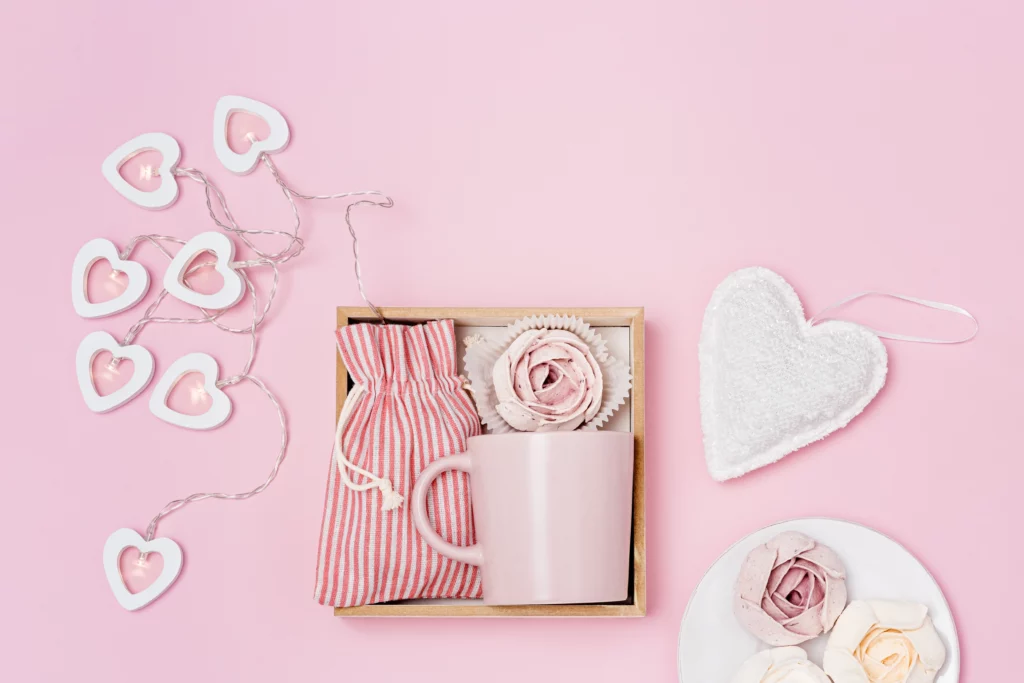
                                  9. Mug & Tea Set

                                  A cosy cup of tea makes for a comforting gift, and you can easily create a tea and mug set for under $5. You can find cheap trendy mugs at discount stores or thrift shops, add a few tea bags into the cup you have lying around at home, decorate with a ribbon and voila! This is an ideal gift for friends or coworkers who enjoy winding down with a hot drink.

                                  $5 gift ideas: tea and mug set | Red Tree Finance

                                  10. Mini Candle

                                  Maybe if you can’t afford a romantic getaway, you can bring the romance into that special someone’s home! Candles are a small luxury that can make a big impact. Mini candles, especially in soothing scents like lavender or vanilla, can often be found on sale for less than $5 at various stores.

                                  They’re perfect for setting a calming ambience in a home, making them a wonderful gift for your partner who enjoys relaxing or creating a cosy atmosphere. They’re also a great addition to care packages or stocking stuffers.

                                  11. Homemade Hot Chocolate Kit

                                  Create a DIY hot chocolate kit by packaging cocoa powder, marshmallows, and maybe even some peppermint in a small jar or bag. This cosy and delicious gift is perfect for cold winter nights, making it ideal for anyone who enjoys a warm drink during the holiday season. It’s a fun and budget-friendly gift that costs less than $5 but feels like a thoughtful treat.

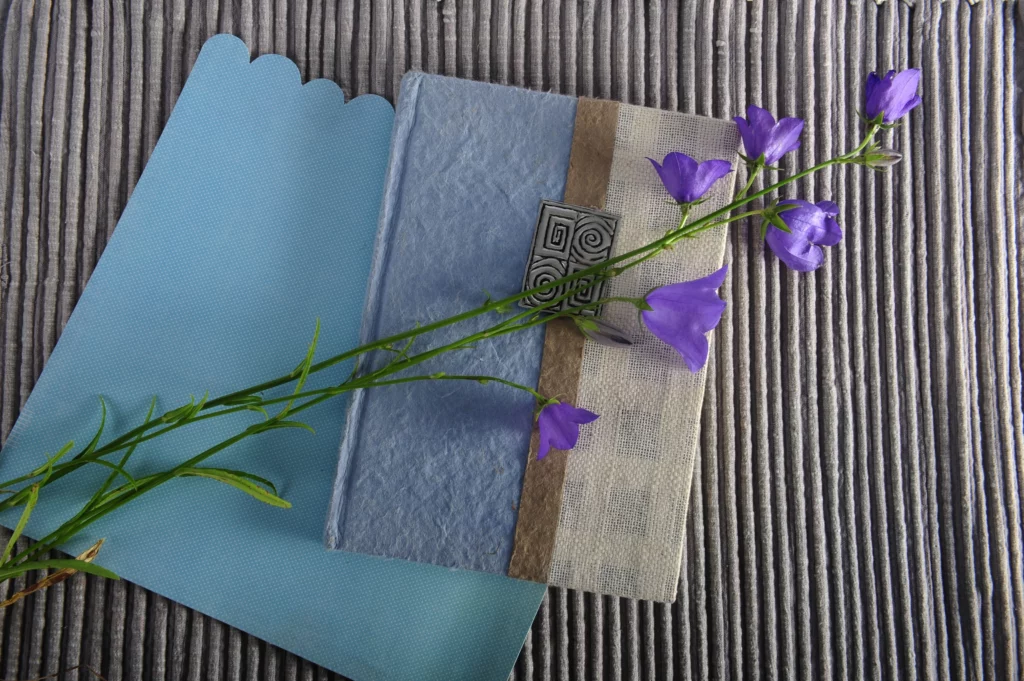
                                  12. Decorative Notebooks or Journals

                                  At discount stores, you can find cute and decorative notebooks or journals for under $5. These make practical and thoughtful gifts for people who enjoy writing, journaling, or note-taking.

                                  It’s an ideal gift for students, creative types, or anyone who likes to stay organised with their bills or work schedule. You can even add a personalised touch by writing a motivational quote or message on the first page.

                                  Low cost present: journal or notebook | Red Tree Finance

                                  13. Puzzle or Brain Teaser

                                  Small puzzles, Rubik’s cubes, or brain teaser games are fun and inexpensive gifts for both kids and adults. They offer entertainment and a challenge, and you can often find them in the toy or game sections of dollar stores. These are great stocking stuffers or small gifts for anyone who enjoys testing their mental skills or simply having a bit of fun.

                                  14. Reusable Straws

                                  For the eco-conscious friend or family member, a set of reusable metal or silicone straws is an excellent gift. Many stores sell these for under $5, and they’re a practical way to reduce single-use plastic waste. This gift is not only useful but also environmentally friendly, making it great for people who love sustainable living.

                                  15. Local Handmade Soap

                                  Handmade soap bars are often available at local markets for under $5. These bars are usually made with natural ingredients and come in a variety of scents and designs.

                                  They make great gifts for anyone who loves self-care, and the fact that they’re handmade adds a special, thoughtful touch.

                                  Cheap gift: handmade soap | Red Tree Finance

                                  Celebrate the important stuff with Red Tree Finance

                                  These affordable $5 gift ideas prove that you don’t need to spend a fortune to show someone you care. From DIY projects to thoughtful finds, you can give meaningful and practical gifts without going over your budget.

                                  However, if you’re finding yourself needing a bit of extra financial support for the holidays, birthdays, or any occasion, Red Tree Finance can help. A small cash loan up to $5,000 can provide the extra funds you need to make the most of your celebrations. Apply now for a personal loan to relieve the stress and enjoy giving.

                                  Want to know more? Find out how to get a quick loan using your car as collateral or contact us for more information.

                                  Gift cards are among the most popular gifts, allowing recipients to choose what they really need or want. They’re versatile and fit any occasion, from birthdays to Christmas.

                                  Some good small gifts to show appreciation:

                                  • Handwritten letter
                                  • Flowers
                                  • Homemade treats
                                  • Hand Lotions
                                  • Framed picture

                                  You can apply for up to $5,000 with a Red Tree Finance online loan, depending on your financial needs and eligibility.

                                  People also read:

                                  image
                                  img
                                  image
                                  img
                                  Apply now

                                  Ready to apply for a loan?

                                  Apply to borrow up to $5,000 fast. Complete your online application in under 5 minutes.

                                  image
                                  image
                                  image

                                  How To Create A Household Budget In Excel: A Step-By-Step Guide

                                  Using Excel to create a household budget is an effective way to track and manage your finances. Excel is a powerful and effective tool that allows you to visualise your income, spending, emergency savings and opportunities to reduce your spending. In this guide, learn how to create a budget, step-by-step in Excel, to help you

                                  Budgeting 17 July 2023

                                  In this article:

                                    Calculate your loan repayments

                                    How much would you like to borrow?

                                    Simply. Transparent. Tailored to you.

                                    Loan amount:
                                    $
                                    $2,350 $5,000
                                    Repayment frequency:
                                    Weekly repayment:

                                    (Over 12 month loan term)

                                    $0.00
                                    • Loan term 12 months
                                    • Interest & Fees $1,072
                                    • Total to pay $3,172
                                    arrow
                                      image

                                      Using Excel to create a household budget is an effective way to track and manage your finances. Excel is a powerful and effective tool that allows you to visualise your income, spending, emergency savings and opportunities to reduce your spending. In this guide, learn how to create a budget, step-by-step in Excel, to help you take control of your finances.

                                      How to Make A Budget In Excel

                                      1. Gather your information

                                      First, you need to gather all of your financial details. This includes:

                                      Your income:

                                      • How much money you make each week
                                      • Any allowances

                                      Your expenses:

                                      • Debt repayments
                                      • Food expenses
                                      • Monthly subscriptions
                                      • Essential bills – think water, gas, electricity rent
                                      • Travel expenses

                                      2. Open Excel and set it up

                                      Now it’s time to create a budgeting spreadsheet in Excel.

                                      Open Microsoft Excel on your computer and start a new workbook. You’ll see a blank sheet.
                                      Rename one sheet as “Budget” and another sheet as “Summary.” This will make it easier to keep everything organised.

                                      You can also get inspiration from these free budget templates or download this Excel spreadsheet template and just fill in your details.

                                      3. Track your income & expenses

                                      In the “Budget” sheet, make a table with two columns. In the first column, write down any income from your job and any allowances you receive. In the second column, write down how much money you get for each source.

                                      Below the income table, create another table with two columns. In the first column, write down different categories for your total expenses, like food, transportation, entertainment, and so on.

                                      In the second column, write down how much money you think you’ll spend in each category. Use your recent banking transactions as a guide — it’s easy to underestimate things like groceries or fuel expenses.

                                      Your final budget should include a buffer to save a little each pay cycle for when emergencies arise. An emergency fund can give you peace of mind to navigate the unexpected, like a car breakdown, a vet bill or time off work.

                                      4. Let Excel do the maths

                                      In the “Summary” sheet, create a table that mirrors the one in the “Budget” sheet. In the last row of the “Budget” sheet, use the formula “=SUM” to calculate the total income and expenses. Excel will automatically update this sum as you adjust figures in your budget.

                                      5. Visualise your budget

                                      Excel has some cool features that can help you see your budget visually. You can use charts and free budget templates to show how much money you’re earning and spending in each category. It makes it easier to understand where your money is going and where you might want to make changes.

                                      Visual representations help you understand your day-to-day finances and empower you to manage your money. You can personalise your budget with colours and styles, and even make a joint budget with your partner.

                                      6. Set savings goals

                                      Excel can also help you track your savings goals. Create a section in the “Budget” sheet where you can write down how much money you want to save. Use a formula to calculate how much you need to save each month.

                                      For example, if you want to save $10,000 in a year then the formula you would type into your cell is ‘=10000/12’ which would mean you would have to save $833.33 per month. This will help you stay motivated and monitor your progress over time.

                                      7. Update and review

                                      Remember to update your budget regularly. Whenever you spend money, write it down in the “Budget” sheet. This way, you’ll always have an accurate picture of your finances. Review your budget regularly to see if you’re sticking to it and if there are any areas where you can save more money.

                                      Once you’ve been implementing your budget for a while, take some time to analyse how well you’re sticking to it. Look for any areas where you may be spending more than you planned or areas where you have extra money left over.

                                      This analysis will help you make adjustments to your budget, reallocating funds to align with your evolving priorities and financial goals.

                                      Key Tips to Help You Save

                                      Continuously explore opportunities to save money within your budget. Look for ways to reduce expenses, such as finding cheaper alternatives for certain products or services, comparing prices before making purchases, or cutting back on non-essential items. The more you can save, the more you’ll have to put towards your savings or other important financial goals.

                                      Managing your expenses easier with Red Tree Finance

                                      By organising your income, expenses, and savings, you’ll have a better understanding of your finances. Planning budgets help to outline financial goals for your future, so that you have enough when Christmas comes around, or any other financial goals you have throughout the year.

                                      At Red Tree Finance, we offer cash loans up to $5000 so you don’t have to stress about financials. You can receive an instant loan online with the money in your account on the same day. If you have any questions or need assistance, please don’t hesitate to contact us online.

                                      Frequently Asked Questions

                                      View all FAQs View all FAQs

                                      To create a simple budget in Excel, write down your monthly income and expenses in separate columns. Once you have these two figures, take them away from each other which will show you how much money you have left each month. Take this opportunity to see if there is any way to cut back on expenses.

                                      The formula is “=SUM(total funds/total expenses)’. This will help you find how much money you are earning compared to what you are spending and help you find a balance.

                                      The 50/30/20 budget rule in Excel is a budgeting strategy to help you understand your spending. 50% of your income goes to “needs”, 30% of your income goes to “wants” and 20% of your income goes to savings.

                                      People Also Read

                                      The information provided in this blog is of a general nature and is provided without considering your specific objectives, financial situation, or needs. It is intended for informational purposes only and should not be relied upon as financial, investment, or other professional advice.

                                      Before making any financial decisions or taking action based on the information presented, you are strongly encouraged to assess its appropriateness in light of your individual circumstances. Red Tree Finance does not intend to provide personalised financial advice, and you should seek independent financial, legal, tax, and other relevant advice tailored to your unique situation.
                                      image
                                      img
                                      image
                                      img
                                      Apply now

                                      Ready to apply for a loan?

                                      Apply to borrow up to $5,000 fast. Complete your online application in under 5 minutes.

                                      image
                                      image
                                      image

                                      How to Organise Bills: 8 Smart Ways to Pay Bills on Time

                                      Struggling with bills creates more than financial strain. Missed payments can lead to late fees, which can negatively impact your credit history and increase financial and personal stress. With living costs continually rising and most bills now paid digitally, having a clear system to manage payments is essential.

                                      Budgeting 19 June 2023

                                      In this article:

                                        Calculate your loan repayments

                                        How much would you like to borrow?

                                        Simply. Transparent. Tailored to you.

                                        Loan amount:
                                        $
                                        $2,350 $5,000
                                        Repayment frequency:
                                        Weekly repayment:

                                        (Over 12 month loan term)

                                        $0.00
                                        • Loan term 12 months
                                        • Interest & Fees $1,072
                                        • Total to pay $3,172
                                        arrow
                                          image

                                          Struggling with bills creates more than financial strain. Missed payments can lead to late fees, which can negatively impact your credit history and increase financial and personal stress. With living costs continually rising and most bills now paid digitally, having a clear system to manage payments is essential.

                                          Why Keeping Bills Organised Matters

                                          Keeping bills organised is not just about paying for things when the time comes around. It is an essential part of financial well-being. When bills are left unmanaged, small problems like late fees and penalties quickly grow into bigger issues that drain your budget.

                                          Consistently paying bills on time is one of the easiest ways to protect your credit history because lenders pay close attention to your repayment record, and missed bills can limit your ability to borrow in the future. A clear payment routine demonstrates financial stability and discipline.

                                          Being organised with your bills has other benefits. It makes budgeting easier, gives you confidence to plan for savings and discretionary spending, and provides accurate records at tax time. When you’re on top of your bills, you reduce anxiety and stress around money and gain peace of mind that everything is under control.

                                          Types of Bills to Keep Organised

                                          Every household faces a mix of predictable and less obvious bills. Beyond major costs like rent and utilities, small recurring charges such as subscriptions are easy to overlook. Keeping a complete list ensures nothing slips through the cracks.

                                          Typical bills include:

                                          • Rent or mortgage
                                          • Electricity, gas, waterInternet and mobileHome, car and health insurance
                                          • Car registration
                                          • Council rates
                                          • Childcare or school fees
                                          • Subscription services

                                          Keeping track of them all in one place gives you an accurate snapshot of your expenses.

                                          Not all bills are predictable either. Seasonal variations, such as higher energy use in summer, can push costs up, and emergencies like vet bills can appear suddenly. Review your past bills to highlight patterns and try to create an emergency buffer so that unexpected costs do not disrupt your system.

                                          How to Organise Bills: 8 Smart Ways to Pay Them on Time

                                          A smiling couple look over their finances on a laptop

                                          It can be daunting to look at your past bills and try to untangle them. But the hardest part is getting started, so here are 8 tips to help you organise your bills and make managing them a breeze.

                                          1. Create a Monthly Budget

                                          A budget is the foundation for organising your bills. By mapping your income and expenses, you see exactly how much of your money is already committed each month. This allows you to plan and prevents nasty surprises.

                                          Start by reviewing your bank statements and listing every regular expense. Add these up and compare the total with your income. Then decide on a savings goal and set a realistic spending limit for discretionary items.

                                          Simple rules, such as the 50-30-20 approach, make it easier to stick to a plan. The clearer your budget, the easier it becomes to pay bills on time.

                                          2. Use a Bill Checklist

                                          A checklist gives you visibility and control. By recording each bill with its name, due date and amount, you create a simple reference that makes it easier to plan for payments.

                                          Your checklist can take many forms. Some people prefer a digital spreadsheet they can access anywhere, while others use a notebook or a whiteboard in the kitchen. It’s about what method is right for you. The format matters less than the consistency.

                                          Ticking off bills as they are paid creates a clear record and reduces the mental pressure of wondering what has or hasn’t been paid.

                                          3. Track Your Receipts

                                          Receipts may seem minor, but they create an important record of your spending. Small cash purchases and incidental costs add up over time, and without a record, they are easy to forget.

                                          You can manage receipts in several ways. Physical folders work for paper copies, while scanning and storing them digitally allows for easier searching. Reviewing your receipts alongside your banking app ensures that nothing is missed.

                                          Building this habit gives you two advantages: you stay on top of your bills, and you start to see patterns in your spending. This awareness can help you adjust habits and make better financial decisions.

                                          4. Set up Calendar Reminders

                                          A calendar is one of the simplest tools to keep bills on track. Setting reminders for upcoming due dates ensures you are always prepared.

                                          The key is to set alerts a few days before the bill is actually due. This gives you time to move money if needed and avoids last-minute pressure.

                                          Recurring reminders are particularly useful for fixed bills like insurance or rent. With a few minutes of setup, you can remove the risk of forgetting altogether.

                                          5. Set up Automatic Payments

                                          Automatic payments remove the risk of forgetting a bill altogether. Once set up, your bank or provider deducts the payment each month without further action from you.

                                          This method works best for essential bills like rent, utilities and insurance with, many providers even offering small discounts for setting up direct debit. The only requirement is to ensure your account balance covers the deduction to avoid dishonour fees.

                                          If you prefer manual control, you can still use scheduled transfers through your online banking. Choose a regular date each month, pay your bills and record the transaction. Both approaches reduce stress and keep your payments consistent.

                                          6. Implement Budgeting Tools

                                          Budgeting tools make organisation easier by doing much of the tracking for you. Instead of managing everything manually, apps can centralise information, send reminders and provide insights into your spending.

                                          In Australia, popular options include BPAY View, which lets you manage bills within your banking app, Money management apps like Frollo, which help track overall finances, and GetReminded, which alerts you before renewals and helps compare alternatives. Most banks also offer in-app budgeting tools to keep you on track.

                                          Choose the tool that suits your lifestyle. The best app is the one you will actually use consistently.

                                          7. Use a Digital Filing System

                                          Filing bills digitally means no more paper. Scanning and storing bills electronically allows you to create labelled folders by category and access them from any device. Automatic backups and cloud software ensure everything is recorded.

                                          This approach makes tax preparation simple and helps you find documents quickly. Keep your active bills in a separate folder from archived ones so you can focus on what still needs to be paid.

                                          By moving to digital storage, you reduce clutter and create a reliable record you can use at any time.

                                          8. Consolidate Bills with a Loan

                                          Managing multiple due dates each month is stressful, so a more straightforward way to manage the chaos is to roll your bills into one loan. This way, you can roll a number of payments into a single predictable amount.

                                          A loan for bills is similar to a debt consolidation loan. It reduces the number of due dates you must track, helps you avoid late fees and protects your credit record.

                                          Red Tree Finance offers loans designed to make this process easier. With one repayment schedule, you can reduce stress and focus on the bigger picture.

                                          Stay on top of your bills with Red Tree Finance

                                          Bills do not have to control your life. With a clear system, you can stay ahead of due dates and protect your financial well-being.

                                          If overdue bills are already causing pressure, Red Tree Finance can help. A loan to cover bills combines multiple payments into one manageable repayment, reducing stress and helping you avoid extra fees.

                                          You can apply online today or, if you prefer, talk with our customer service team about the best way forward for you.

                                          Frequently Asked Questions

                                          View all FAQs View all FAQs

                                          You can organise bills at home physically or digitally. A simple starting point is to separate paid and unpaid bills into labelled folders so nothing gets lost. Some households colour-code folders by category, such as utilities, insurance and subscriptions, to make them easy to find.

                                          For long-term convenience, scanning bills and storing them digitally is even more effective. Cloud storage lets you access records anywhere and keeps them safe from damage. Keeping current bills in a separate folder from archived ones ensures you focus only on what still needs attention.

                                          Whether physical or digital, the goal is the same: reduce clutter, know what is outstanding and create a reliable record for tax or budgeting.

                                          The 50-30-20 budget rule makes it easy to understand and manage your income with a simple framework, which in turn, helps you learn how to organise bills. It divides your take-home pay into three categories: 50 per cent for essential needs such as rent, bills and groceries, 30 per cent for discretionary spending like entertainment and dining, and 20 per cent for savings or debt repayments.

                                          For example, if you earn $4,000 a month after tax, $2,000 would go towards needs, $1,200 for wants, and $800 towards savings and debt reduction.

                                          This approach makes it easier to prioritise bills because you know the essentials are always covered first. From there, you can plan lifestyle spending and savings without the risk of falling behind.

                                          Bill smoothing is a payment arrangement offered by many Australian utility providers (e.g. electricity, gas). Instead of paying variable bills (higher in summer for air conditioning, lower in spring), your provider estimates your annual usage and divides it into equal monthly instalments.

                                          This helps households avoid bill spikes and makes cash flow more predictable. It’s directly relevant to the bill organisation because it removes one of the biggest budgeting challenges: seasonal shocks.

                                          People also read:

                                          The information provided in this blog is of a general nature and is provided without considering your specific objectives, financial situation, or needs. It is intended for informational purposes only and should not be relied upon as financial, investment, or other professional advice.

                                          Before making any financial decisions or taking action based on the information presented, you are strongly encouraged to assess its appropriateness in light of your individual circumstances. Red Tree Finance does not intend to provide personalised financial advice, and you should seek independent financial, legal, tax, and other relevant advice tailored to your unique situation.
                                          image
                                          img
                                          image
                                          img
                                          Apply now

                                          Ready to apply for a loan?

                                          Apply to borrow up to $5,000 fast. Complete your online application in under 5 minutes.

                                          image
                                          image
                                          Apply now Apply now