Borrow between $2,350 - $5,000 today.

Apply now Apply now

Tag: <span>Personal Loans</span>

image

What Wedding Costs Can A $5000 Loan Cover?

Planning a wedding is one of life’s most exciting occasions, from sampling different catering options to choosing suits and dresses and, of course, booking the venue for the big day. But it does add up quickly.

Budgeting 21 April 2026

In this article:

    Calculate your loan repayments

    How much would you like to borrow?

    Simply. Transparent. Tailored to you.

    Loan amount:
    $
    $2,350 $5,000
    Repayment frequency:
    Weekly repayment:

    (Over 12 month loan term)

    $0.00
    • Loan term 12 months
    • Interest & Fees $1,072
    • Total to pay $3,172
    arrow
      image

      Planning a wedding is one of life’s most exciting occasions, from sampling different catering options to choosing suits and dresses and, of course, booking the venue for the big day. But it doesn’t take much for wedding costs to add up quickly. A $5,000 wedding loan may not cover every last detail, but it can certainly provide some relief to key areas of your budget.

      Venue Hire And Styling

      Your venue sets the tone for the day, whether you decide on a traditional church ceremony or have your wedding at a winery or function centre. Here in Australia, though, even modest locations come with a notable price tag.

      Booking a small function room, garden, or community hall can set you back anywhere from $1,500 to $4,000, depending on your location and preferred day of the week for the ceremony. With a $5,000 loan, you could comfortably pay for your venue hire for an intimate gathering and still have funds left over to cover styling essentials like table centrepieces, fairy lights, signage, and chair covers.

      Many prospective newlyweds use this portion of their wedding budget to create a visually stunning space without overspending elsewhere. It goes to show that a thoughtful venue choice can make a big difference to your special day.

      Catering And Drinks

      The food and drink you serve at your wedding reception will likely be one of the biggest talking points among your guests, both when they’re seated at their tables and in the days after the event.

      With careful planning, you can make a $5,000 cash loan stretch surprisingly far on the catering side of things. Consider these budget-friendly approaches:

      • Opt for a canapé-style service rather than a formal sit-down meal. Not only can this potentially lower your per-head costs in a big way, but it also keeps the atmosphere relaxed and social.
      • Shared grazing tables are growing in popularity in Australia. Depending on the spread that you offer and the number of guests that attend, this can feed a crowd for $800–$1,500.
      • Some BYO venues let you bring your own alcohol, allowing you to possibly save hundreds of dollars on inflated venue mark-ups.
      • Food trucks or pop-up caterers offer flexible, transparent pricing that suits smaller guest lists and outdoor settings beautifully.

      Photography And Videography

      Long after the ceremony has ended, and you’ve packed up the reception venue and headed on your honeymoon, your wedding photos and video will provide the lasting record of one of the most important days of your life. Therefore, it’s worth investing wisely in the photographer and videographer who will capture those moments.

      In Australia, a professional photographer typically charges between $3,000 and $5,500 for coverage that spans pre-ceremony to reception. If you choose to hire a videographer as well, that can add a further $2,500 to $4,000 to your costs. With a $5,000 loan, you could realistically cover photography alone, or split the sum between a mid-range photographer and a shorter videography package.

      Booking your photographer and videographer well in advance doesn’t just secure the team you want; it also gives you time to sort your finances without stress. If timing is a concern, a fast loan can provide the funds you need to secure your dream photographer or videographer.

      Wedding Attire And Beauty

      One wedding day detail guaranteed to get guests and the bridal party talking is the bride’s dress and the groom’s suit. Looking and feeling your best on your wedding day matters enormously, and the costs of attire and beauty add up faster than many couples expect.

      Here’s what a $5,000 personal loan could realistically cover across a small bridal party:

      • Wedding dress or suit hire/purchase: $800–$3,000, depending on the designer and whether you buy or hire.
      • Bridesmaid dresses and groomswear: $500–$1,200 for a party of three or four.
      • Hair and makeup for the bridal party: $400–$900 for a professional artist covering four people.
      • Shoes, jewellery, accessories, and alterations: $200–$500, depending on choices.

      Entertainment And Music

      When it comes to the wedding reception, your choice of entertainment will shape the energy and atmosphere of the event. For many couples, that choice often comes down to a live band or a DJ.

      To hire a live band, you can expect to pay anywhere from $2,000 to $5,000, depending on the number of musicians and the length of their set. On the other hand, a professional DJ typically runs between $800 and $2,000.

      But these are not your only two options. If your budget is tighter and you’d rather use the funds from a same-day loan elsewhere on your wedding, don’t underestimate the value of a carefully curated playlist. Play it through a quality sound system, and the hire costs can often remain well under $500. You might also want to set aside funds for a photo booth, lawn games, or a wishing well.

      Flowers, Decorations, And The Finishing Touches

      Floral arrangements and décor really bring a wedding ceremony to life. If you plan well in advance, you can often order seasonal blooms from a local florist at a surprisingly affordable rate.

      A full floral package, one that covers the bridal bouquet, buttonholes, ceremony arch, and reception centrepieces, can start from $1,500 and go above and beyond the $3,500 price point. With $5,000 available from an instant loan, you have real room to move, especially if you mix professional floristry with DIY elements like pillar candles, lanterns, or eucalyptus garlands. Dried florals are also a growing trend – they last longer and often cost considerably less.

      Borrow Smart And Celebrate Well

      With wedding expenses now coming in at an average total of $36000, many couples often explore all avenues to close the divide between the reality of their bank balance and their dream wedding experience.

      Though a $5,000 loan won’t cover all your wedding costs, it can meaningfully fund one or more key areas – whether that’s your venue, photography, attire, or catering. The important thing is to be clear about your priorities before you borrow, so the funds go exactly where they’ll make the biggest difference to your special day.

      Red Tree Finance offers secured loans that can help you partially cover wedding costs. When you’re ready to move forward, take a few minutes to check your eligibility before applying. It’s a straightforward step that helps you understand what’s available and plan your wedding finances with confidence.

      Frequently Asked Questions

      View all FAQs View all FAQs

      You can certainly have a romantic wedding that is memorable in all the right ways on a $5000 budget, but the likelihood is that planning the event will require a lot of DIY effort and some creative thinking. You will also likely need to keep numbers relatively small so as not to go over your budget.

      A 2024 survey by the Australian Government website MoneySmart revealed that the average Australian wedding cost $36000. Of the couples surveyed, 82% funded their wedding with their savings, and 60% took out a loan to cover full or partial costs.

      The 30-5 rule states that you should account for time variables and “things not going 100% to plan” occurrences by allocating 30 minutes to tasks or events that you would expect to take 5 minutes of your time. This could be anything from gathering the bridal party for photos to pinning your buttonhole. When you have wedding photographers and vendors who might charge by the hour, accounting for this time matters.

      The information provided in this blog is of a general nature and is provided without considering your specific objectives, financial situation, or needs. It is intended for informational purposes only and should not be relied upon as financial, investment, or other professional advice. Before making any financial decisions or taking action based on the information presented, you are strongly encouraged to assess its appropriateness in light of your individual circumstances. Red Tree Finance does not intend to provide personalised financial advice, and you should seek independent financial, legal, tax, and other relevant advice tailored to your unique situation.
      image
      img
      image
      img
      Apply now

      Ready to apply for a loan?

      Apply to borrow up to $5,000 fast. Complete your online application in under 5 minutes.

      image
      image
      image

      What Is A Credit Card Balance Transfer?

      With living costs on the rise in Australia, high-interest credit card debt can feel like a treadmill that never stops. Whether you're struggling to keep up with everyday bills and expenses or carrying a balance that just won't shrink, a “balance transfer” might sound like the best way to get off that treadmill. While this

      Debt Consolidation 15 April 2026

      In this article:

        Calculate your loan repayments

        How much would you like to borrow?

        Simply. Transparent. Tailored to you.

        Loan amount:
        $
        $2,350 $5,000
        Repayment frequency:
        Weekly repayment:

        (Over 12 month loan term)

        $0.00
        • Loan term 12 months
        • Interest & Fees $1,072
        • Total to pay $3,172
        arrow
          image

          With living costs on the rise in Australia, high-interest credit card debt can feel like a treadmill that never stops. Whether you’re struggling to keep up with everyday bills and expenses or carrying a balance that just won’t shrink, a “balance transfer” might sound like the best way to get off that treadmill. While this option may provide some financial breathing space and offer an effective solution, balance transfers aren’t always the “get out of jail free” card they appear to be.

          How Does A Balance Transfer Really Work?

          Before signing a new credit agreement, it’s important to think about the short-term benefits and the long-term risks, and consider each carefully.

          The Advantages

          • Temporary relief from high interest: Transferring your balance from a high-rate to a low-rate (or no-interest) card can help you reduce your principal quicker.
          • Simpler debt management: Transferring multiple credit card balances into one single card can make your finances easier to manage, as you only have one repayment to keep track of instead of several.

          The Drawbacks

          • The revert rate can be expensive: If you don’t repay the transferred balance in full before the end of the promotional period, the remaining amount often attracts a significantly higher interest rate. For some people, depending on the balance, this can be like walking one step forward and two steps back. This can lead to a situation that leaves you considering an emergency loan to cover an unexpected shortfall.
          • Fees can reduce the benefit: Many balance transfer offers come with an upfront transfer fee, which lenders add to your balance from day one. This means the offer may not be as cost-effective as it first appears.
          • It can encourage ongoing credit card use: For some borrowers, moving the balance creates a false sense of progress. Keeping old cards open or making new purchases on the balance transfer card makes it easy to fall back into old habits and maintain the same debt cycle.

          Why A Balance Transfer Isn’t Always The Best Solution

          While some credit card holders can make balance transfers work to their advantage, they’re not always suitable for everyone and require a lot of self-control to manage.

          Moving the debt from one card to another and believing you’ve solved the problem doesn’t always work out that way. It’s why many people fall into the trap of keeping their old cards open and continuing their spending.

          In many cases, banks don’t always allow a full transfer of the balance of your new card; you might only be able to move 70% or 80% of the approved amount. This leaves you with a “hangover” of debt on your old high-interest card, which defeats the point of consolidation.

          Many providers can also cancel your 0% offer right away if you miss just one payment, putting you back where you started. When you’re already under financial pressure, waiting weeks for a solution isn’t an option. This is why many Australians look into same-day loan options that can stop the interest clock sooner.

          Structured Personal Loans: The Alternative

          For many Australians seeking ways to reduce their debt, maintaining a revolving door of credit cards (even with low to no interest) risks keeping the debt problem alive. This is where cash loans for debt consolidation can provide a better, more organised way to get your balance down.

          Unlike a credit card that stays open until you decide to cancel it, a secured loan has a set end date, which allows you to clearly see the end of the tunnel. This may make your life easier by paying off all of your cards at once with a cash loan. There is no guesswork or “revert rates”; just a simple plan to pay off your debts.

          Key Things To Consider When Making A Consolidation Plan

          Before signing up for an online loan, or any new financial product, you should look beyond the “low rate” headlines and see how the debt structure aligns with your current financial circumstances.

          To make sure your plan for a fresh start works, think about the following things:

          • Repayment scheduling: Can you schedule your repayments directly with your payday – whether it’s weekly, fortnightly or monthly – so you don’t run out of money?
          • Speed of approval: Every day counts when your current interest rates are sky high. The quicker the decision on your application, the quicker you can stop the interest from bleeding on your old cards.
          • A clear finish line: With a fixed-term loan, you know you’ll pay the debt off by a certain end date. With credit cards, you can choose to only make the minimum payments, which keeps the debt cycle ongoing.
          • Cost transparency: Has the lender clearly outlined the total costs and interest rates up front, or are there hidden “revert rates” and annual fees that you can’t see?
          • Human assessment: Will you only have an algorithm judging your application, or will the lender also look at your current job and how well you can handle payments today?

          How To Decide Which Option Suits Your Situation

          Choosing between a balance transfer and a consolidation loan as the best option to manage your debts will depend on your spending habits.

          A balance transfer might work for someone who has only a small amount of debt and is very disciplined about not using their card to buy coffee or petrol. But if you really want to stop using “plastic” for good, a personal loan may suit you better and allow you to combine all of your debts into one fixed payment. This will enable you to start over and see your balance finally reach zero by a certain date.

          Take Charge Of Your Financial Future

          While a credit card balance transfer can be helpful for some people, it’s often just a band-aid solution to a bigger problem for others.

          Moving debt from one card to another doesn’t erase the issue. It might reduce the problem, but it can also just “relocate” the problem. To really manage your debts and reclaim control of your finances, a structured plan with a clear start and end date goes a long way.

          At Red Tree Finance, we understand that getting on top of debt is rarely about those quick fixes. More often, it comes down to choosing an option that is realistic, manageable and easier to stick with over time. For some borrowers, that may mean looking beyond credit cards altogether and exploring fast loans online that offer clear repayment terms and an even clearer endpoint.

          Frequently Asked Questions

          View all FAQs View all FAQs

          A balance transfer credit card allows you to move the balance you owe from a card with a high interest rate to one that comes with a lower rate of interest (or 0% interest) for a determined period of time. This enables you, as the cardholder, to repay the principal you owe more quickly than you would on a high-interest-rate card. While balance transfer cards allow you to simplify your debt repayments at a lower interest rate, they do often incur a one-time fee to facilitate the transfer.

          Credit card balance transfers can be an effective debt management strategy for some people, but they won’t necessarily work for everyone. If you’re disciplined enough to treat your balance transfer card simply as a way to reduce your debt, it may provide the benefits you need. But if you continue to use the card for spending, you risk adding to your debt and defeating the original purpose of transferring the balance.

          Common drawbacks that come with a credit card balance transfer can include:

          • The upfront transfer fee (which can be up to 5% of the total balance)
          • The significantly higher interest rate that your credit card reverts to if you don’t pay off the balance in full during the promotional period.
          • The possible drop in your credit score. Though it’s often temporary, any new credit application can negatively impact your rating.

          The information provided in this blog is of a general nature and is provided without considering your specific objectives, financial situation, or needs. It is intended for informational purposes only and should not be relied upon as financial, investment, or other professional advice.Before making any financial decisions or taking action based on the information presented, you are strongly encouraged to assess its appropriateness in light of your individual circumstances. Red Tree Finance does not intend to provide personalised financial advice, and you should seek independent financial, legal, tax, and other relevant advice tailored to your unique situation.
          image
          img
          image
          img
          Apply now

          Ready to apply for a loan?

          Apply to borrow up to $5,000 fast. Complete your online application in under 5 minutes.

          image
          image
          image

          How To Set Up A Home Office Or Study

          For many Australians going to work or studying in a post-COVID world, the “new normal” saw the dining room table become the boardroom or the classroom. Sure, working from home offers great flexibility and convenience. However, leaning over a laptop on a kitchen stool isn't a good way to set yourself up for long-term success.

          Guide 24 February 2026

          In this article:

            Calculate your loan repayments

            How much would you like to borrow?

            Simply. Transparent. Tailored to you.

            Loan amount:
            $
            $2,350 $5,000
            Repayment frequency:
            Weekly repayment:

            (Over 12 month loan term)

            $0.00
            • Loan term 12 months
            • Interest & Fees $1,072
            • Total to pay $3,172
            arrow
              image

              For many Australians going to work or studying in a post-COVID world, the “new normal” saw the dining room table become the boardroom or the classroom. Sure, working from home offers great flexibility and convenience. However, leaning over a laptop on a kitchen stool isn’t a good way to set yourself up for long-term success.

              Making A Plan For Your Space And Setting A Budget

              Before you start shopping around for secured loans to buy the latest ergonomic office chair and desk, planning is essential – first the floorplan, then your finances. Being honest about your budget and measuring the space you have will help you avoid costly mistakes in the future.

              • Measure twice, buy once: Draw a map of your nook or room. You won’t buy a desk that blocks the door if you know the exact size you need.
              • Prioritise your spending: Pick the items that will make you most productive first, while also maintaining your comfort. If you type for eight hours a day, a good chair should be at the top of your list.
              • Financial flexibility: If you need to set up a dedicated work or study space but don’t have the money right now, looking into online loans can help you access the funds you need right away.

              Planning your finances ahead of time will help you make a space that works for you without adding extra stress.

              Picking A Style That Works For You

              If you’re likely to be spending a great deal of time in your office or study, it should be a place that you want to spend time in. Design isn’t just about how things look; it’s also about how they make you feel and how well they work.

              • The value of colour: Don’t underestimate how the right colour scheme can bring value to your productivity. Blue tones make you feel calm, while yellow pops make you more creative.
              • The power of green: An inexpensive Pothos or Snake Plant from the local nursery is worth more than you think. They clean the air and make the room feel alive.
              • Personal touches: Use photos, art or motivational posters that make you feel good and inspire you to GET THINGS DONE.

              Choosing the right look makes your workplace look professional and keeps you motivated all week long. A cash loan from Red Tree Finance can provide the funds you need to fit out your new home office or study.

              Finding Cheap Office Furniture

              Once you’ve got your budget sorted, it’s time to start shopping for your furniture.

              Thankfully, you won’t need to spend a lot of money to get a good setup. Across Australia and online, you’ll find a multitude of budget-friendly stores and busy second-hand markets to choose from.

              The Desk: Your Base of Operations

              If you live in a small apartment, look for “ladder desks” or small workstations. Stores like IKEA, Officeworks, and Kmart offer a range of stylishly designed desks that won’t blow your budget. Of course, if you find the perfect high-end item second-hand and need to act quickly, you can get a fast loan online and take advantage of those local deals before someone else does.

              The Chair: Don’t Cut Corners on Ergonomics

              Choosing the right ergonomic chair is vital. Your back will certainly thank you later.

              Whichever models you look at, make sure you can change their height and lumbar support. Look on Facebook Marketplace or Gumtree for high-end brands like Herman Miller or Steelcase. Offices that are getting rid of old stock often sell them much cheaper than the standard retail price.

              Buying good furniture early on prevents long-term damage to your body and makes you more productive in the long run.

              Tips for Better Lighting and Productivity

              Bad lighting makes your eyes tired and strained, especially when you’re working away for hours on end. To maintain focus and keep your energy up all day, work on these cheap changes:

              • Optimise your use of natural light: To get more Vitamin D and less glare on your screen, put your desk next to a window.
              • Layered lighting: A basic LED desk lamp is great for getting work done at night.
              • Cable management: Use cheap cable sleeves from a discount store or binder clips to stop your “cord spaghetti” from getting out of control.

              Keeping your workspace clean and well-lit helps you stay focused on the important tasks and cuts down on distractions. If you want to maximise your use of natural light in your home, a personal loan of up to $5000 can provide the funds to add a skylight to the room or consider other improvements.

              Save Money By Upcycling Or Going DIY

              The least expensive furniture is the furniture that you already own, and this is where upcycling comes into play as an avenue worth considering. Not only is upcycling good for your wallet, but it’s also good for the environment.

              When it comes to how to set up an office or study, there are many upcycling options you can play with. And all will infuse your productive workspace with character and personality that truly makes the space your own.

              For example, if you want to achieve a unique “industrial” look, take an old dining table, sand it down, and paint or stain it. You can get creative with how you store your office supplies by using old wooden crates as floating shelves or mason jars to hold your pens, pencils and other stationery.

              If you want to turn a spare room into a permanent studio, knowing how to apply for a loan gives you access to funds upfront for tools, materials and setup costs. It may also help you manage costs by giving you a clear, finite budget to work with – keeping spending focused and preventing unexpected overruns.

              Are You Ready To Change How You Work From Home?

              The Australian Bureau of Statistics released a report in August of 2025 showing that 36% of employed people usually worked from home. Whether you’re looking to switch to a WFH agreement or you’re creating a dedicated space to study, knowing how to set up a home office or study that looks good and works well need not cost you a lot of money.

              By combining smart shopping with fun DIY projects and the financial assistance of an instant loan from Red Tree Finance, you can create a workspace that looks as good as any corporate headquarters or well-equipped classroom.

              To set up a home office or study, make sure you have a dedicated room in the house. Minimise distractions and maximise natural light. For comfort and health benefits, make sure your furniture is ergonomically sound. Spend a weekend getting your workspace ready; a weekend loan from Red Tree Finance can give you the funds to get up and running.

              To set up a functional home office that fosters productivity and performance, you’ll need furniture (i.e. a desk and chair). A desk lamp can provide additional lighting for night working, while cable management clips and accessories will keep your cords tidy and safe. To keep your workspace tidy, consider organisers for your paper and media, as well as hooks for the wall.

              How much you spend on your home office or study will depend on how you choose to fit out your workspace. You may want to keep your design very minimalistic or fit out your space with second-hand furniture. You might opt for brand new ergonomic furniture and install a skylight, all of which will increase your overall spend. Red Tree Finance offers loans starting from $2350 up to $5,000, giving you the funds you need, no matter how detailed your plans get.

              The information provided in this blog is of a general nature and is provided without considering your specific objectives, financial situation, or needs. It is intended for informational purposes only and should not be relied upon as financial, investment, or other professional advice.Before making any financial decisions or taking action based on the information presented, you are strongly encouraged to assess its appropriateness in light of your individual circumstances. Red Tree Finance does not intend to provide personalised financial advice, and you should seek independent financial, legal, tax, and other relevant advice tailored to your unique situation.
              image
              img
              image
              img
              Apply now

              Ready to apply for a loan?

              Apply to borrow up to $5,000 fast. Complete your online application in under 5 minutes.

              image
              image
              image

              Can I Pause Loan Repayments?

              Life doesn’t always move in a straight line. Obstacles can wreak havoc on your short and long-term plans and throw your financial circumstances into disarray. From unexpected medical emergencies to loss of employment or natural disaster events, it’s situations like these that can make you reassess your immediate financial priorities. If you have a personal

              Budgeting 10 February 2026

              In this article:

                Calculate your loan repayments

                How much would you like to borrow?

                Simply. Transparent. Tailored to you.

                Loan amount:
                $
                $2,350 $5,000
                Repayment frequency:
                Weekly repayment:

                (Over 12 month loan term)

                $0.00
                • Loan term 12 months
                • Interest & Fees $1,072
                • Total to pay $3,172
                arrow
                  image

                  Life doesn’t always move in a straight line. Obstacles can wreak havoc on your short and long-term plans and throw your financial circumstances into disarray. From unexpected medical emergencies to loss of employment or natural disaster events, it’s situations like these that can make you reassess your immediate financial priorities. If you have a personal loan, questions like “Can I pause my loan repayments?” become important to help you navigate potential financial hardship issues.

                  How Different Types Of Personal Loans Work

                  Many people believe that personal loans come with the same “repayment holidays” typically advertised with 30-year mortgages, but that isn’t necessarily the case. For example, Red Tree Finance personal loans are capped at $5000 and come with shorter repayment terms. They’re primarily used to fund smaller purchases or services like car repairs, paying medical bills, or debt consolidation. This makes the structure for repayment relief more specific.

                  Repayment Variations As A Relief Option

                  A full “pause” of your repayments, with no accumulated interest, is rare in the personal loan industry. A more common option is a “repayment variation”, where the lender and borrower agree to a change in the terms of your loan contract. This way, your loan doesn’t become too burdensome while you deal with a crisis, and still allows you to chip away at loan repayments.

                  Defining Financial Hardship

                  You’ve likely heard the term “financial hardship” in conversation or in the media and understood its general meaning. Within the Australian credit landscape, however, it has a specific definition.

                  Financial hardship describes a situation where a borrower intends to make their loan repayments but lacks the immediate financial capacity to do so. It is not a permanent inability to pay, but rather a temporary hurdle caused by a change in circumstances.

                  Typical Financial Hardship Scenarios

                  Common situations in which you’ll potentially qualify for hardship assistance include:

                  • Changes in employment status: If you become redundant, experience a significant downturn in available overtime, or your employer moves you from full-time to casual hours.
                  • Health issues: A sudden illness or injury that leads to high medical out-of-pocket costs or puts you out of action and leaves you unable to earn an income.
                  • Changes to family situations: Relationship breakdowns or the loss of a family member can put a strain on household finances.
                  • Surges in daily living costs: Major cost-of-living expenses that compromise your ability to meet your loan repayment agreement.
                  • Natural disasters and other emergencies: Flood, earthquake or bushfire events can be financially damaging and affect your ability to repay your loan as you recover.

                  If you experience any of these situations, you may be able to apply for financial hardship assistance.

                  The Application Process For Assistance

                  If you find yourself in a position where you’re unable to meet your next scheduled loan repayment, early and proactive communication is the best way to maintain your credit score and keep default notices at bay.

                  You will need to demonstrate a clear picture of your current financial standing if you wish to apply for hardship assistance. Red Tree Finance has streamlined this process to be as stress-free as possible. The three steps are as follows:

                  1. Documentation: Collect evidence of your change in circumstances. Common examples include a medical certificate, a letter from your employer notifying you of your redundancy, or bank statements that show a noticeable drop in income.
                  2. Financial summary: Put together a basic summary of your current monthly income versus your essential shared household expenses (rent/mortgage, food, utilities).
                  3. Submission: You can access our dedicated Financial Hardship application form or email our care team directly at hardship@redtreefinance.com.au.

                  Once Red Tree Finance receives your application and documentation, our people review your information with sensitivity to determine a sustainable path forward. Possible options might include a temporary reduction in payment amounts or an extension of the loan term to reduce the weekly or fortnightly cost.

                  How Repayment Variations Might Affect You In The Long Term

                  Though repayment variations can provide short-term relief in times when you’re experiencing financial hardship, it’s important to also consider their possible long-term effects – especially when it comes to the overall cost of your loan.

                  For example, if you were to apply for financial hardship assistance and were offered an extension to your original loan term, it could certainly reduce your weekly payments. However, you may end up paying more in interest over the life of the loan.

                  With any repayment variation, Red Tree Finance aims to ensure it aligns with our Target Market Determination. This means that the proposed solution must be fit for your needs and will not create further long-term financial harm.

                  Rather than a quick “band-aid fix”, we aim to provide a “sustainable fix” that allows you to gradually return to your original repayment schedule without building up a mountain of debt.

                  Your Rights Under Australian Law

                  Transparency and fairness are protected under the National Consumer Credit Protection Act. As a borrower, you have specific rights when you request financial relief:

                  • Right to a quick response: Red Tree Finance always aims to resolve all hardship assistance-related disputes within 21 days.
                  • Right to an internal review: If you do not like a decision about your hardship assistance application, you can formally ask for an internal review of the case.
                  • External dispute resolution: If we can’t come to an agreement, you are welcome to contact the Australian Financial Complaints Authority (AFCA). AFCA is an independent body that offers free dispute resolution services to consumers, ensuring that lenders act fairly and reasonably.

                  At Red Tree Finance, we understand how important it is to work with you to find a fair and sustainable path forward.

                  It’s Time To Take The First Step

                  Dealing with money troubles can be exhausting, especially when they come without warning. But when you have a cash loan with Red Tree Finance, you don’t need to manage these troubles alone.

                  Though you cannot stop your payments outright, we provide structured, legal avenues to help you manage your personal loan when times are tough.

                  The best way to protect your credit health and gain peace of mind is by being proactive as soon as you start to feel the pinch. If you are struggling, please visit our Financial Hardship page or contact us online.

                  Getting on the front foot today is the most effective way to secure your financial future.

                  Frequently Asked Questions

                  View all FAQs View all FAQs

                  If you’re experiencing financial hardship due to events like a loss of employment, a natural disaster or changes to your family situation, you can request hardship assistance in the form of a repayment variation. Most commonly, these variations often come as an extension to the term of your loan or a reduction in your regular repayment amount.

                  According to the National Debt Helpline, a default on your loan (which is when you have missed repayments) will be listed on your credit report. However, if you have organised a repayment arrangement with the lender due to financial hardship, they cannot list a default on your report. Therefore, it will not affect your credit score.

                  Hardship assistance is a short-term solution to get you through an immediate financial obstacle. It’s not intended to be a permanent change to your contract. Ultimately, the duration depends on your specific situation, such as how long you expect to be out of work or recovering from an illness. Once the agreed-upon period ends, you will typically return to your regular repayment schedule.

                  The information provided in this blog is of a general nature and is provided without considering your specific objectives, financial situation, or needs. It is intended for informational purposes only and should not be relied upon as financial, investment, or other professional advice.Before making any financial decisions or taking action based on the information presented, you are strongly encouraged to assess its appropriateness in light of your individual circumstances. Red Tree Finance does not intend to provide personalised financial advice, and you should seek independent financial, legal, tax, and other relevant advice tailored to your unique situation.

                  image
                  img
                  image
                  img
                  Apply now

                  Ready to apply for a loan?

                  Apply to borrow up to $5,000 fast. Complete your online application in under 5 minutes.

                  image
                  image
                  image

                  5 Low Cost Hobbies To Take Up In 2026

                  As Aussies continue to navigate the growing costs of living, many of us are looking for ways to have fun in the new year without spending too much money. That's why more and more people are pursuing affordable hobbies and interests in 2026.

                  Guide 23 January 2026

                  In this article:

                    Calculate your loan repayments

                    How much would you like to borrow?

                    Simply. Transparent. Tailored to you.

                    Loan amount:
                    $
                    $2,350 $5,000
                    Repayment frequency:
                    Weekly repayment:

                    (Over 12 month loan term)

                    $0.00
                    • Loan term 12 months
                    • Interest & Fees $1,072
                    • Total to pay $3,172
                    arrow
                      image

                      As Aussies continue to navigate the growing costs of living, many of us are looking for ways to have fun in the new year without spending too much money. That’s why more and more people are pursuing affordable hobbies and interests in 2026.

                      1. DIY Crafts And Upcycling

                      These are two classic low-cost hobbies that let you make something useful and potentially valuable out of scraps and discarded items you already have.

                      DIY crafts and upcycling encourage creativity over consumption, whether it’s by repainting old furniture, making gifts by hand, or finding new uses for items around the house. Many people like the feeling of accomplishment that comes with finishing small projects, especially when they can follow free online tutorials.

                      What Is Upcycling?

                      We’re all very aware of recycling as a way of reducing waste, but how does it differ from upcycling?

                      Simply put, upcycling is the process of transforming old or discarded materials or items into something new that is of greater value or quality. It differs from recycling by not breaking down materials to produce something new, like recycled paper or plastics. Instead, you’re simply “upgrading” the item in its current state through design or creative repurposing. For example, you might make a candle holder out of an empty jam jar rather than throwing it out in the recycling bin.

                      If you have to pay for small purchases up front and keep track of your household expenses, knowing how personal loans for everyday expenses work can help you plan with more confidence.

                      2. Exploring Local Hiking Trails On The Weekend

                      Australia has some wonderful walking trails and hiking spots across the country, from the Heysen Trail in South Australia (the country’s longest marked trail, spanning 1200 kilometres) to a variety of tracks in Victoria’s Wilsons Promontory. And thankfully, for most people, walking is one of the easiest low-cost hobbies you can take up in 2026.

                      Many of us see the new year as the perfect time to get fit and active, but don’t always want to commit to going to the gym to achieve that goal. Australia is rich with national parks, beaches and other hiking trails that mean you don’t have to shell out for memberships or expensive equipment to get the heart rate up.

                      Walking regularly is a hobby that can easily become a part of your routine if you try out new routes or invite friends to join you. If you’re travelling long distances to test out some new trails, be sure to service or repair your car in advance. The last thing you want is to find yourself stranded out in the middle of nowhere.

                      3. Reading And Exchanging Books

                      If you love to travel to new places but don’t have the time to take advantage of a holiday loan at the moment, reading is an easy and low-cost way to explore new worlds from the comfort of your home.

                      No matter how much money you have, you can read by going to the library, buying used books, downloading free eBooks, or swapping books with other people in your community. Many Australians also like to join book clubs or online reading groups. These groups add a social aspect without over-the-top additional expenses.

                      4. Gardening (Even In Small Spaces)

                      When done right, gardening can become a low-cost hobby for homeowners and renters alike. Better yet, you don’t even need a lot of outdoor space to make it work.

                      Growing herbs on a windowsill or vegetables in containers (possibly even upcycled ones) can help you save money on groceries over time and become a relaxing pastime, regardless of the season. Starting with seeds and recycled pots can lower costs and help you slowly get accustomed to the “green thumb” lifestyle.

                      Make Your Home Gardening-Friendly

                      One essential factor of gardening is natural light, whether it’s outdoors in the sun or through an installed skylight in your home. To maximise the amount of sunlight you can enjoy indoors, a Red Tree Finance online loan can help you make any essential improvements to your home.

                      5. Photography

                      One of the great things about taking up photography as an interest is that you can spend as much or as little on it as you like. Though some people will apply for a $5000 loan to purchase the very best camera, lens, tripod and other equipment, you can get just as much enjoyment from the hobby by using your smartphone camera.

                      As a low-cost hobby, photography is easy to fit into a busy schedule. Photo opportunities can come from anywhere, whether it’s on the walk to the train station or a classic summer sunset over the beach. There is also a plethora of free instructional videos on YouTube to get you started.

                      Five Additional Low-Cost Hobbies To Consider

                      Looking for some other inexpensive interests to pursue this year? Here are 5 more to think about:

                      • Creative writing
                      • Home yoga or stretching
                      • Cooking
                      • Puzzles and brain-training games
                      • Volunteering in the local community

                      Like photography, some of these will have free how-to videos online, so you won’t need to pay for expensive courses if you don’t want to. All of these can potentially bring fulfilment and colour to your life in ways you may not have imagined. And if you’re looking at secured loans to get your new hobby underway, Red Tree Finance is here to help.

                      Enjoy Life More Without Spending More!

                      Low-cost hobbies show that you don’t have to spend a lot of money to have fun. You can improve your health without adding to your financial stress by picking activities that fit your lifestyle and budget. Small, cheap habits can make a big difference over time, whether you like doing creative things, moving around outside, or learning something new.

                      Whether you’re looking at a weekend loan to fund a quick hiking trip in the Aussie bushland, or an instant loan to buy a new camera, Red Tree Finance lets you look at and apply for short-term loans online whenever you need them.

                      Frequently Asked Questions

                      View all FAQs View all FAQs

                      In many cases, the most inexpensive hobbies are those that:

                      • Make use of the skills or resources you already have.
                      • Require very little specialised tools or equipment.
                      • You can do at home or in the local community.

                      These can include activities such as weekend walks, DIY crafts, gardening and reading.

                      This is a widely-regarded personal development concept that suggests people should pursue hobbies in five specific areas in order to live a balanced life. Those categories include hobbies to:

                      • Make money (e.g. photography, blogging)
                      • Stay fit and in shape (running, competitive sport)
                      • Express your creativity (playing an instrument, creative writing)
                      • Build knowledge (learning a new language, reading)
                      • Evolve your mindset (meditation, mindfulness practices)

                      If you’re looking for some funds to start your new hobbies in 2026, Red Tree Finance has loans from $2350 to get you started.

                      There are many hobbies you can take up that don’t cost the earth, from neighbourhood walks to designated hiking trails, to free online courses, smartphone photography or learning a language.

                      The information provided in this blog is of a general nature and is provided without considering your specific objectives, financial situation, or needs. It is intended for informational purposes only and should not be relied upon as financial, investment, or other professional advice.Before making any financial decisions or taking action based on the information presented, you are strongly encouraged to assess its appropriateness in light of your individual circumstances. Red Tree Finance does not intend to provide personalised financial advice, and you should seek independent financial, legal, tax, and other relevant advice tailored to your unique situation.
                      image
                      img
                      image
                      img
                      Apply now

                      Ready to apply for a loan?

                      Apply to borrow up to $5,000 fast. Complete your online application in under 5 minutes.

                      image
                      image
                      image

                      How Much Does It Cost To Elope?

                      February is here! The month of romance, Valentine’s Day, and love truly being in the air. It’s no surprise that February is a popular month for weddings in Australia. In fact, the Australian Bureau of Statistics reported that 24th February was the most popular day to get married in 2024, with 1773 nuptials taking place

                      Guide 23 January 2026

                      In this article:

                        Calculate your loan repayments

                        How much would you like to borrow?

                        Simply. Transparent. Tailored to you.

                        Loan amount:
                        $
                        $2,350 $5,000
                        Repayment frequency:
                        Weekly repayment:

                        (Over 12 month loan term)

                        $0.00
                        • Loan term 12 months
                        • Interest & Fees $1,072
                        • Total to pay $3,172
                        arrow
                          image

                          February is here! The month of romance, Valentine’s Day, and love truly being in the air. It’s no surprise that February is a popular month for weddings in Australia. In fact, the Australian Bureau of Statistics reported that 24th February was the most popular day to get married in 2024, with 1773 nuptials taking place on that day.

                          Elopement vs. Traditional Wedding: The Price Gap

                          As you ask the question, “How much is it to elope?”, it’s well worth comparing the common costs of an elopement against a traditional wedding ceremony and reception.

                          The major difference between the two lies in the “per head” costs. For 100 guests, you could very easily find yourself with a $20,000 bill just for catering, alcohol, and venue hire, before even purchasing a dress.

                          By eloping and opting for a streamlined, small and possibly spontaneous wedding, you put those funds towards other essentials. You might reallocate them towards a high-end wedding photographer or even a special overseas honeymoon.

                          In the end, many Australian couples opt to elope and still enjoy a beautiful ceremony that respects their long-term financial health while maintaining the magic of the moment.

                          Whether you choose to elope or opt for the complete white wedding experience, there are numerous non-negotiable expenses you must include in your budget to make it all official and legal. Thankfully, these costs are the most affordable.

                          To guarantee that your marriage is recognised by law, you’ll need the following:

                          • Notice of Intended Marriage (NOIM): You’ll need to lodge this mandatory form at least one month before your wedding date.
                          • Registry Office Fees: Prices vary by state, but a standard weekday ceremony at a Births, Deaths, and Marriages (BDM) office typically costs between $350 and $550.
                          • Marriage Certificate: A standard official certificate usually costs around $60, which is essential for name-change processes.
                          • Private Celebrant: A private celebrant may charge between $400 and $900 if you’re looking for a ceremony away from the Registry Office.

                          Once you’ve ticked these administrative boxes, you have the legal freedom to marry anywhere you like, from a local park to a remote mountain peak!

                          Choosing Your Style: Budget vs. Luxury Elopements

                          One of the great benefits of eloping is that there is no one set way to approach it. You and your partner might summon friends and family to the local registry office and treat them to a meal at a favourite pub or restaurant afterwards. It’s a relatively inexpensive option that will likely set you back no more than $1,500. Or, you might spend more than $5,000 to fly interstate or overseas with just a couple of witnesses and a celebrant. You still get a small and low-key wedding in a more deluxe location.

                          There are no set rules for how much it costs to elope. You can do – and spend – what you like.

                          Many couples typically spend somewhere between $2,000 and $5,000 on the conventional trimmings associated with weddings (i.e. flowers, photography and outfits), without the additional expenses of a 100-person guest list. Compare that to the $36,000 cost for the average Australian wedding, and it’s easy to see why eloping becomes an appealing option.

                          Hidden Costs To Budget For

                          Even a micro wedding has its logistical quirks and hidden costs you’ll need to prepare for if you want to avoid unexpected spending. While you may save on reception catering, you should still account for the professional services that help you preserve the memory of your day.

                          Keep These In Mind

                          To help you plan a realistic budget, keep these common “hidden” expenses in mind:

                          • Professional photography: Most eloping couples spend the bulk of their budget on photography, with short-coverage packages starting around $1,500.
                          • Council permits: If you plan to marry on a public beach or in a botanical garden, you likely need a permit. This may cost anywhere from $100 to $500.
                          • Travel and transport: Don’t forget to include Uber fares, fuel, or even a chauffeured car to get you to and from your location.
                          • Dress and suit alterations: Even a second-hand or high-street dress often requires professional tailoring to fit perfectly.

                          Budgeting for these smaller expenses will keep your special day stress-free and without last-minute financial surprises.

                          Explore Australia’s Backyard With A Destination Elopement

                          It’s no secret that Australia is rich with some of the world’s most stunning locations for an elopement wedding. From the rugged cliffs of Tasmania to the tropical Whitsundays, we are certainly spoiled for choice.

                          Travelling interstate can be a great way to turn your wedding day into an extended holiday. While the flights and luxury accommodation may increase overall costs, they often double as a “staycation” honeymoon.

                          Many island resorts around Australia now offer specific elopement packages that include a celebrant, flowers, and a romantic dinner for two, often costing around $3,000. Packages like these can make the planning process significantly easier, allowing you to show up and enjoy the ride (as well as the picturesque scenery).

                          How A Personal Loan Can Help Create The Perfect Day

                          Even a modest elopement budget can benefit from a little extra financial leg-up to make the experience really special.

                          If you have found the perfect photographer or dream dress that may take you over your planned budget, but you know they’ll really elevate the occasion, a small personal loan can bridge the gap. At Redtree Finance, we provide quick and transparent lending options up to $5,000, allowing you to fund your wedding costs upfront, without draining your emergency savings.

                          By spreading the cost into manageable instalments, you can focus on the excitement of your upcoming nuptials rather than checking your bank balance every time you book a vendor.

                          Choose A Quality Wedding Over Quantity

                          At the end of the day, the answer to “how much does it cost to elope?” depends entirely on your personal values and how you want to remember your wedding day.

                          Whether you spend under $1,000 for a registry wedding, budget $2,000 for a beach or forest ceremony, or spend $5,000 for a destination wedding, the result is the same: a legal, loving commitment to your partner. By choosing an intimate ceremony, you are choosing to start your married life on a solid financial footing.

                          If you are ready to start planning but need a little assistance to cover the costs of your rings, attire, or travel, Redtree Finance is here to help. Our straightforward application process is designed for everyday Australians who want to make their milestones happen today.

                          If you’re looking to reduce costs for your big day, getting married at the Registry Office will be the cheapest option. In South Australia, the maximum number of attendees is 30, including the couple, the legally required two witnesses, photographers, and any other guests. You’ll be charged a total of $436.00, which includes the $138 Notice of Intended Marriage fee and ceremony/venue hire of $294. Other states and territories in Australia may have a different fee structure.

                          Definitely! Once you have paid all the essential legal and administrative fees and charges to make your marriage official, you can spend as much or as little as you like on your wedding ceremony. Red Tree Finance offers secured loans up to $5,000 that you can use to fund your big day or supplement any savings that you’ve already accumulated for your wedding.

                          In the same way that you’d apply the 50/30/20 rule to budgeting for a family income, you can do the same as you plan your wedding. In this context, you would allocate 50% of your budget to the essentials such as venue hire, catering and outfits. 30% will go to things like booking a photographer and entertainment, as well as the venue decor. Set aside 20% for those factors you can’t always plan for, like extra guests or any other unplanned expenses.

                          The information provided in this blog is of a general nature and is provided without considering your specific objectives, financial situation, or needs. It is intended for informational purposes only and should not be relied upon as financial, investment, or other professional advice.Before making any financial decisions or taking action based on the information presented, you are strongly encouraged to assess its appropriateness in light of your individual circumstances. Red Tree Finance does not intend to provide personalised financial advice, and you should seek independent financial, legal, tax, and other relevant advice tailored to your unique situation.
                          image
                          img
                          image
                          img
                          Apply now

                          Ready to apply for a loan?

                          Apply to borrow up to $5,000 fast. Complete your online application in under 5 minutes.

                          image
                          image
                          image

                          How To Budget For A Family Income

                          Grocery shopping. School supplies and sports team fees. Utility bills. Day-to-day costs for Australian families certainly add up fast. Therefore, you cannot overstate the importance of knowing how to budget for a family income.

                          Budgeting 15 October 2025

                          In this article:

                            Calculate your loan repayments

                            How much would you like to borrow?

                            Simply. Transparent. Tailored to you.

                            Loan amount:
                            $
                            $2,350 $5,000
                            Repayment frequency:
                            Weekly repayment:

                            (Over 12 month loan term)

                            $0.00
                            • Loan term 12 months
                            • Interest & Fees $1,072
                            • Total to pay $3,172
                            arrow
                              image

                              Grocery shopping. School supplies and sports team fees. Utility bills. Day-to-day costs for Australian families certainly add up fast. Therefore, you cannot overstate the importance of knowing how to budget for a family income.

                              What Is A 50/30/20 Budget?

                              If there is one rule that makes knowing how to budget for a family income significantly easier, it’s the 50/30/20 budget.

                              It’s a fairly straightforward system that divides your income into three key categories. You split up your pay like this:

                              • 50% goes to essential living expenses (e.g. food, rent, bills, transport)
                              • 30% goes to “wants” and lifestyle expenses such as clothing, movies, restaurants, etc
                              • 20% goes towards your savings and short/medium/long-term goals

                              The 50/30/20 budget system provides a straightforward and structured approach to creating an achievable family budget. It enables you to prioritise the immediate financial needs and wants of your family, while not neglecting any long-term goals you may also have.

                              To put this system into action, you’ll need to track the money coming in and the money going out. This is how to go about it.

                              Assess The Family Income (Money In)

                              The all-important first step is to record the money coming into the household. This might include anything from wages or salary payments to share dividends, pensions or Government benefits.

                              You’ll want to record how much income you receive, where that income comes from and how frequently you receive it (i.e. weekly, monthly, annually).

                              Calculate Your Expenses (Money Out)

                              Once you’ve recorded the money coming in, you need to record your expenses. They typically fall under three categories:

                              • Fixed expenses – rent or mortgage payments, utility bills, council rates, food and groceries.
                              • Debt expenses – credit card payments, loan repayments.
                              • Unplanned expenses – medical bills, car repairs, etc.

                              You’ll want to record information like the amount of the expense, the frequency with which you pay it (weekly, fortnightly, monthly) and the day or date it comes out. An Excel spreadsheet can be an effective visual tool for this. You can see the money coming in, the money going out, and let Excel do all the necessary calculations that will help you put the 50/30/20 system into practice.

                              Why You Need A Budget In Place

                              Knowing how to budget for a family income will help you to see how much money you have coming into the household and how much money you have going out. That way, you have the financial information in front of you to better plan for the immediate and long-term future.

                              Budgeting helps you meet short and long-term financial goals. When you set these goals, whether it’s to save up for an overseas trip or a down payment on a house, it

                              pays to take the SMART approach to goal setting.

                              You’ll see everyone from the big four banks to the Australian Government’s MoneySmart website using this acronym; it stands for goals that are:

                              • Specific
                              • Measurable
                              • Achievable
                              • Realistic or relevant
                              • Time-bound

                              Also important and something that will largely determine your budgeting approach is whether you’re setting short, medium or long-term goals.

                              Setting and Meeting Short, Medium and Long Term Family Budget Goals

                              How to budget for a family income can differ depending on whether you’re setting short-term goals or looking at the bigger, long-term picture.

                              Let’s put the five SMART components into common examples for each end of the scale.

                              Short-term goals are typically those that you’ll achieve within 0-2 years. So, whether you’re saving $700 for a PlayStation or $7000 for a holiday, this is the easiest way to go about it.

                              • Specifics – The family wants to save $7000 for an overseas holiday.
                              • Measurable – They set up a new savings account to save that money.
                              • Achievable – Both income earners create an automatic transfer that deducts $50 from their weekly or fortnightly pay and deposits it into the new account.
                              • Realistic – They know to keep the goal achievable and relevant, and make any necessary changes should financial circumstances change. That may involve increasing or decreasing your automatic payment to keep within your family budget.
                              • Time-bound – The family sets a time frame in which they aim to achieve their goal (e.g. “We want to save $7000 within 12 months / by the end of the year).

                              Medium-term goals typically sit within the 3-5 year timeframe and may include saving for a house deposit, paying off a credit card debt, or buying a new car. In this situation, you might follow a similar process to the one above. For medium-term goals, consider opening a higher interest-earning account, increasing the amount of your regular payments and keeping the goal within reach, depending on your income and budget needs.

                              One of the most common long-term goals for families, taking five or more years, is paying off credit card debt. This is how you might put a long-term SMART goal into action while still maintaining a comfortable day-to-day lifestyle.

                              • S – I want to pay off my credit card balance in two years.
                              • M – I will make more than just the minimum monthly payments.
                              • A – Instead of monthly payments of $200, I will increase those payments to $300.
                              • R – I will keep this goal within reach depending on my income and budget circumstances.
                              • T – The timeframe may vary depending on the value of the debt and the minimum repayment amounts.

                              Whether your goals are at the short-term end of the spectrum or you’re looking more long-term, it’s important to keep yourself accountable. Don’t get too down if you stray from the path or find you can’t maintain the pace. Make any necessary changes to your SMART goals that help you get back on track.

                              4 Essential Tips For Sticking To The Family Budget

                              Now your family budget is in place, how will you stick to it? It will take some discipline, but some proven tips can help make it easier.

                              • Monitor the budget regularly – Keep track of your income and expenses every month to gauge whether your current budget plan still works for you. Changes to your income and expenses might warrant a revision of your plan.
                              • Look for ways to trim the expenses – If it’s been months since you actually used your premium Netflix account, or you can’t remember the last time you reviewed your energy bills, these might present good opportunities to save money.
                              • Make changes to your savings plan when necessary – Don’t feel like you’re locked in to putting aside $100 a week into your savings account forever. Changes to employment or life circumstances may require you to tweak your savings plan once in a while.
                              • Celebrate your wins! – Sticking to a budget is an achievement worth celebrating! Once you reach a financial goal, enjoy the moment!

                              There are plenty of online budget tools and smartphone apps that can help you track your spending and maintain your commitment to your budget.

                              Budgeting For Family Emergencies

                              One important factor to consider regarding how to budget for a family income is the possibility of emergencies. They happen to any family, whether it’s unplanned medical bills, a sudden loss of employment, or unexpected damage to the house.

                              Saving for an emergency fund is well worth factoring into your family budget. Here’s what you need to do.

                              Determine How Much You Want To Set Aside

                              Working out how much you need in your emergency fund is the first step.

                              The general rule of thumb is to look towards keeping enough in your fund to cover two to three months of regular expenses. This is the typical waiting period to access your superannuation or insurance in the event that you cannot work. Of course, you may want to consider having enough in there for a longer period.

                              Determine What Counts As An Emergency To You

                              Set a clear definition as to what constitutes an emergency and stick to it. Replacing a broken toaster, while inconvenient, may be better suited to a “rainy day” fund.

                              Open A Savings Account

                              Just as you set up an account to reach your savings goals, doing the same for an emergency account will help immensely. Factor this into your 50% part of your budget.

                              Consider A Loan

                              As we’ve said before, a loan is never a replacement for a savings plan. However, it can be especially useful when you find yourself in an emergency situation. Red Tree Finance has quick and helpful loan options available to help you out when you need it most.

                              Take The First Steps Towards A Better Financial Future

                              Whether you already have a family budget or creating one is on the to-do list, structure and flexibility go a long way towards securing a better financial future. It enables you to set and achieve small or large financial goals while also maintaining a comfortable day-to-day lifestyle.

                              Red Tree Finance can also help you with our household-friendly cash loan options. Whether you’re planning a holiday or fixing up the house, or simply want to cut up your credit card once and for all, speak to us to see how we can assist.

                              FAQ – Common Family Budget Questions

                              View all FAQs View all FAQs

                              The 50/30/20 rule is an easy-to-follow household budgeting system that helps families manage their finances with relative ease. The idea is that you set aside 50% of your after-tax income for essential expenses like food, rent or mortgage payments, and utility bills. You put 30% of your income towards lifestyle expenses that are more “want” than “need”, such as eating at restaurants, streaming subscriptions and other hobbies. The remaining 20% of your income goes into a savings account that may be used as an emergency fund or to achieve a savings goal.

                              The 70/20/10 rule is effectively the same as the 50/30/20 rule, but with the percentages adjusted for families that want to set more realistic goals. They may come from more expensive neighbourhoods or be operating on a lower income. You use 70% of your net income for essential expenses and 20% for lifestyle expenses, with the remaining 10% going into savings.

                              First and foremost, what you need to do is get a comprehensive understanding of your household finances by listing the money coming in (your income) and the money going out (your expenses). The expenses should include anything that is fixed and consistent, like utility costs, house payments and council rates, and any variable payments. Once you’ve listed your expenses, separate them into essentials and non-essential payments, and work out where you may be able to reduce those expenses. It’s also a good idea to set up a savings account and create clear financial goals using the SMART method.

                              The information provided in this blog is of a general nature and is provided without considering your specific objectives, financial situation, or needs. It is intended for informational purposes only and should not be relied upon as financial, investment, or other professional advice.

                              Before making any financial decisions or taking action based on the information presented, you are strongly encouraged to assess its appropriateness in light of your individual circumstances. Red Tree Finance does not intend to provide personalised financial advice, and you should seek independent financial, legal, tax, and other relevant advice tailored to your unique situation.
                              image
                              img
                              image
                              img
                              Apply now

                              Ready to apply for a loan?

                              Apply to borrow up to $5,000 fast. Complete your online application in under 5 minutes.

                              image
                              image
                              image

                              10 Last Minute Date Ideas: On A Budget

                              Life can get busy, but planning a last-minute date on a budget doesn’t have to be stressful. Sometimes, a little extra support, like a fast loan, can help you create those special experiences but there are plenty of affordable ways to spend quality time with your partner in Australia.

                              Budgeting 13 August 2025

                              In this article:

                                Calculate your loan repayments

                                How much would you like to borrow?

                                Simply. Transparent. Tailored to you.

                                Loan amount:
                                $
                                $2,350 $5,000
                                Repayment frequency:
                                Weekly repayment:

                                (Over 12 month loan term)

                                $0.00
                                • Loan term 12 months
                                • Interest & Fees $1,072
                                • Total to pay $3,172
                                arrow
                                  image

                                  Life can get busy, but planning a last-minute date on a budget doesn’t have to be stressful. Sometimes, a little extra support, like a fast loan, can help you create those special experiences but there are plenty of affordable ways to spend quality time with your partner in Australia.

                                  10 Last Minute Date Ideas: On A Budget

                                  1. Sunset picnic at the beach

                                  You don’t need to plan a romantic getaway for your partner when the weather’s warm – you can just head to the closest beach! Pack snacks from home, a blanket, and some cold drinks for a simple and romantic picnic by the ocean. It’s free, and the beach offers a beautiful backdrop for conversations and relaxation. Ideal for mornings, sunsets, or lazy afternoons.

                                  2. Outdoor movie night in the park

                                  Not every date needs to be out of the house! If you’re low on income or wanting to save money why not opt for a cosy and affordable date, turn your living room into a home theatre. Choose a movie you’ve both wanted to watch, grab some popcorn, and create a cinema-like experience at home. You can stream movies for free or rent them online, making it a great option when time and money are tight. Perfect for evening wind-downs.

                                  3. Hiking adventure

                                  To create a memorable last-minute date, a hiking adventure is an excellent choice. Not only is it budget-friendly – it’s often free if you choose local trails. Hiking also offers a chance to connect with nature and each other. Grab your hiking shoes, pack some water, and set off for a nearby trail.
                                  This date is perfect for a spontaneous weekend outing or even a weekday evening if you have time to catch the sunset. Plus, the physical activity can release serotonin, boosting mood and energy levels, making it a great date when you want to make a good impression.

                                  4. Local farmers market

                                  On the weekend, why not check out a nearby farmers market? It’s free to walk around, and you can grab inexpensive snacks, explore local crafts, and enjoy a relaxed outdoor atmosphere.
                                  If you’re in Melbourne and looking for a cheap but fun date, you can visit the Queen Victoria market or South Melbourne market. It’s a fun and budget-friendly way to spend a few hours while supporting local producers, you can even save money on your weekly grocery shop at the same time.

                                  5. Coffee date

                                  Something super simple but affordable is a cute coffee date. If you’re looking for something quick and easy, find a local café, order your favourite coffee or tea, and sit outside for some people-watching. It’s a low-cost way to enjoy each other’s company, chat, and soak up the local atmosphere. Great for mornings or early afternoons when the world is bustling around you.

                                  6. Board games or card night

                                  If you’re in the mood to stay in, challenge your partner to a fun board game or card game. You likely already have a deck of cards or a game at home, making this a zero-cost date idea that can bring out a playful side in both of you. Perfect for a relaxed evening or lazy Sunday afternoon.

                                  7. Ice cream trip

                                  Who doesn’t love ice cream? When you’re low on time and looking for a quick, affordable date idea, a spontaneous ice cream or gelato run is perfect. Head to your favourite local spot and enjoy a few scoops together.
                                  It’s budget-friendly, as ice cream or gelato rarely costs more than a few dollars per person, making it an ideal treat for those on a tight budget.

                                  Many Australian cities offer free or donation-based entry to museums and galleries. This is a perfect last-minute date when you’re looking for something cultural and interesting to do. You’ll have a chance to explore new exhibits together and spark interesting conversations, all without spending much.
                                  If you’re in South Australia, both the museum and art gallery are free to explore and are in close proximity to each other, so you can visit both for no cost at all if it fits into your schedule.

                                  9. Bike ride around town

                                  A bike ride around your local area is a great last-minute and budget-friendly date idea. If you both have bikes, this date is essentially free! It’s a fun way to explore new parts of town or revisit favourite spots.
                                  You can pack a small snack or stop at a local park for a rest. This is an ideal daytime date for weekends or evenings when the weather is pleasant, giving you both the chance to enjoy some light exercise and fresh air together without spending much. Plus, it’s flexible – you can adjust the ride length to suit your schedule.

                                  10. Wine and cheese night

                                  Create a fancy wine and cheese night at home with supermarket bargains. Buy a budget-friendly bottle of wine and some affordable cheese, crackers, and fruit. Set it up on the dining table or your balcony for an intimate and low-cost evening in.
                                  This is perfect for a spontaneous evening date when you want to feel indulgent without spending too much.

                                  Splurge on romance with Red Tree Finance

                                  You don’t need to spend a fortune to have a memorable time with your partner. These date ideas prove that romance can thrive on a budget but if you are looking to spoil yourself to your partner with a cheap vacation in Australia or fun weekend out, Red Tree Finance is here to help.
                                  With a small cash loan of up to $5,000, you can cover any unexpected expenses while staying on top of your budget. Apply now for a personal loan and enjoy more stress-free moments with your loved ones.

                                  Yes, last-minute dates can be a great idea! They add spontaneity and excitement to your relationship, showing that you don’t need elaborate plans to have fun or create meaningful memories.

                                  Planning a last-minute date is all about keeping it simple. Choose activities that don’t require reservations or lots of preparation, such as a coffee date, stargazing, or a home movie night.

                                  Yes! Red Tree Finance offers small loans up to $5,000 that can be used for a variety of personal expenses, including treating your partner to a special date.

                                  The information provided in this blog is of a general nature and is provided without considering your specific objectives, financial situation, or needs. It is intended for informational purposes only and should not be relied upon as financial, investment, or other professional advice.

                                  Before making any financial decisions or taking action based on the information presented, you are strongly encouraged to assess its appropriateness in light of your individual circumstances. Red Tree Finance does not intend to provide personalised financial advice, and you should seek independent financial, legal, tax, and other relevant advice tailored to your unique situation.
                                  image
                                  img
                                  image
                                  img
                                  Apply now

                                  Ready to apply for a loan?

                                  Apply to borrow up to $5,000 fast. Complete your online application in under 5 minutes.

                                  image
                                  image
                                  image

                                  How Many Cash Loans Can You Have All At Once?

                                  With rising costs of living and continual bills to pay you may find yourself considering taking out an additional small personal loan to help with unexpected expenses. However, if you already have a loan, you need to consider how many loans you can afford repayments for. Dive in as we explore the pros and cons

                                  Loans Advice 11 August 2025

                                  In this article:

                                    Calculate your loan repayments

                                    How much would you like to borrow?

                                    Simply. Transparent. Tailored to you.

                                    Loan amount:
                                    $
                                    $2,350 $5,000
                                    Repayment frequency:
                                    Weekly repayment:

                                    (Over 12 month loan term)

                                    $0.00
                                    • Loan term 12 months
                                    • Interest & Fees $1,072
                                    • Total to pay $3,172
                                    arrow
                                      image

                                      With rising costs of living and continual bills to pay you may find yourself considering taking out an additional small personal loan to help with unexpected expenses. However, if you already have a loan, you need to consider how many loans you can afford repayments for. Dive in as we explore the pros and cons of multiple loans and when to consider a consolidation loan.

                                      Factors That Determine How Many Cash LoansYou Can Have

                                      Your ability to take out an additional loan will depend on your credit score, debt repayment history, income, and other liabilities. Responsible lending practices ensure that your lender puts your interests first, ensuring that you can afford the loans that you have and reducing the risk of you missing a payment or falling into default.

                                      Borrowing Power: Your Income And Ability To Repay

                                      The first consideration that determines whether you can take out an additional loan is whether you have enough spare cash flow to meet the repayments, after taking into account your current expenses and financial obligations.

                                      Do You Already Have A Secured Loan Against Your Vehicle?

                                      One way you may be able to qualify for an additional loan is by using your vehicle as security. If you don’t have an existing car loan or another personal loan secured against your car, this can give the lender additional confidence to provide you with the cash you need.

                                      Whilst you’ll still need to meet the other lending criteria, including having income to cover your repayments, using your car as security may allow you to take out a second personal loan.

                                      Other Loans And Liabilities You Hold

                                      When you apply for a second loan, the lender will consider your other loans, including any credit card balances, personal loans, mortgages, university debts and so on. Your debt-to-income ratio is one factor that may determine how many cash loans you can have at once.

                                      One option if you do have multiple loans already is to consolidate those loans into one. This means you will make just one repayment which can help you to have a clear view of your finances and pay off your debts systematically.

                                      Tips For Managing And Repaying Multiple Cash Loans

                                      Sometimes taking out multiple loans can help you through an expensive period of time, but you can still create a plan to ensure that you keep up with your expenses.

                                      Create A Budget

                                      Juggling various loan obligations means you will want to consider implementing and following a budget. One way you can do this is to prioritise your repayments and bills first before any discretionary spending.

                                      Pay On Time

                                      The easiest way to ensure bills are made is to automate it, with direct debits for your bills and repayments. For ongoing bills like council rates or electricity, you might choose to leave bill emails unopened until you have time to pay them so that they are not missed.

                                      Put In Extra

                                      Once you are happy with your budget and everything is running smoothly, you might try to save a little extra and pay down your loan balance- doing this may mean you pay less interest across the lifetime of the loan and pay off the amount you owe a little faster.

                                      Determining Your Personal Cash Loan Limit

                                      To work out how much you are comfortable repaying, evaluate your monthly income, fixed expenses, and any existing debts. You may consider your financial goals and ongoing financial obligations to identify how much debt you can reasonably manage.

                                      Remember that things can change – like your job or primary income source. Think about how potential changes in your income or expenses may affect your overall spending, and be mindful that you want to be comfortable with repayments on an additional loan.

                                      When taking out an additional personal loan, make sure you understand:

                                      1. What loan fees and charges will you need to pay, and when you will need to pay them
                                      2. The interest rate and how it works
                                      3. What happens if you don’t pay the loan back on time

                                      A personal loan from Red Tree Finance can help you get through a tricky time

                                      Whether it’s a car breakdown, unexpected bills, school fees or medical expenses, sometimes an additional loan can help you stay on top of your finances. Our small personal loans are secured against a vehicle, and repayable within a year. To learn more about taking out a second cash loan to cover unexpected bills, pay for an emergency or something else, speak with our friendly team.

                                      Frequently Asked Questions

                                      View all FAQs View all FAQs

                                      You can get another loan straight away, provided you meet the lending criteria. With some lenders, you may even be able to take out a loan before your current loan is paid off. However, a responsible lender will ensure that you can only borrow what you can reasonably afford to repay.

                                      You can have multiple loans if approved by lenders, not all lenders will approve a second or third loan. If you have a car you can use as security this may help you to be approved for a second loan. Managing multiple loans can strain your budget, so be sure to consider your options before applying

                                      Yes, you can have multiple loans from different lenders, provided lenders will approve your applications. The approval and terms of each loan will depend on several factors, including your creditworthiness, income, and the lending policies of the banks involved. The more loans you take out the harder it may be to qualify for a new loan.

                                      The information provided in this blog is of a general nature and is provided without considering your specific objectives, financial situation, or needs. It is intended for informational purposes only and should not be relied upon as financial, investment, or other professional advice.

                                      Before making any financial decisions or taking action based on the information presented, you are strongly encouraged to assess its appropriateness in light of your individual circumstances. Red Tree Finance does not intend to provide personalised financial advice, and you should seek independent financial, legal, tax, and other relevant advice tailored to your unique situation.
                                      image
                                      img
                                      image
                                      img
                                      Apply now

                                      Ready to apply for a loan?

                                      Apply to borrow up to $5,000 fast. Complete your online application in under 5 minutes.

                                      image
                                      image
                                      image

                                      Why Do Loan Companies Ask For Employers Details?

                                      When applying for a loan, you might wonder why loan companies ask for employers details. Well, a lender will only ever contact an applicant’s employer in certain circumstances but the information is always vital. There are some good reasons behind this when applying for a cash loan and we'll explore 4 key points that shed

                                      Financial Help 6 August 2025

                                      In this article:

                                        Calculate your loan repayments

                                        How much would you like to borrow?

                                        Simply. Transparent. Tailored to you.

                                        Loan amount:
                                        $
                                        $2,350 $5,000
                                        Repayment frequency:
                                        Weekly repayment:

                                        (Over 12 month loan term)

                                        $0.00
                                        • Loan term 12 months
                                        • Interest & Fees $1,072
                                        • Total to pay $3,172
                                        arrow
                                          image

                                          Applying for a personal loan can be a significant financial decision that most prospective borrowers don’t make lightly. In many cases, they do so for an important reason. When applying for a loan, you might start wondering, “Can loan companies call your employer?”

                                          Four Reasons Why Loan Companies May Ask For Employer Details

                                          The fundamental obligation with any cash loan is that you, as the borrower, repay the principal sum with interest back to the loan company. As part of their responsible lending obligations, a reputable lender may want to contact your employer to ensure you’re in a financially sound enough position to meet your repayment obligations.

                                          Here are four key reasons lenders may ask for your employment details before deciding on your loan application.

                                          1. Income Verification

                                          One of the key reasons lenders ask for your employer information is to confirm that you are gainfully employed and receive a stable and consistent income. They want to make sure that you are capable of comfortably meeting the repayment terms of your loan without putting yourself in financial hardship. Your income level is a crucial factor that helps lenders assess your ability to repay the borrowed funds.

                                          2. Risk Assessment

                                          Lenders also use your employment details to gauge the level of risk associated with your loan application. Steady employment with a secure and reputable company may reduce your perceived risk level in the eyes of the lender. On the other hand, if you frequently change jobs, work in an unstable industry or haven’t been with your employer for very long, this might affect your eligibility for a personal loan. For the lender, your employment history ultimately provides valuable insights into your financial stability.

                                          3. Contact Information

                                          In some cases, lenders may collect your employer’s details for contact purposes. While lenders generally won’t contact your employer about your loan application, having this information is valuable should they need to reach you about your loan. For security and privacy purposes, it’s important for lenders to have various contact options for you.

                                          4. Fraud Prevention

                                          While lenders won’t typically contact your employer during the loan application process, they may seek your employer’s information to prevent any fraudulent activity or identity theft in your name. Lenders will confirm your employment details to verify your identity. This creates an added layer of security that protects both you and the lender from the consequences of fraudulent activity.

                                          What Employer Details Do Lenders Typically Ask For?

                                          When you submit an application with a lender, that loan company will usually ask for a small, standard set of employer details. This required information usually includes:

                                          • The name of your employer
                                          • Your job title or position
                                          • How long you’ve worked there (start date or length of employment)
                                          • Employment type – full-time, part-time, or casual
                                          • Your gross income (i.e. what you’re paid before tax comes out)
                                          • A contact number for your workplace – this is for verification purposes rather than for discussing your application

                                          How Lenders Can Confirm Your Employment Without Contacting Your Workplace

                                          Lending companies can often directly confirm your employment and income information from the documents you provide as you apply for your loan, rather than by contacting your workplace. As part of its online loan application process, Red Tree Finance asks you to provide payslips, 90 days of bank statements, and two forms of identification. While they may not always rule out the need for employer contact, these documents generally provide lenders with the information they need to verify an application without involving the applicant’s workplace.

                                          What If I’m Self-Employed or Don’t Have a Traditional Employer?

                                          Across Australia, the working landscape is shifting. With data from August 2025 showing over 1.1 million independent contractors and nearly 850,000 sole proprietors nationwide, lenders are increasingly familiar with non-traditional employment and have streamlined their processes to accommodate self-employed applicants.

                                          At Red Tree Finance, we understand that not everyone applying for a loan will have a traditional employer. If you’re self-employed or a contractor, you will still need to show three months of consistent and recent income. You’ll just likely be asked for different supporting documents instead of employer contact details. That might include recent bank statements, income statements, or other proof of income.

                                          Helpful Tips For A Smooth Loan Application

                                          Whether you’re applying for an emergency loan to cover an urgent payment, or a holiday loan to enjoy some much-needed R&R, consider these helpful tips to facilitate a smoother loan application process:

                                          • Have your employer’s correct legal business name and contact number ready.
                                          • Keep one or two recent payslips or income statements on hand.
                                          • Know your employment start date and job title. These will usually appear on your employment contract.
                                          • If you’re self-employed or a contractor, make sure you have your most recent bank statements or income documentation ready.
                                          • Confirm that your details match what’s on your payslips exactly, to avoid unnecessary complications.

                                          Apply with Confidence: What Really Happens With Your Employer Details

                                          So, can loan companies call your employer? Generally, they won’t call to discuss your loan application, but they may call to confirm specific information that can influence the ultimate decision on your application. Lenders will usually get the required information from the documents they ask you to provide, including payslips, bank statements, and other income details. However, if those documents don’t have sufficient information, the loan company may contact your workplace directly.

                                          Employer information exists to verify your income, assess risk, and protect you from fraud, not to alert your employer to your application. Whether you’re employed or run your own business as an independent contractor, being upfront and accurate with your details is the best way to keep your application moving smoothly.

                                          Frequently Asked Questions

                                          View all FAQs View all FAQs

                                          No, lenders typically do not contact your employer to discuss any loan application details. They may contact your employer to seek important employment information, which they will use as evidence of your continuing income, ability to repay the loan, and for verification purposes. But loan companies will not disclose your application to your workplace.

                                          Your employment history is essential for lenders to assess your financial stability. A stable job with a consistent income can increase your chances of loan approval, while frequent job changes or employment in an unstable industry might affect your eligibility.

                                          Though lenders won’t always contact your employer, they may do so to confirm your employment status and income. This process also acts as an important security measure to verify your identity and prevent fraudulent activity from happening in your name.

                                          The information provided in this blog is of a general nature and is provided without considering your specific objectives, financial situation, or needs. It is intended for informational purposes only and should not be relied upon as financial, investment, or other professional advice.

                                          Before making any financial decisions or taking action based on the information presented, you are strongly encouraged to assess its appropriateness in light of your individual circumstances. Red Tree Finance does not intend to provide personalised financial advice, and you should seek independent financial, legal, tax, and other relevant advice tailored to your unique situation.
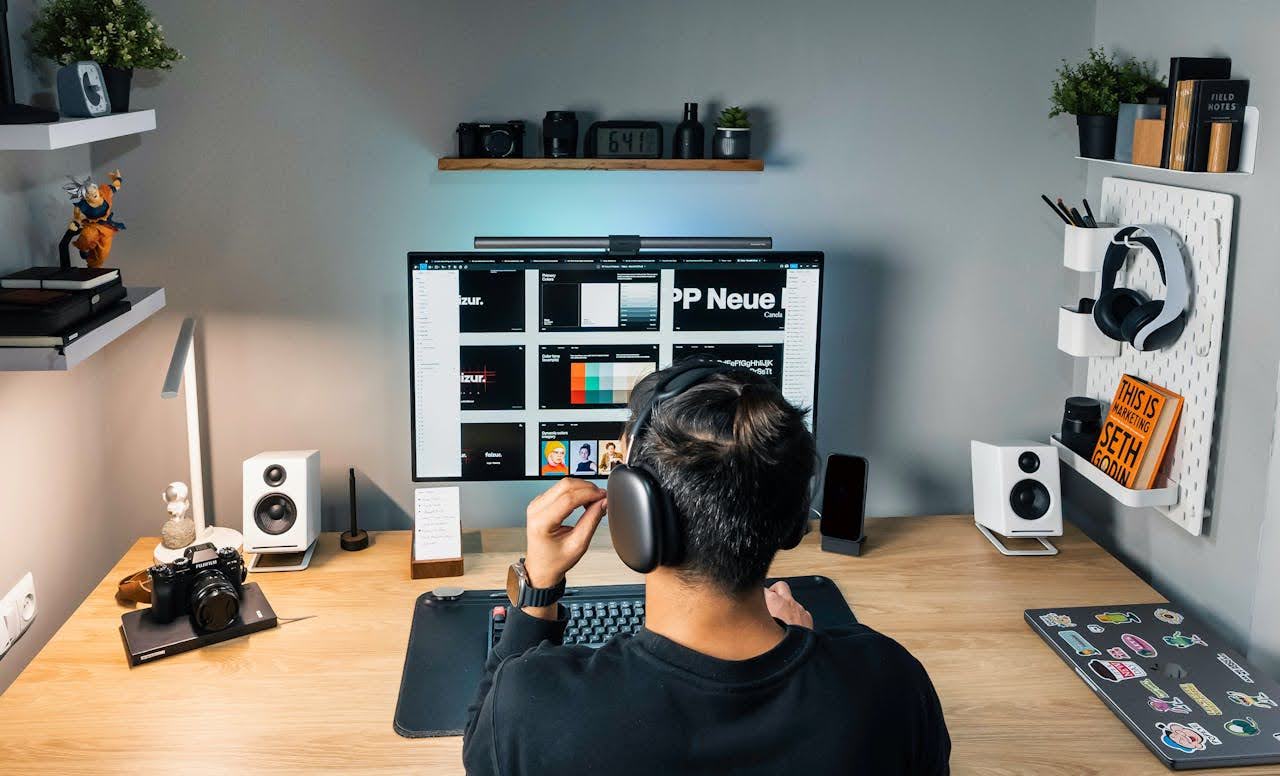
                                          image
                                          img
                                          image
                                          img
                                          Apply now

                                          Ready to apply for a loan?

                                          Apply to borrow up to $5,000 fast. Complete your online application in under 5 minutes.

                                          image
                                          image
                                          Apply now Apply now