Perth is a vibrant city brimming with opportunities for romantic adventure. Whether you're planning your first date or making time with your long-term partner, start planning your weekend date with our free date ideas.
Perth is a vibrant city brimming with opportunities for romantic adventure. Whether you’re planning your first date or making time with your long-term partner, start planning your weekend date with our free date ideas.
4 free date ideas in Perth
1. Explore art galleries
Many galleries host exhibitions and events which can be the perfect free date idea. The Art Gallery of Western Australia and the Western Australian Museum are perfectsome ideas of places to explore. These venues provide an opportunity to wander side by side, where conversation can flow more easily and be prompted by the artworks and installations around you.
2. Go on a picnic
Kings Park offers breathtaking views of the city and the Swan River. Pack a picnic, and a rug and find a cosy spot somewhere in the park. Enjoy the beautiful botanical gardens, take a stroll along the Lotterywest Federation Walkway, and watch the sunset from Fraser Avenue Lookout. A ‘bring-you-own’ style date is a savvy way to save money on a low income.
3. A coastline walk and swim
One of the simplest date ideas is a walk or a dip somewhere along Perth’s stunning coastline. There are plenty of options around Perth, including Cottesloe Beach, City Beach, Trigg Beach, Coogee Beach, Scarborough Beach and many more to choose from. A coffee somewhere along the way might be the only expense on this date.
4. Go for a bushwalk
A 15-minute drive from the Perth CBD, Bold Park is a huge area of inner city bushland that features over 15km worth of walking trails and a variety of lookouts with views of the city and coast. Perfect for a more adventurous date, bring along some snacks and hit the trails.
Dating on a budget is possible
Sticking to your budget is no barrier to enjoying fun dates and creating new memories. With these free date ideas you are set up for weeks of fun, then when a special occasion or anniversary comes along, you might consider a romantic getaway to raise the bar and let that special person know how much you care.
Go for a scenic walk. Enjoy free local events run by councils, libraries, not-for-profits and community centres. Find a good view and have a picnic. Take a long drive or train trip somewhere new. Explore museums and art galleries.
The key to dating on a budget is to be open and honest about your financial situation. Avoid trying to match other couples’ extravagant spending—this can lead to problems. Instead, concentrate on creating a deeper bond through open communication, shared interests and values.
Some creative ideas include thoughtful gifts, quality time and kind acts of service:
Write a poem
Cook a romantic dinner at home
Pack a sunset picnic
Pick wildflowers for a gift
Help with a tricky task or chore
Go for a walk or hike in a scenic location
Plan a ‘treasure’ hunt of romantic Post-it notes
Curate a personal playlist
The information provided in this blog is of a general nature and is provided without considering your specific objectives, financial situation, or needs. It is intended for informational purposes only and should not be relied upon as financial, investment, or other professional advice.
Before making any financial decisions or taking action based on the information presented, you are strongly encouraged to assess its appropriateness in light of your individual circumstances. Red Tree Finance does not intend to provide personalised financial advice, and you should seek independent financial, legal, tax, and other relevant advice tailored to your unique situation.
News
Other blog articles
From budgeting tips to ways to make your money go further, we’ve got it all. Get financially savvy with the Red Tree Finance blog.
We all rely on our cars to get us to and from work, the shops, or simply to get from A to B. And while regular car servicing and maintenance are important measures that keep our cars running smoothly, sometimes unexpected car troubles occur that require professional attention, leaving you with an often costly car repair bill.
Life can throw financial curveballs from many directions, whether it’s unplanned car repairs, emergency medical bills, or even a spontaneous overseas family trip. When cash is tight, many Australians turn to a personal loan to ease the pressure. It's a fixed lump sum you repay with interest over time – problem solved.
Are you looking to build up some quick cash in your account to fund your next adventure or pay off some bills? While cash loans can present as one solution, it’s entirely likely that you’re sitting on a goldmine right at home.
When it comes to managing finances, a personal loan can be a valuable tool for men seeking financial flexibility or access to cash ahead of major life events such as moving out of home, starting a family or buying a car. We'll explore essential tips to help you make the most of personal loans while
When it comes to managing finances, a personal loan can be a valuable tool for men seeking financial flexibility or access to cash ahead of major life events such as moving out of home, starting a family or buying a car. We’ll explore essential tips to help you make the most of personal loans while avoiding common pitfalls, what you need to know about personal loans and when they come in handy.
Fund major life events with a personal loan
Whether it be a wedding, moving into your new home, or a new baby is on the way, some of life’s most cherished moments happen in quick succession meaning it can be hard to financially recover before the next big expense comes along.
It is common for new families to rely on a sole income while children are small, adding financial pressure during a time of many new and often unpredicted expenses. If you are feeling the pinch it can be a tricky time and having limited funds can make it very difficult to make the most of life’s joys.
With careful planning and consideration, personal loans can alleviate pressure quickly allowing you to create lasting memories that bring you closer to loved ones.
Understand your needs and research lenders
1. Be realistic
Consider your specific financial situation and whether you could set a savings goal to help you achieve your goal instead.
2. Research
Shop around and select an option that suits you or your family’s needs.
3. Budget
Plan your budget carefully and consider all costs involved so you’re not caught off-guard by repayments.
Personal loans can provide financial relief, providing you borrow responsibly and only take out what you can afford to repay. Consider your monthly budget and future expenses to determine a realistic loan amount and repayment plan.
Remember, before making any decisions that could affect your family’s financial health, consult with your partner and carefully consider their input. Sit down and discuss your financial situation and make decisions together.
Live life now
We all have dreams and aspirations that inspire us and give meaning to our lives. Whether it’s hitting the open road on a motorcycle, or embarking on family adventures with the caravan in tow, personal loans can provide the means to turn these dreams into reality.
By carefully assessing your financial situation and budgeting for loan repayments, you can confidently invest in the experiences and possessions that bring you joy and fulfilment.
Red Tree Finance practices responsible lending, meaning we only approve you for a loan we know meets your requirements and that you can afford to repay.
Chat with our friendly customer care team on (02) 9044 5633 today.
Personal loan amounts generally range from as low as $1,000 to as high as $100,000. The exact range varies from lender to lender. Here at Red Tree Finance we only lend what you can comfortably repay up to $5000.
Personal loans can be used for almost any expense, including debt consolidation, home improvement projects, moving house, vet bills, holidays and emergencies.
While most reasons won’t stop you from obtaining a personal loan, you’ll need to explain why you need the money you’re borrowing, such as for a car, holiday or for personal or family needs.
The information provided in this blog is of a general nature and is provided without considering your specific objectives, financial situation, or needs. It is intended for informational purposes only and should not be relied upon as financial, investment, or other professional advice.
Before making any financial decisions or taking action based on the information presented, you are strongly encouraged to assess its appropriateness in light of your individual circumstances. Red Tree Finance does not intend to provide personalised financial advice, and you should seek independent financial, legal, tax, and other relevant advice tailored to your unique situation.
News
Other blog articles
From budgeting tips to ways to make your money go further, we’ve got it all. Get financially savvy with the Red Tree Finance blog.
We all rely on our cars to get us to and from work, the shops, or simply to get from A to B. And while regular car servicing and maintenance are important measures that keep our cars running smoothly, sometimes unexpected car troubles occur that require professional attention, leaving you with an often costly car repair bill.
Life can throw financial curveballs from many directions, whether it’s unplanned car repairs, emergency medical bills, or even a spontaneous overseas family trip. When cash is tight, many Australians turn to a personal loan to ease the pressure. It's a fixed lump sum you repay with interest over time – problem solved.
Are you looking to build up some quick cash in your account to fund your next adventure or pay off some bills? While cash loans can present as one solution, it’s entirely likely that you’re sitting on a goldmine right at home.
Managing your credit is a key part of financial health, but we’re all bound to make some mistakes along the way. So how long does bad credit last? Understanding the way your credit score works can be confusing. And whether you’re new to the world of credit or just trying to improve your credit with
Managing your credit is a key part of financial health, but we’re all bound to make some mistakes along the way. So how long does bad credit last? Understanding the way your credit score works can be confusing. And whether you’re new to the world of credit or just trying to improve your credit with a debt consolidation loan, knowing how your credit information may affect your score is essential. We’ll explain what bad credit is, and just how long you can expect it to follow you around.
What is considered “bad credit”?
Before we explore how long bad credit sticks around, or how to repair bad credit, it’s important to understand what it actually means. In Australia, your creditworthiness is demonstrated through your credit report, which showcases your credit history to potential lenders.
This information helps lenders assess whether you are a high risk for repayment or if you have a track record of good financial behaviour. The three major credit reporting agencies in Australia are Equifax, Experian, and Illion.
While each agency has their own scoring criteria, generally a score of 500 or lower is considered below average, or bad credit. A score of above 661 puts you in the good range, while anything about 853 is considered excellent. Below is a breakdown of the full credit score ranges from Australia’s major credit agencies.
Credit bureau
Excellent
Very Good
Good
Fair
Below average
Equifax
853 – 1,200
735 – 852
661 – 734
460 – 660
0 – 549
Experian
800 – 1,000
700 – 799
625 – 699
550 – 624
0 – 549
Illion
800 – 1,000
700 – 799
500 – 699
300 – 499
0 – 299
How long does a bad credit rating last?
Bad credit information may stay on your credit report for up to 5 to 7 years, depending on the type of negative event. For example, late payments typically last up to 5 years, while more severe issues like bankruptcies may remain for 7 years. However, the impact of bad credit may decrease over time, especially if you start practising good credit habits like making on-time payments and reducing debt.
Factors that can impact credit duration
Several factors may influence how long certain items remain on your credit report. These include:
The type of account or event: For instance, while inquiries into your credit (such as when you apply for a loan) may stay on your report for only two years, more serious issues like defaults can last much longer.
Your repayment behaviour: Timely repayments may help reduce the impact of negative marks on your credit over time. Conversely, late or missed payments may lead to a prolonged effect.
The credit reporting agency: Different agencies may have slightly different policies for how long they keep your data. It’s always a good idea to check your credit report with multiple agencies to ensure accuracy.
Keeping your credit in good shape
You can’t always control what happens to your credit, but you can take steps to keep it in tip-top shape! Here are some tips:
Keep old accounts open: Even if you’re not using a credit card, having a long-standing line of credit can improve your score, as it shows a history of managing credit responsibly.
Limit applications for new credit: Applying for too many loans or credit cards at once may raise red flags to lenders, as it might seem you’re overly reliant on borrowing.
Check your credit report regularly: Mistakes happen! By reviewing your report at least once a year, you can spot any errors or issues early. It’s free to check your report every three months, but if you want to do it any more frequently you may incur some fees.
Debt consolidation: If you’ve accumulated a large amount of debt, you might be eligible for a debt consolidation loan which, if you continue to pay off, can increase your credit periodically.
Will bad credit affect me if I want to get a loan?
Bad credit may affect your ability to get a loan, as lenders typically review your credit history to determine risk. However, some lenders offer small personal loans to individuals with less-than-perfect credit. While you might face higher interest rates or stricter repayment terms, you still have options. It’s important to always review the terms and ensure you can repay the loan before applying.
Stay on top of your credit score with Red Tree Finance
It’s important to stay on top of your credit history to make sure it reflects responsible borrowing and repayment. Whether you’re planning a large purchase or just trying to keep your financial options open, keeping an eye on your credit can make a big difference in the long run.
At Red Tree Finance, we offer cash loans designed to help you when you need it most. Our loan process is quick and easy, making it possible to get the funds you need, even if your credit history isn’t flawless. If you need an emergency loan to cover an unexpected bill, or a debt consolidation loan to try to improve your credit score, we can help! Apply for a loan today or contact our team for more information.
Credit information, such as late payments or defaults, may stay on your credit report for up to 5-7 years. This can depend on the type of information and the credit reporting laws in your area.
It’s a good idea to check your credit score regularly – at least once a year – to ensure everything is accurate and up-to-date. You may also want to review it before making big financial decisions like applying for a loan or credit card.
Taking out a small personal loan may help improve your credit score if you make timely payments and manage the loan responsibly. However, it’s important to only borrow what you can comfortably repay to avoid negative impacts on your credit.
The information provided in this blog is of a general nature and is provided without considering your specific objectives, financial situation, or needs. It is intended for informational purposes only and should not be relied upon as financial, investment, or other professional advice.
Before making any financial decisions or taking action based on the information presented, you are strongly encouraged to assess its appropriateness in light of your individual circumstances. Red Tree Finance does not intend to provide personalised financial advice, and you should seek independent financial, legal, tax, and other relevant advice tailored to your unique situation.
News
Other blog articles
From budgeting tips to ways to make your money go further, we’ve got it all. Get financially savvy with the Red Tree Finance blog.
We all rely on our cars to get us to and from work, the shops, or simply to get from A to B. And while regular car servicing and maintenance are important measures that keep our cars running smoothly, sometimes unexpected car troubles occur that require professional attention, leaving you with an often costly car repair bill.
Life can throw financial curveballs from many directions, whether it’s unplanned car repairs, emergency medical bills, or even a spontaneous overseas family trip. When cash is tight, many Australians turn to a personal loan to ease the pressure. It's a fixed lump sum you repay with interest over time – problem solved.
Are you looking to build up some quick cash in your account to fund your next adventure or pay off some bills? While cash loans can present as one solution, it’s entirely likely that you’re sitting on a goldmine right at home.
How to Get Approved Personal Loans & Why It Might Be Declined
Getting rejected for a personal loan can be stressful, leaving you wondering what to do next. Once you’ve been declined, the best thing to do is to take a second and breathe. It’s not good for your credit score to continuously apply if you’re getting multiple rejections. If you are unsure why your application was
Getting rejected for a personal loan can be stressful, leaving you wondering what to do next. Once you’ve been declined, the best thing to do is to take a second and breathe. It’s not good for your credit score to continuously apply if you’re getting multiple rejections.
If you are unsure why your application was rejected and need some guidance on how to get approved for personal loans, we’re put together 6 reasons you might have been declined, plus some strategies to improve your chances of being approved next time.
6 reasons why you might be getting declined for personal loans
An application for a personal loan or other credit may be declined if you don’t have enough income or insufficient savings to meet loan repayments. The number of other loans and financial commitments you have and your employment security will also impact your application outcome.
These are the six most common reasons that you might be declined for personal loans and what you can do to secure a loan approval next time you apply.
1. A poor credit score
When you apply for a personal loan, the lender must check your credit report and determine the risk of you not meeting your repayments. This is a requirement for responsible lending.
The three main credit reporting bodies in Australia, Equifax, Experian, and Illion, have their own scales to calculate your credit score. You can check your score for free every three months, which might be helpful if you’ve been declined for a personal loan. Getting a copy of your credit report is a great first step to understanding where you’re at and what to do first to improve your position.
Your credit report contains information like previous credit applications, missed payments on loans or utilities, and when you change your address. Addressing problems in your credit report can help you lower your credit score and get approved for your next personal loan.
2. High debt-to-income ratio
When you go for a personal loan, the lender will consider how much existing debt you have, how the additional loan will impact your overall debt, and your ability to meet the monthly repayments. The amount of money you earn per month compared to the amount of debt you owe each month is known as the debt-to-income ratio (DTI).
For example, take someone who earns $70,000 a year and has a car loan of $15,000 and a personal loan of $5,000. When you divide their total income (70,000) by the amount of total debt (20,000), you would get a debt-to-income ratio of 3.5.
A high debt-to-income ratio indicates that you have large total debt repayments compared to your monthly income, which may signal a higher risk to lenders that you will miss a payment. On the other hand, a lower debt-to-income ratio means that you have a lower amount of existing debt, improving your chances of getting approved for a personal loan.
If you have been declined for a personal loan, consider the amount of debt you have compared to your monthly income. You might put a strategy in place to pay off the smallest debt quickly, or close lines of credit, including overdraft, consumer credit, and credit cards.
Another option is to consolidate debts into one loan so that you only have one repayment to worry about. This makes it easier to pay down the debt quickly. It’s also a great way to improve your credit score.
3. Employment status
As part of the application process, the lender will ask you for your current working history and the employer’s details. Gathering this information allows the lender to create a risk assessment to determine if your loan request will be approved.
These details verify your current employment status and also provide income information. Lenders will look at details such as monthly income, duration of employment, and your employment status (casual, part-time, or full-time).
You may be declined for a loan if:
You have only been employed for a short period (under 3 months or six months, depending on the lender’s policy)
You don’t earn enough to service the loan repayments
You may not meet the eligibility criteria if you are on a casual or low-hours part-time contract
4. Lender eligibility requirements
When you apply for a personal loan, it is important to understand the eligibility requirements. These requirements may vary between lenders, however, all lenders must follow responsible lending practices.
Eligibility criteria may include owning an unencumbered vehicle, having a particular surplus income to service the loan, spending habits, or the number of additional loans or lines of credit you currently hold.
Non-bank lenders may have different criteria for personal loans than banks. If you have been declined by a bank, a non-bank lender may still be able to help you get approved for a personal loan.
5. Open lines of credit
An open line of credit is counted as a debt when the lender assesses your debt-to-income ratio. Lines of credit include credit cards, overdrafts, and “buy now, pay later” services that provide consumer credit.
While using these types of services can help with your weekly or monthly cash flow, it’s important to use them responsibly. This means making sure you can pay off the balance or meet the payments when they are due. Missed payments can negatively impact your credit score, just like a missed loan repayment can.
If you have been declined for a personal loan, you may want to close any of these services that you can, or reduce the balance owing.
6. Gambling
When applying for a personal loan, lenders will ask for bank statements showing all transactions for the last 3 months. If you have excessive gambling debits on your statement, this may raise a red flag for the lender. Gambling can be addictive and it can easily consume funds that should be for bills or loan repayments.
If you do have gambling transactions on your card, make an effort to avoid these for three months before applying for a loan. It’s also best to set yourself a strict budget and stick to it in the future. That way you can place a bet on your favourite team without blowing up your bank account.
If you need help with gambling, reach out to the Gambling Help Line for support.
Tips on how to get approved for a personal loan
The best strategy to improve your chances of approval will depend on your personal circumstances. If you’ve been declined for a personal loan, try reaching out to the lender to find out the reason why. Once you know that, you can choose the strategy that will improve your chances of being approved next time.
Work towards a full-time position if you’re part-time or casual.
Reduce discretionary spending and pay off consumer credit balances, like “buy now pay later” and credit cards.
Limit the amount of gambling you do. Small infrequent bets are fine, but routine or big gambles will impact your chances of approval. Seek help and support if you need some guidance on changing your habits.
Consolidating your debt can help you pay it off faster and decrease your chances of missing a repayment. It also shows that you’re serious about tackling debt in a timely manner.
Pay your bills on time to show consistency and prove you can manage your finances. Utility bills can also impact your credit score, so if you are struggling to meet a bill deadline, reach out and ask about financial hardship options.
Create a budget and allocate additional funds to pay off your existing debts.
Been declined by the banks? Red Tree Finance might be able to help
Now you have an understanding of why you could have been declined for a personal loan, you can make changes to increase your chances of approval.
Most banks have stricter lending requirements, so if you’ve been denied by them, the team at Red Tree Finance might be able to help. If you are looking to reapply for a personal loan, contact us for more information or apply for an online loan today!
If your loan keeps getting declined, consider whether your credit score is low or if you have too many debts that need to be paid. Pay these bills off first, then you may increase your chances of getting approved.
Many different factors could affect your loan being approved like:
The lender’s eligibility requirements
Low credit score
High debt-to-income ratio
Credit card usage
Excessive gambling
Employment status and history
Applying for any type of finance, including a personal loan or credit card, can affect your credit score as the lender will need to do a hard credit check. This causes a small dip in your score, which usually returns to normal over time. However, being rejected for a personal loan will not affect your credit score.
The information provided in this blog is of a general nature and is provided without considering your specific objectives, financial situation, or needs. It is intended for informational purposes only and should not be relied upon as financial, investment, or other professional advice.
Before making any financial decisions or taking action based on the information presented, you are strongly encouraged to assess its appropriateness in light of your individual circumstances. Red Tree Finance does not intend to provide personalised financial advice, and you should seek independent financial, legal, tax, and other relevant advice tailored to your unique situation.
News
Other blog articles
From budgeting tips to ways to make your money go further, we’ve got it all. Get financially savvy with the Red Tree Finance blog.
We all rely on our cars to get us to and from work, the shops, or simply to get from A to B. And while regular car servicing and maintenance are important measures that keep our cars running smoothly, sometimes unexpected car troubles occur that require professional attention, leaving you with an often costly car repair bill.
Life can throw financial curveballs from many directions, whether it’s unplanned car repairs, emergency medical bills, or even a spontaneous overseas family trip. When cash is tight, many Australians turn to a personal loan to ease the pressure. It's a fixed lump sum you repay with interest over time – problem solved.
Are you looking to build up some quick cash in your account to fund your next adventure or pay off some bills? While cash loans can present as one solution, it’s entirely likely that you’re sitting on a goldmine right at home.
How Much Does the Average Renovation Cost in Australia?
With house prices always on the rise, more Aussie buyers are turning to fixer-uppers to get a foot in the property market. Renovating an older home can make it a much more inviting place to live, as well as increase its value if you sell in the future. But what style do you go for?
With house prices always on the rise, more Aussie buyers are turning to fixer-uppers to get a foot in the property market. Renovating an older home can make it a much more inviting place to live, as well as increase its value if you sell in the future. But what style do you go for? Which room do you start with? And, the biggest question of all, how much is the average renovation cost in Australia?
Whether you’re hiring professionals or taking the DIY approach, renovations can be expensive. A personal loan can provide the financial boost you need to get started, but you’ll need to have a plan to avoid overspending. In this guide, we’ll break down the average renovation cost in Australia and explore expenses room by room to help you plan your budget effectively.
The average cost to renovate a house in Australia
In Australia, the average cost to renovate your entire house ranges between $20,000 (for a small unit) to $500,000 (for very large homes). But don’t be too scared by the big numbers. According to data from Suncorp Bank, homeowners are borrowing an average of $63,188 to fund their projects.
This pricing drastically varies because of:
The square meterage of your home: The bigger your home, the more it will cost
The quality of materials: Paint, tiles, insulation, drywall, gyprock, cornices, new appliances, and skirting boards.
The scope of your renovation: changing tiles, painting the walls, or a full knockdown renovation.
Paying a professional vs DIY renovations: Cost of labour and materials.
New vs old appliances: The cost of brand new top of the line appliances can quickly blow out your budget.
How to create a budget for your renovations
Creating a budget is essential for managing your renovation costs, helping you plan how much to allocate for each room and track your expenses throughout the project.
To create a budget, you’ll need to have a solid plan in mind. Head to Pinterest, or ask your friends and family for inspiration. Once you’ve got an idea of what you want your home to look like, you can start adding up how much it’ll cost. Remember to stay open to change along the way, because no renovation ever goes exactly as planned.
Below, we’ve outlined the expected costs for each room to give you a clearer idea of what to budget for.
Renovating budgets room-by-room
According to the experienced team at Renovation Junkies, the most renovated rooms in the house are the kitchen and bathroom. As well as having the most potential to be damaged or look outdated, they’re also the most valued areas to potential home buyers. But as you’ll see below, they’re also the most difficult and expensive to renovate, given the many different trades involved.
Average cost of renovating a lounge room
The lounge room is the communal space in the house where memories are shared and visitors are usually entertained. Refreshing this space is important to make your guests feel more comfortable.
The average cost of renovating a lounge room can range between $7,000-$15,000. These costs include:
Painting the walls
Replacing the floors
Removing walls to make it open-plan
Adding more powerpoints or aerial points
Installing floating shelves or cabinetry on the wall
New curtains or shutters
Average cost of renovating a bedroom
Your bedroom is a safe haven, and adding those special touches to make it feel truly yours can make all the difference. The perfect walk-in robe or an added ensuite can all make you feel more comfortable, as well as add value to your home if you’re looking to sell.
Bedrooms are usually smaller than the rest of the house, so a new floor and a fresh coat of paint can cost as little as $2000. But if you’re planning for walk-in robes or an upgraded ensuite, you could be looking at costs between $15,000-$30,000.
There are many different upgrades and changes that you can do to renovate your bedroom, such as:
Knocking down walls to build an ensuite and walk-in robe
Built-in cabinetry and a make-up station
Add a double shower or sink
Upgrade the toilet
Change the flooring
Add new lighting or a ceiling fan
Average cost of renovating a bathroom
Between all the new tiles and fixtures, as well as specialised trades like plumbers and waterproofers, bathrooms become notoriously costly to renovate. But cutting corners here could lead to much more expensive problems down the line, so it’s always best to consult the professionals.
Depending on what you’re looking to change, a bathroom renovation can cost anywhere between $1,000-$35,000. This is also dependent on whether you’re upgrading an ensuite, main bathroom, or both.
Some bathroom renovation costs include:
Adding a double basin
Upgrading the toilets
Adding floor-to-ceiling tiles
Changing the shower to a double shower
Replacing the light and exhaust fan system
Adding new mirrors with LED lights
Average cost of renovating a kitchen
They don’t call kitchens the heart of the home for nothing. Between late-for-work breakfasts and after school snacks, your whole family flows in and out of the kitchen. And if you’re looking to spruce it up, it’s likely a good chunk of your budget will flow into it too.
There are plenty of costs and design questions to consider, which is why a kitchen renovation typically ranges from $30,000 to $50,000.
Some renovation ideas to consider include:
Creating a walk-in pantry
New appliances like a fridge, freezer, oven, stove top, and dishwasher
Adding a dual sink and stone benchtops
Replacing the flooring
Building floating cabinetry
Installing downlights
Adding a kitchen island and breakfast bar
Average cost of backyard improvements
A report by Houzz and Home Australia found 57% of Australians were including outdoor areas in their renovation plans. Some landscaping or backyard improvements can help tie everything together, making the outside of your home just as appealing as the inside. The average cost of renovating your backyard is between $12,500-$44,500.
Of course, your outside plans will vary drastically depending on how much space you have available. Some new plants and a refresh of the garden soil won’t set you back much and can still make a huge difference to the feel of your backyard. If you have room, adding a shed or installing a pool can be fantastic outdoor improvements.
Here are some other projects you can do to renovate your backyard:
Build an outdoor pergola or alfresco area
Add a deck and outdoor kitchen
Create garden beds or vegetable gardens
Build an outdoor granny flat or activities room
Add a firepit
Get help funding your renovation project from Red Tree Finance!
A home renovation should be a fun experience that adds value to your home. Now that you how much the average renovation costs in Australia, try to budget effectively and plan out your home renovation within your means. But if you fall just short of your budget, Red Tree Finance can help! We offer same-day loans to make sure you don’t have to compromise your vision. For any more information or any enquiries, feel free to reach out and contact our expert team today.
The average home renovation costs between $20,000-$500,000 and an estimated $1,500-$3,500 per square meter of your home. If you want to change the physical structure of the home or add rooms to your house, then the costs are significantly higher.
The most expensive home renovations are kitchen and bathroom upgrades. That’s because these rooms require more high-quality materials and specialised trades than other areas of the home.
In Australia, a full kitchen renovation costs between $20,000 and $50,000. These costs depend on the size of your kitchen, what you want to add, the quality of material you use and the new appliances you add.
The information provided in this blog is of a general nature and is provided without considering your specific objectives, financial situation, or needs. It is intended for informational purposes only and should not be relied upon as financial, investment, or other professional advice.
Before making any financial decisions or taking action based on the information presented, you are strongly encouraged to assess its appropriateness in light of your individual circumstances. Red Tree Finance does not intend to provide personalised financial advice, and you should seek independent financial, legal, tax, and other relevant advice tailored to your unique situation.
News
Other blog articles
From budgeting tips to ways to make your money go further, we’ve got it all. Get financially savvy with the Red Tree Finance blog.
We all rely on our cars to get us to and from work, the shops, or simply to get from A to B. And while regular car servicing and maintenance are important measures that keep our cars running smoothly, sometimes unexpected car troubles occur that require professional attention, leaving you with an often costly car repair bill.
Life can throw financial curveballs from many directions, whether it’s unplanned car repairs, emergency medical bills, or even a spontaneous overseas family trip. When cash is tight, many Australians turn to a personal loan to ease the pressure. It's a fixed lump sum you repay with interest over time – problem solved.
Are you looking to build up some quick cash in your account to fund your next adventure or pay off some bills? While cash loans can present as one solution, it’s entirely likely that you’re sitting on a goldmine right at home.
Easter is a time for joy, celebration, and of course, delighting the little ones. While chocolate eggs are a classic, there are plenty of other creative options to consider that are an affordable way to give gifts in the holidays that are a little kinder on the household budget. From DIY craft ideas to Easter
Easter is a time for joy, celebration, and of course, delighting the little ones. While chocolate eggs are a classic, there are plenty of other creative options to consider that are an affordable way to give gifts in the holidays that are a little kinder on the household budget. From DIY craft ideas to Easter egg hunting with a twist, here are some Easter gift ideas sure to bring smiles to children’s faces.
Creative Easter Craft
With Christmas wrapped up, Easter is now upon us bringing with it public holidays and long weekends to enjoy as a family. Why not get creative this year and go beyond the traditional chocolate treats and surprise the kids with thoughtful and creative gifts that inspire imagination, exploration, and joy.
Many of the more traditional forms of celebrating Easter are also more affordable for those of us on single or low incomes and about the process of creating rather than the end product.
Focus on re-using and keeping it simple – op-shops are a great resource for craft materials on a budget, you will find all sorts of things like bunting, and hats to re-use for school Easter hat parades and even little wicker baskets for Easter egg hunting.
DIY Easter Gift Ideas
Egg decorating
To dye eggs the traditional way, begin by hard-boiling a dozen or so eggs and allowing them to cool completely. Next, prepare several cups of boiling water and add a teaspoon of vinegar to each cup, which helps the dye adhere to the eggs.
Choose a variety of vibrant food colouring dyes and add them to the cups of water, creating a rainbow of colours. Carefully lower the eggs into the dye baths, using a spoon or tongs to ensure even coverage. Let the eggs soak until they reach the desired hue, periodically checking their colour.
Once dyed, remove the eggs from the dye baths and allow them to dry. Decorate further with textas or ribbon and for a glossy finish, rub vegetable oil onto the eggs. This traditional method of Easter egg dyeing results in beautifully coloured eggs that are perfect for hiding, displaying traditionally by hanging on trees, or enjoying as a festive snack.
Homemade Easter bunny masks
Craft simple bunny masks using paper plates, construction paper, and elastic bands. Kids can decorate them with textas and glitter for a fun Easter activity.
Easter-themed craft
Provide materials for Easter-themed craft activities; like making pom-pom chicks, tissue paper flowers, or bunny ears headbands. These hands-on activities will keep kids entertained much longer than a soft toy would and also foster their creativity.
DIY paper Easter baskets
To create your own paper basket, use paper in vibrant Easter colours. Cut the paper into strips and weave them together to form the base of the basket, securing the ends with glue or tape. Then, craft a handle using additional paper strips or ribbon, attaching it securely to the sides of the basket. Decorate your creation with stickers, textas, or ribbon bows and paper flowers.
A little holiday help
As the cost of living affects many families Australia-wide, added pressure can be felt during holiday periods. Holiday loans can alleviate the pressure to allow you to access money quickly.
We’re here to help with your questions and concerns. Talk with our customer care team and loan experts today.
Although chocolate is a popular gift for Easter, sugary sweets don’t have to be the only option for your kids. Outside of chocolate (or in addition to it, if you choose) consider handmade gifts and craft activities that can be enjoyed as a family.
A traditional German tradition that takes place on Easter Sunday: First thing in the morning after waking up, children go hunting for Easter eggs (brightly painted, hard-boiled eggs) that the Easter bunny has hidden for them – in the home or in the garden. The one who finds the most Easter eggs wins!
With Australian families spending in excess of $150 on Easter Easter food and chocolates, this year why not opt for traditional crafts and homemade options? Save the cash, get creative and enjoy time spent with family.
The information provided in this blog is of a general nature and is provided without considering your specific objectives, financial situation, or needs. It is intended for informational purposes only and should not be relied upon as financial, investment, or other professional advice.
Before making any financial decisions or taking action based on the information presented, you are strongly encouraged to assess its appropriateness in light of your individual circumstances. Red Tree Finance does not intend to provide personalised financial advice, and you should seek independent financial, legal, tax, and other relevant advice tailored to your unique situation.
News
Other blog articles
From budgeting tips to ways to make your money go further, we’ve got it all. Get financially savvy with the Red Tree Finance blog.
We all rely on our cars to get us to and from work, the shops, or simply to get from A to B. And while regular car servicing and maintenance are important measures that keep our cars running smoothly, sometimes unexpected car troubles occur that require professional attention, leaving you with an often costly car repair bill.
Life can throw financial curveballs from many directions, whether it’s unplanned car repairs, emergency medical bills, or even a spontaneous overseas family trip. When cash is tight, many Australians turn to a personal loan to ease the pressure. It's a fixed lump sum you repay with interest over time – problem solved.
Are you looking to build up some quick cash in your account to fund your next adventure or pay off some bills? While cash loans can present as one solution, it’s entirely likely that you’re sitting on a goldmine right at home.
When life throws a curveball (or two), a personal loan might be the quickest way to get cash fast. But when multiple emergencies happen at once, those loans can spiral out of control until it feels like you’re drowning in debt. If paying off debt is a priority for you this year, a debt consolidation
When life throws a curveball (or two), a personal loan might be the quickest way to get cash fast. But when multiple emergencies happen at once, those loans can spiral out of control until it feels like you’re drowning in debt. If paying off debt is a priority for you this year, a debt consolidation loan can help you do it. But it’s not the only way, so we’ll guide you through how to reduce debt and pay off large amounts fast.
Balance your finances
Create a budget
No matter how you got into debt, the main thing is to take stock of where you are right now and make a plan to pay down the money you owe. The first step is to create a detailed budget, taking into account your income and expenses. Your budget should include:
With your income and expenditure written down, you can easily see how much money you have left over to put towards your debt repayments. You can even see if there are unnecessary expenses you can cut back so you have more to put towards your outstanding loans.
Build an emergency fund
You might want to pay off your debts as fast as possible, but it’s just as important to build an emergency fund. If you don’t have any savings, the next unexpected expense that comes up might have you scrambling for another loan, which could make your debt problem even worse.
Your goal should be to set aside three to six months worth of expenses to cover emergencies, but you can start small. Even putting aside $50 will give you something to fall back on.
To give yourself a headstart, you could look around your home for unused or unwanted items and sell them for money.
Debt management strategies
There are several debt management strategies that can help you repay your loan faster and reduce the total interest paid, ultimately saving you money. Choose the one that suits you best, and start working towards reducing how much you owe.
1. Debt Snowball
The debt snowball strategy focuses on paying off your debts, from the smallest (typically highest interest) to the largest (lower interest). Once your smaller loan is paid off, the repayments that you would have to pay on those loans can now be used on the next smallest loan to repay it quicker. As you continue to pay off your smaller loans, you’ll have more funds available to put towards the others.
An example of the debt snowball strategy:
For this example, assume you had the following debts:
Loan 1: $500 (42% interest p.a)
Loan 2: $1000 (38% interest p.a)
Loan 3: $1500 (30% interest p.a)
Loan 4: $2500 (20% interest p.a)
And your weekly repayment cycle looks like this:
$20 per week to repay Loan 1
$40 per week to repay Loan 2
$60 per week to repay Loan 3
$100 per week to repay Loan 4
By paying extra money per week to pay off Loan 1, then you’ll have an extra $20 to put towards the next biggest loan. Then once the next biggest loan is repaid, you will have an extra $40 from Loan 2 plus the $20 from Loan 1 to put towards the next biggest loan.
2. Frequency of Repayments
To help you get ahead of your repayments, you should look to pay more than your minimum repayments. For example, if you have a repayment of $250 per week, and you can afford to repay $350, then you would reduce the amount of time taken to repay that loan. By making extra repayments you will also reduce the amount of total interest you will pay.
Find out more about when your loan interest rate is calculated. If the interest fees are calculated daily on the outstanding balance, then by repaying extra money towards your loan before your repayment cycle, you will be able to reduce the amount of interest you pay.
An example of how earlier repayments save you money
In this example, assume you had a debt of:
Loan amount: $25,000
Interest rate: 10% p.a
Standard weekly repayment: $250
Loan term: 1 year
Repayments per week
Amount of interest paid
Time taken to repay loan
$250
$1,328
12 months (52 weeks)
$350
$960
9 months (38 weeks)
$450
$775
7 months (31 weeks)
$550
$660
6 months (26 weeks)/td>
As you can see, the more money you can afford to repay per week will not only reduce the time taken to repay the loan, but also the total interest paid.
3. Debt Consolidation
A very popular way to repay your debts fast is to get a debt consolidation loan. This loan combines multiple smaller loans into one loan with one repayment cycle. When you consider a debt consolidation loan, it’s important to check that it will reduce the amount of interest you pay over that time.
An example of debt consolidation:
Let’s use the same example we used earlier in the debt snowball section:
Loan 1: $500 (42% interest p.a)
Loan 2: $1000 (38% interest p.a)
Loan 3: $1500 (30% interest p.a)
Loan 4: $2500 (20% interest p.a)
The total interest paid over 1 year is $1540.
If there was a debt consolidation loan being offered at 25% interest per annum, and you combined your total debt of $5,500 into one loan, then you’d end up paying $1375 – saving you $165 every year!
To take out a debt consolidation loan whilst having multiple smaller loans, you may need to have a good credit score. If you don’t have a good credit score because of your loans, you could consider a secured loan, which may require an asset like a car as collateral.
Take Control Of Your Finances With Red Tree Finance
Reducing your debt takes time and patience, but with the right mindset and consistency, you’ll be on your way to debt-free living. Whether you need help with creating a budget or are looking for a debt consolidation loan, the expert team at Red Tree Finance can help! For more information or if you have any questions, don’t hesitate to contact us today.
If you have $30,000 in debt and need to repay this amount in one year, then you will need to allocate a minimum of $577 per week + interest. Some strategies to help you pay it off quicker include:
The information provided in this blog is of a general nature and is provided without considering your specific objectives, financial situation, or needs. It is intended for informational purposes only and should not be relied upon as financial, investment, or other professional advice.
Before making any financial decisions or taking action based on the information presented, you are strongly encouraged to assess its appropriateness in light of your individual circumstances. Red Tree Finance does not intend to provide personalised financial advice, and you should seek independent financial, legal, tax, and other relevant advice tailored to your unique situation.
News
Other blog articles
From budgeting tips to ways to make your money go further, we’ve got it all. Get financially savvy with the Red Tree Finance blog.
We all rely on our cars to get us to and from work, the shops, or simply to get from A to B. And while regular car servicing and maintenance are important measures that keep our cars running smoothly, sometimes unexpected car troubles occur that require professional attention, leaving you with an often costly car repair bill.
Life can throw financial curveballs from many directions, whether it’s unplanned car repairs, emergency medical bills, or even a spontaneous overseas family trip. When cash is tight, many Australians turn to a personal loan to ease the pressure. It's a fixed lump sum you repay with interest over time – problem solved.
Are you looking to build up some quick cash in your account to fund your next adventure or pay off some bills? While cash loans can present as one solution, it’s entirely likely that you’re sitting on a goldmine right at home.
Having a financial safety net in place can provide much-needed peace of mind during uncertain times. But you might be wondering how much do you need for an emergency fund? At Red Tree Finance, we understand the importance of being prepared for the unexpected, so we’ve put together a guide to help you learn how
Having a financial safety net in place can provide much-needed peace of mind during uncertain times. But you might be wondering how much do you need for an emergency fund? At Red Tree Finance, we understand the importance of being prepared for the unexpected, so we’ve put together a guide to help you learn how to build and manage them, and how much you need for your own.
What is an emergency fund?
In life, unexpected financial emergencies can strike at any moment. Whether it’s medical bills, car repairs, or sudden unemployment, it’s important to make sure you have a financial buffer for when the worst happens. An emergency fund is a dedicated savings account specifically designed to cover you when unexpected expenses or financial emergencies crop up.
Unlike other savings goals, such as holidays or home renovations, the primary purpose of an emergency fund is to provide financial stability and security during unforeseen circumstances. It serves as a financial cushion, offering protection against the unexpected and helping you avoid falling into debt.
How much do I need in an emergency fund?
Determining the appropriate amount for your fund depends on various factors, including your monthly household expenses, financial obligations, and individual circumstances.
As a general rule of thumb, financial experts often recommend saving 3 to 6 months worth of living expenses. This buffer can help cover essential costs in the event of a sudden financial setback, providing a cushion to navigate through challenging times.
But building a safety net doesn’t happen overnight, so don’t worry if you’re not quite there yet. Every little bit counts, and even saving $20 a week for a year will turn into $1000 – which is a great start to any fund. Moneysmart have some tips on saving for an emergency fund, like automating your savings and maximising your offset account if you have a home loan.
Where should you put the money for an emergency fund?
When it comes to storing your emergency fund, accessibility are key considerations. Opt for accounts that offer easy access to your funds, such as a high-interest savings account. These accounts typically offer higher interest rates than traditional savings accounts while still allowing you to withdraw funds quickly and without penalties when needed.
If you have a mortgage with a redraw function or offset account, this is another great option as you can save interest on your mortgage while still having easy access to your funds.
How do I manage an emergency fund?
Building your safety net involves committing to regular contributions, periodic reassessments, and disciplined financial habits. Set up automatic transfers each pay period to ensure consistent savings growth. Periodically review your fund’s balance and adjust your savings goals as needed to account for changes in expenses or income.
Additionally, resist the temptation to dip into your savings for non-essential expenses, reserving it exclusively for true emergencies.
When is the right time to use my emergency fund?
Knowing when to tap into your fund requires careful consideration and judgement. Reserve it for genuine emergencies, such as unexpected medical expenses, major vet bills, or sudden job loss.
Before accessing your emergency fund, explore alternative options like selling items and consider the urgency and necessity of the expense. Remember, rebuilding your emergency fund should be a top priority after dipping in so you’re prepared for future unexpected challenges.
Emergency loans with Red Tree Finance
In times of financial uncertainty, having a healthy emergency fund can provide the peace of mind and security you need. At Red Tree Finance, we understand the importance of financial preparedness. If you find yourself facing unexpected expenses beyond what your savings can cover, remember that we offer small personal loans of up to $5000 to help you bridge the gap during challenging times. Apply today or contact us for more information.
Calculate how much you spend in a month and aim to accumulate 3 to 6 months’ worth of your expenses.
You should review your savings goal at least once a year, or whenever significant changes occur in your financial situation, such as a change in income, expenses, or family circumstances. Adjust your savings target accordingly to ensure you can cover unforeseen expenses.
While reducing debt is important for long-term financial health, using your savings to pay off high-interest debt may leave you vulnerable in the event of an unexpected expense. Focus on building a separate emergency fund while concurrently working towards paying off high-interest debt. By maintaining a balance between debt repayment and emergency savings, you can achieve financial stability without sacrificing your safety net.
The information provided in this blog is of a general nature and is provided without considering your specific objectives, financial situation, or needs. It is intended for informational purposes only and should not be relied upon as financial, investment, or other professional advice.
Before making any financial decisions or taking action based on the information presented, you are strongly encouraged to assess its appropriateness in light of your individual circumstances. Red Tree Finance does not intend to provide personalised financial advice, and you should seek independent financial, legal, tax, and other relevant advice tailored to your unique situation.
News
Other blog articles
From budgeting tips to ways to make your money go further, we’ve got it all. Get financially savvy with the Red Tree Finance blog.
We all rely on our cars to get us to and from work, the shops, or simply to get from A to B. And while regular car servicing and maintenance are important measures that keep our cars running smoothly, sometimes unexpected car troubles occur that require professional attention, leaving you with an often costly car repair bill.
Life can throw financial curveballs from many directions, whether it’s unplanned car repairs, emergency medical bills, or even a spontaneous overseas family trip. When cash is tight, many Australians turn to a personal loan to ease the pressure. It's a fixed lump sum you repay with interest over time – problem solved.
Are you looking to build up some quick cash in your account to fund your next adventure or pay off some bills? While cash loans can present as one solution, it’s entirely likely that you’re sitting on a goldmine right at home.
What to Do in a Cash Emergency: 6 Smart Ways to Stay Afloat
Life has a way of throwing a financial spanner in the works when you least expect it. A medical bill, an urgent car repair, or rent due before payday, all of which can cause stress. That’s when it helps to know what to do in a cash emergency.
Life has a way of throwing a financial spanner in the works when you least expect it. A medical bill, an urgent car repair, or rent due before payday, all of which can cause stress. That’s when it helps to know what to do in a cash emergency.
What Counts as a Cash Emergency?
A cash emergency is any situation where you need money immediately to cover essential costs. It might be overdue rent, bills, groceries, medical expenses, or urgent repairs such as fixing your car. And sometimes it’s a combination of all of these expenses that can unfortunately pile up when you least expect them.
The important thing is to recognise the situation quickly so you can act before it leads to bigger problems down the track.
Focus on items that hold value but no longer serve a purpose for you. Popular options include branded clothing, small appliances, and sporting equipment tend to sell quickly online and can give you cash in hand within a day or two.
Take a look around your home; if you’ve got anything from bikes, tools, electronics, furniture, or clothing, they can all fetch quick cash through online marketplaces or a weekend garage sale. It clears space and gives you immediate funds to cover essentials.
2. Pick up Extra Work
If you have time, skills, or even just a mower in the shed, use these to earn extra money quickly. People are always on the hunt for help with gardening, cleaning, pet care or odd jobs.
Start with the skills or tools you already have. Whether it’s babysitting, tutoring, mowing lawns, or fixing things around the house, simple services can bring in fast cash without upfront costs. Even just a few hours during the week can add up.
Advertise your services on local community boards, social media, or knock on doors around your local area. A day or two of extra work can put much-needed cash in your pocket.
3. Borrow From Family or Friends
If it’s an option, borrowing from family or friends can help you get through a tight spot without interest. To keep things fair and clear, agree on how much you’ll borrow, repayment terms and a timeframe.
Before you ask, think about what you can reasonably commit to repaying and how soon you can pay it back. Being upfront shows respect and helps set the right expectations. This makes the conversation easier and builds trust from the start.
Write everything down so you all have a plan to follow. A simple agreement between family members avoids confusion and protects your relationship.
4. Contact a Financial Counsellor
Sometimes the best step in a cash emergency is to get professional guidance. Free services such as the National Debt Helpline can help you understand your options, negotiate with providers, and connect you with hardship programs. An expert in your corner can give you the confidence to help you out of a difficult situation.
5. Cut Back Temporarily
If you’re on a low income or when money is tight, trimming expenses can make more room in your budget. Cook at home instead of ordering takeaway, pause subscriptions you don’t use, delay non-essential purchases, or skip nights out. These small changes may seem minor, but together they can free up enough money to cover urgent bills and reduce stress.
6. Consider an Emergency Loan
If other options aren’t enough, an emergency loan can provide the funds you need. With Red Tree, you can apply online in minutes and access up to $5000 using your car as security. Once approved, funds are released quickly, giving you a straightforward way to cover urgent costs and stay in control.
An emergency loan can cover:
Urgent home or car repairs
Vet or medical expenses
Replacement of essential appliances
Rental bonds or emergency flights
Plan to Avoid Future Emergencies
You can’t plan for every setback, but you can prepare for the unexpected with an emergency fund. It allows you to keep a simple budget while building your savings at the same time. And when you have a plan in place, it makes it easier to adjust to rising costs. It’s also important to stay on top of your bills and compare providers for the best deals so you can free up cash to set aside.
These habits give you more choice when the next cash emergency comes along. Instead of scrambling, you’ll already have an emergency plan in place.
A cash emergency doesn’t have to derail your life. Red Tree makes it simple to access secured personal loans up to $5000. With a fast online application and straightforward terms, you’ll know where you stand in minutes.
Apply online today or talk with our customer service team about an option that works best for you. Taking action now means you can cover urgent expenses and focus on what matters most.
If you need urgent money in Australia, there are several options. Community programs such as the No Interest Loan Scheme (NILS) can help with essentials. Some charities and local councils also provide short-term relief for bills or food. If you need funds quickly and meet eligibility requirements, lenders like Red Tree Finance offer emergency loans of $2,350 to $5,000 with same-day outcomes when secured against an unencumbered vehicle.
The 3-6-9 rule is a guideline for building financial security. It suggests you save:
3 months of expenses if you’re single or renting.
6 months if you have a family or a mortgage.
9 months if you’re self-employed or have irregular income.
Following this rule helps you prepare for unexpected costs like job loss, medical bills, or urgent repairs. Even small, regular savings can build toward this goal over time…
To raise emergency cash, start with immediate actions: sell unused items, take on quick extra work, or cut non-essential spending to free up funds. If that’s not enough, look into community relief programs or hardship options with your providers. For fast access to larger amounts, an emergency loan from Red Tree lets you borrow up to $5,000 using your car as security, with applications completed online and funds released quickly once approved.
The information provided in this blog is of a general nature and is provided without considering your specific objectives, financial situation, or needs. It is intended for informational purposes only and should not be relied upon as financial, investment, or other professional advice.
Before making any financial decisions or taking action based on the information presented, you are strongly encouraged to assess its appropriateness in light of your individual circumstances. Red Tree Finance does not intend to provide personalised financial advice, and you should seek independent financial, legal, tax, and other relevant advice tailored to your unique situation.
News
Other blog articles
From budgeting tips to ways to make your money go further, we’ve got it all. Get financially savvy with the Red Tree Finance blog.
We all rely on our cars to get us to and from work, the shops, or simply to get from A to B. And while regular car servicing and maintenance are important measures that keep our cars running smoothly, sometimes unexpected car troubles occur that require professional attention, leaving you with an often costly car repair bill.
Life can throw financial curveballs from many directions, whether it’s unplanned car repairs, emergency medical bills, or even a spontaneous overseas family trip. When cash is tight, many Australians turn to a personal loan to ease the pressure. It's a fixed lump sum you repay with interest over time – problem solved.
Are you looking to build up some quick cash in your account to fund your next adventure or pay off some bills? While cash loans can present as one solution, it’s entirely likely that you’re sitting on a goldmine right at home.
Sydney might have a reputation for being expensive, but you can enjoy plenty of incredible experiences without breaking the bank. From iconic landmarks to hidden gems, here are 20 cheap things to do in Sydney – for under $30!
Sydney might have a reputation for being expensive, but you can enjoy plenty of incredible experiences without breaking the bank. From iconic landmarks to hidden gems, here are 20 cheap things to do in Sydney – for under $30!
1. Visit the Sydney Opera House Forecourt
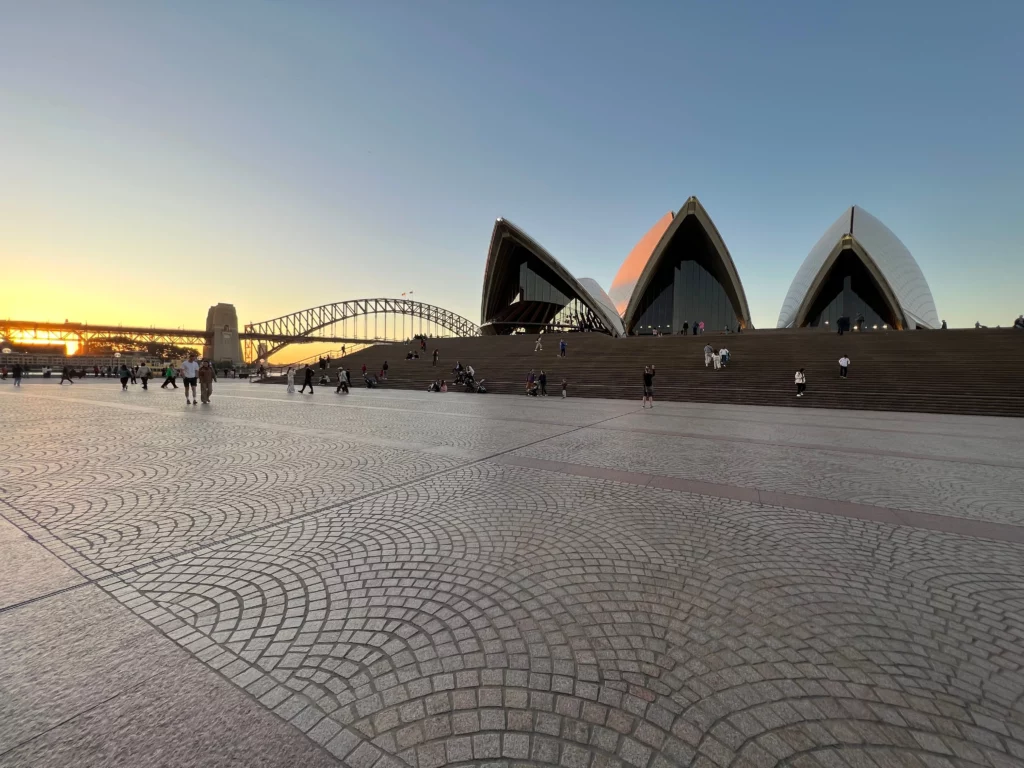
While tours inside the Sydney Opera House can be expensive, exploring the forecourt and taking photos of this architectural marvel is completely free. Time your visit during sunset for the most dramatic shots.
2. Walk Across the Sydney Harbour Bridge
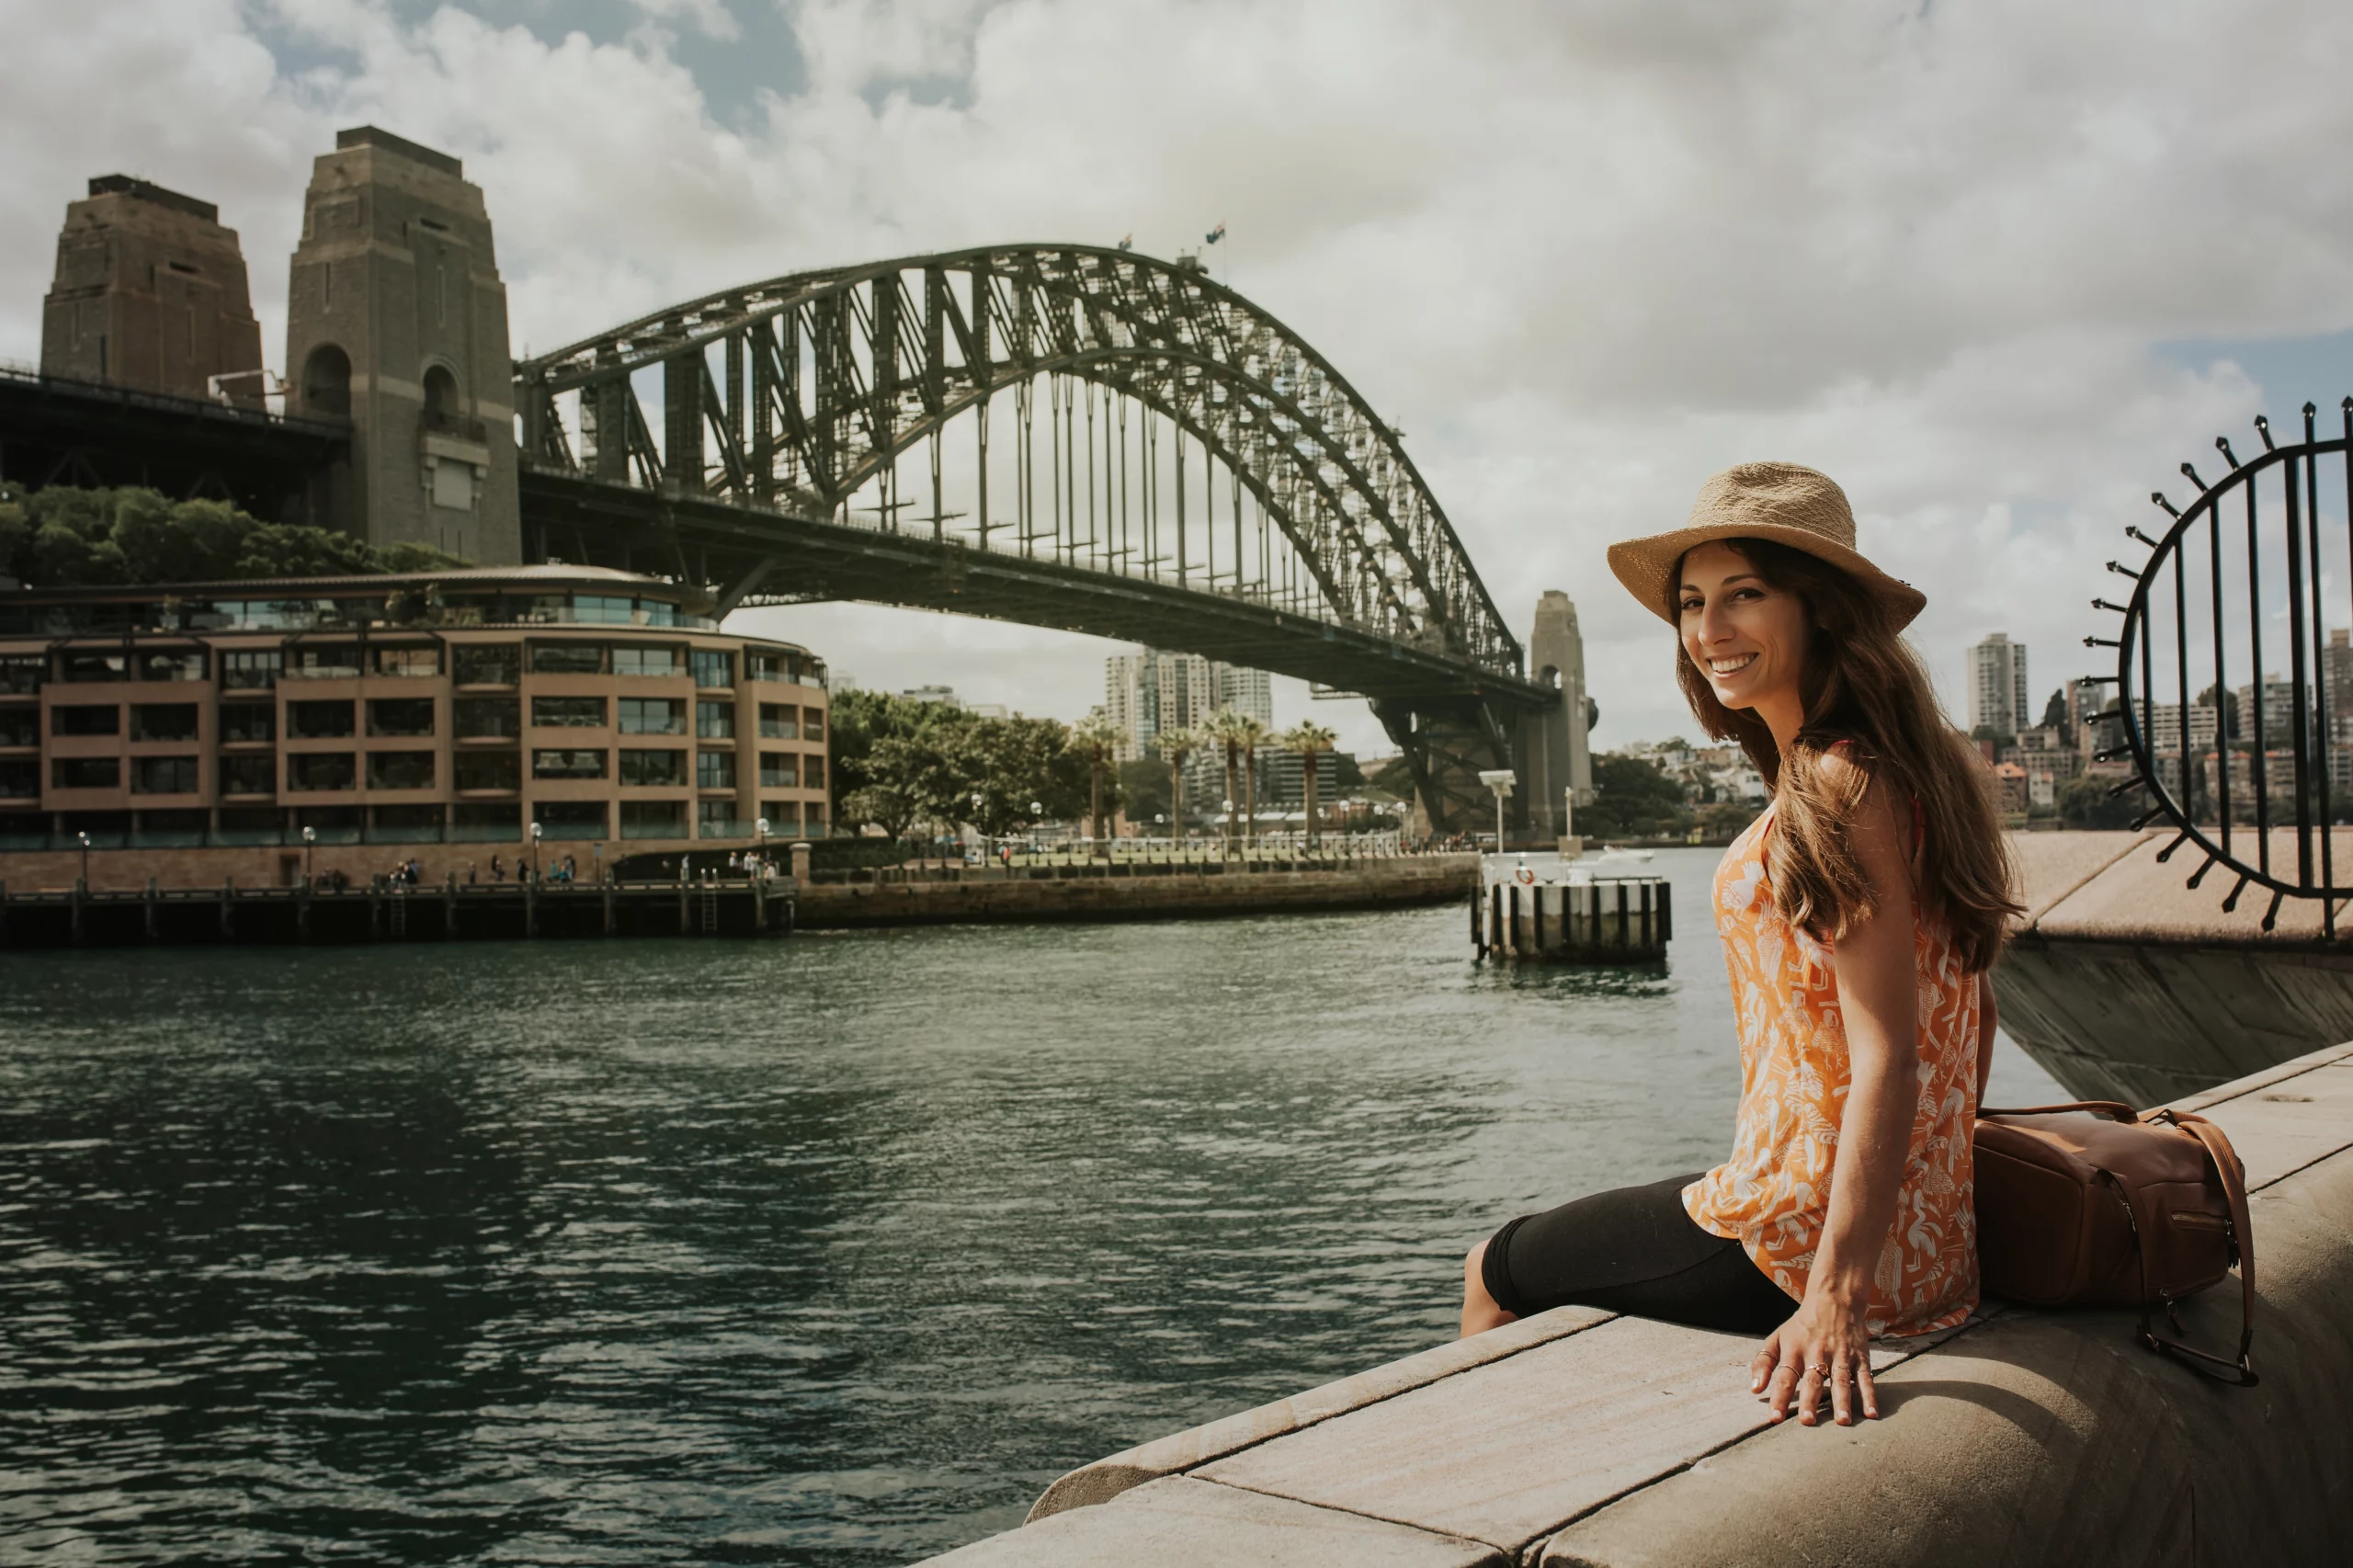
One of Sydney’s most iconic experiences won’t cost you a cent. While climbing the bridge costs hundreds of dollars, walking across the pedestrian pathway offers equally stunning views of the harbour and Sydney Opera House.
3. Royal Botanic Garden Tour
Join the free guided walking tour of the Royal Botanic Garden, located in the heart of the city. Explore native flora, learn about Aboriginal heritage, and enjoy spectacular harbour views, all while staying within your budget. You could also pack a picnic and enjoy the lush surroundings in a romantic spot for an affordable but fun date.
4. Coastal Walks and Trails
Embark on spectacular coastal trails offering stunning ocean views, beautiful beaches, and rocky cliffs. You’ll find no shortage of scenic trails to choose from.
Bondi to Bronte
This coastal walk is a stunning 4km stretch along Sydney’s eastern coastline. You should allow 1.5 hours of walking time to complete.
Bondi to Coogee
For a more extended stroll, you can continue beyond Bronte Beach and make your way to Coogee. This is a 6km trail and should take you 2-3 hours to complete.
Spit to Manly
This spectacular 10km trail will take you through Sydney Harbour National Park and ends at one of the city’s favourite seaside spots, Manly. Set aside roughly 4 hours for this walk.
5. Catch the Manly Ferry
Take the famous Manly Ferry from Circular Quay for a budget-friendly harbour cruise. You’ll get amazing views of the city skyline, the Harbour Bridge, and the Opera House, plus enjoy Manly’s beaches and cafes upon arrival.
6. Visit Sydney’s Local Beaches
Sydney is famous for its stunning beaches, each offering unique experiences and atmospheres. Here’s a glimpse into some of Sydney’s most beloved local beaches:
Bondi Beach
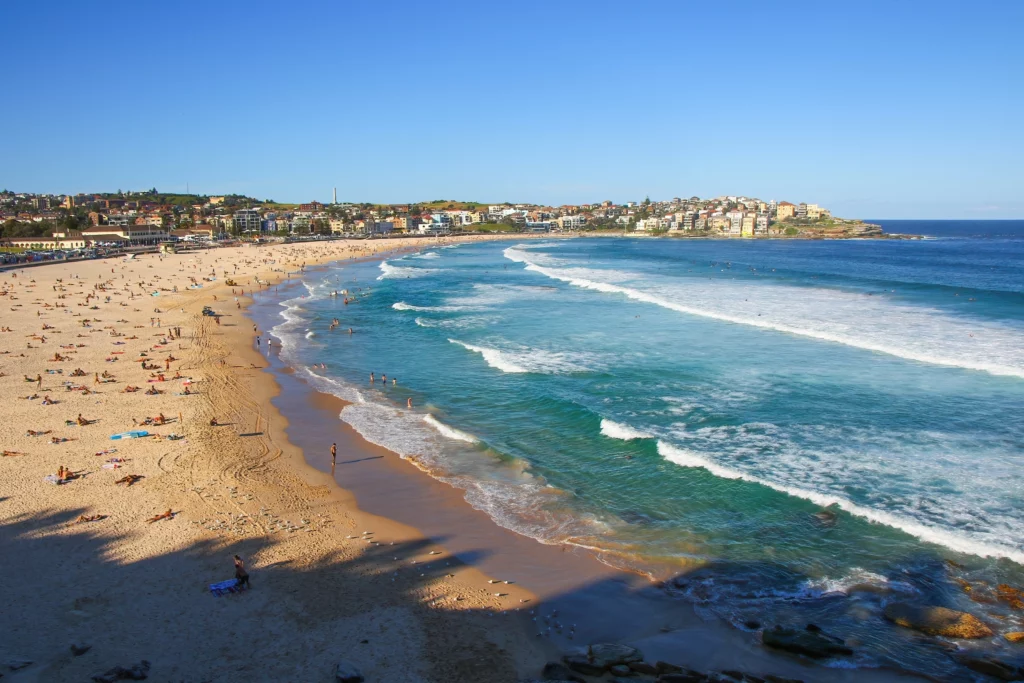
Bondi Beach is perhaps the most iconic beach in Australia, known for its golden sands and vibrant atmosphere. Stretching over a kilometre, it attracts both locals and tourists year-round.
Manly Beach
Accessible by a scenic ferry ride from Circular Quay, Manly Beach is a favourite among Sydneysiders. It offers a laid-back vibe with plenty of shops, restaurants, and beautiful beachside walks.
Shelly Beach
Next to Manly Beach, Shelly Beach is a hidden gem known for its calm waters and beautiful scenery. It’s an excellent spot for snorkelling due to its marine life and underwater gardens. Shelly Beach has picnic facilities and is less crowded than its neighbouring beaches.
7. Dine at The Opera Bar
The Opera Bar is one of Sydney’s most iconic venues on the edge of the stunning Sydney Harbour, right next to the Sydney Opera House. Known for its breathtaking views of the Harbour Bridge and the vibrant atmosphere, it offers a unique dining and entertainment experience that captures the essence of Sydney – the perfect stop for your girls’ weekend getaway.
8. Check Out Sydney’s Museums and Galleries
Sydney boasts an impressive array of museums and galleries that showcase the city’s rich cultural diversity and artistic heritage.
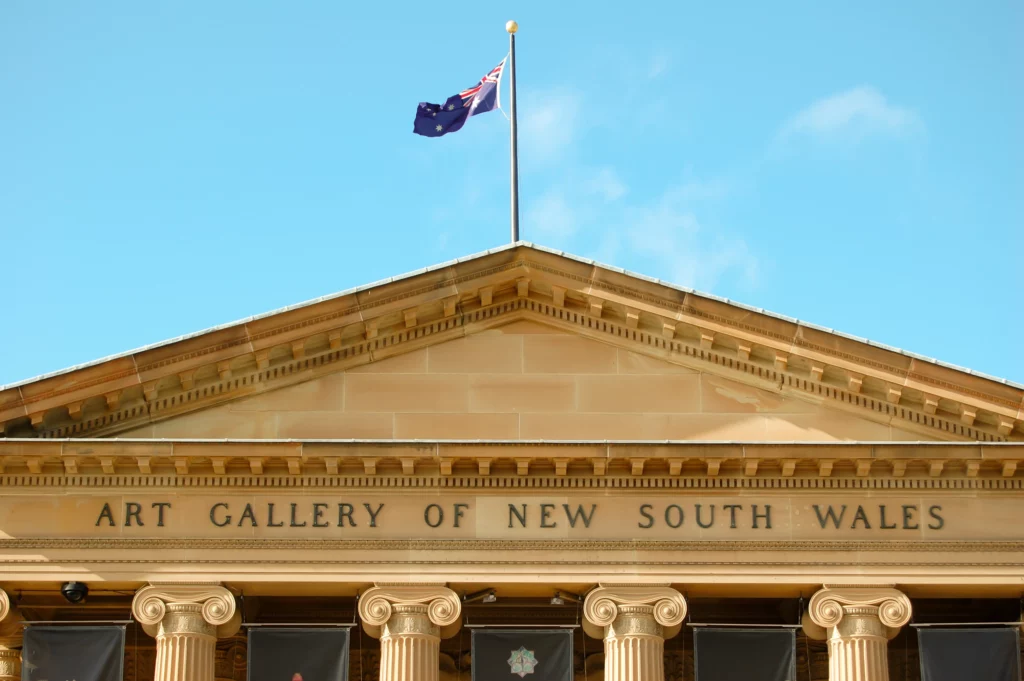
Art Gallery of NSW
Located in the city centre, this premier arts destination offers free entry to its permanent collections spanning:
Classic Australian and European works
Modern and contemporary art
Asian, Aboriginal, and Torres Strait Islander art
Annual Archibald Prize exhibition
Museum of Contemporary Art (MCA)
The MCA is a vibrant cultural institution located at Circular Quay in Sydney’s historic Rocks district. Here are the key details:
Offers free general admission
Celebrates modern-day artists
Boasts a collection of over 4,700 artworks
More than one-third of the artists represented are Aboriginal and Torres Strait Islander artists
Australian Museum
The Australian Museum, located in the heart of Sydney, is Australia’s first museum and a leading institution dedicated to natural history and anthropology. The Australian Museum has:
Free entry to its permanent exhibitions
Exhibitions exploring nature, science, and culture
Over 21 million scientific specimens and cultural objects
Research-driven displays about Australian wildlife and Indigenous cultures
The Rocks Discovery Museum
The Rocks Discovery Museum is a free, family-friendly museum located in a restored 1850s sandstone warehouse in The Rocks. The museum features four permanent exhibitions covering the area’s history.
9. Shop at The Sydney Markets
Offering a wide range of products including vintage clothing and accessories, handmade jewellery and crafts, unique homewares and gift items, gourmet food, and second-hand treasures, there are plenty of Sydney markets to choose from including:
The Kirribilli Markets
The Bondi Markets
The Glebe Markets
The Rocks Markets
The Paddington Markets
10. Explore Darling Harbour
This waterfront precinct is renowned for its stunning views, diverse attractions, and lively atmosphere. You’re sure to find something fun to do with Darling Harbour’s free entertainment, including occasional fireworks displays, street performers, and public art installations.
11. Go On A Hop-On Hop-Off Harbour Cruise
Explore Sydney’s harbour at your own pace. This budget-friendly option allows you to see multiple waterfront attractions at your leisure and includes stops at Circular Quay, Watsons Bay, and Manly.
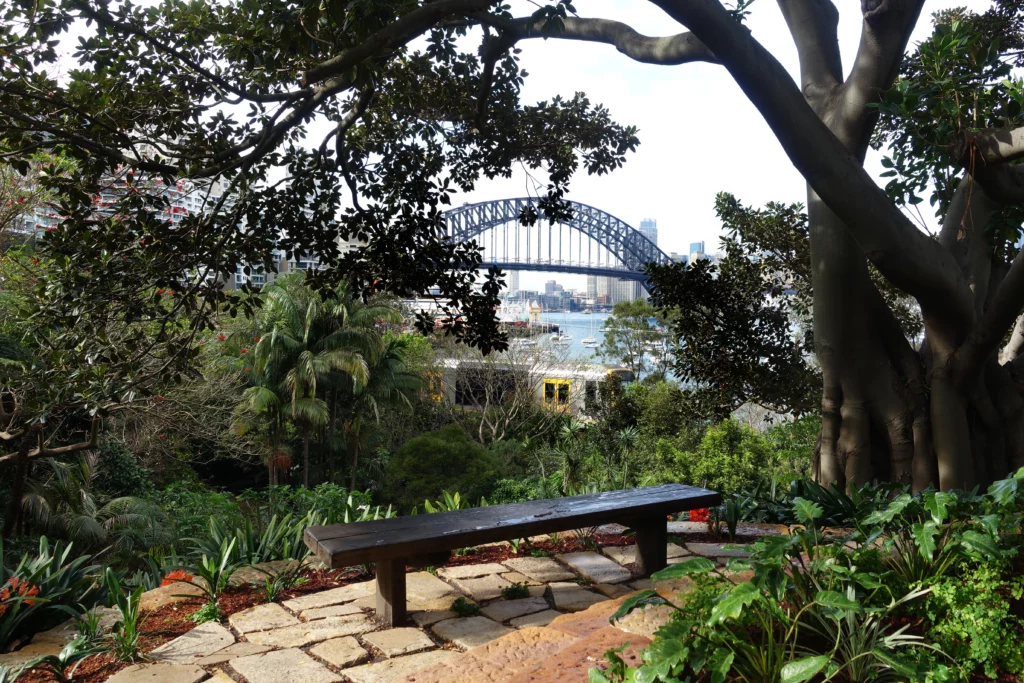
12. Discover The Beauty Of Wendy’s Secret Garden
This hidden gem near Lavender Bay offers beautiful harbour views and a peaceful garden setting. It’s a perfect spot for a romantic stroll or a picnic. The garden is free to enter and features beautiful plants, art installations, and stunning views of the harbour. It’s the perfect romantic getaway on a budget.
13. Check Out The Chinese Garden of Friendship
Located near Darling Harbour, the Chinese Garden of Friendship offers a peaceful escape from the city bustle. The modest entry fee gives you access to traditional Chinese architecture, waterfalls, and tranquil lakes.
14. Explore The Royal National Park
The Royal National Park is a stunning natural reserve located approximately 33 kilometres south of Sydney, making it easily accessible for day trips and outdoor adventures.
15. Take A Dip At The Figure Eight Pools
While visiting the Royal National Park you could check out the Figure Eight Pools, a series of natural rock pools that form a perfect figure eight. Take public transport and walk to this Instagram-famous spot (but make sure you check tides and conditions before visiting).
16. Stroll Through Hyde Park
Take a leisurely walk through Australia’s oldest park. Located in the heart of Sydney’s central business district it spans approximately 16 hectares. Admire its monuments, statues, and impressive fig tree-lined central avenue.
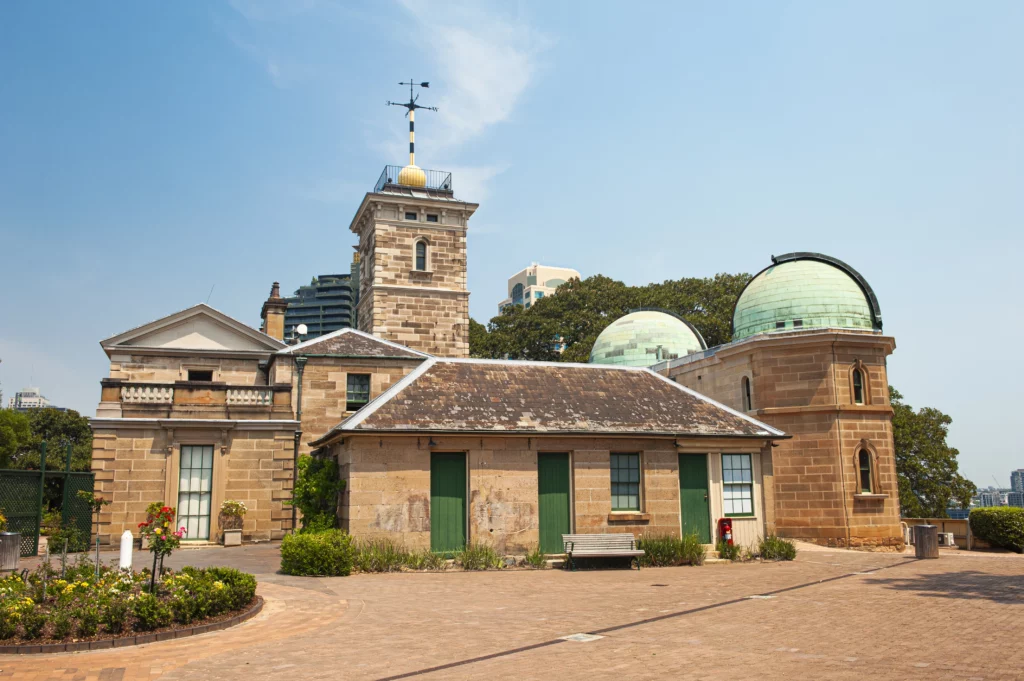
17. Visit The Sydney Observatory
At the Sydney Observatory, visitors can engage in a variety of activities that combine education, exploration, and enjoyment of astronomy. Located on Observatory Hill, the Sydney Observatory is renowned for its historical significance and stunning panoramic views of the Sydney Harbour and iconic Harbour Bridge.
18. Catch A Ferry To Cockatoo Island
Cockatoo Island, located in the heart of Sydney Harbour, offers a variety of activities, experiences and insights into Sydney’s convict and shipbuilding history. Self-guided walking tours are free once you arrive.
19. Window shop at Newtown
Stroll through the eclectic Newtown neighbourhood, known for its vintage stores, quirky boutiques, and impressive street art. This alternative cultural hub is perfect for window shopping and cheap eats.
20. Whale Watch At Barrenjoey Lighthouse
From May to November, Barrenjoey Lighthouse is an excellent spot for whale watching as humpback whales migrate along the coast. Bring binoculars for a better view of these majestic creatures.
You don’t have to break the bank to enjoy Sydney
Sydney offers a wealth of activities that cater to various interests and budgets, proving that you don’t need to spend a fortune to enjoy the city. From scenic coastal walks and vibrant markets to cultural experiences in museums and historical sites, there are plenty of options available for under $30. But if you need extra cash for your trip to Sydney, we offer a range of quick cash loans – including holiday loans!
In Sydney, you can enjoy a wide range of activities, including relaxing on beautiful beaches like Bondi and Coogee, exploring iconic landmarks such as the Sydney Opera House and Harbour Bridge, and hiking scenic coastal trails.
Some must-see attractions for a day in Sydney include:
The Sydney Opera House
The Royal Botanic Gardens
Circular Quay
Taronga Zoo
Manly Beach
The Rocks
Observatory Hill
Yes, there are several low-cost transportation options for getting around Sydney. The Opal card system offers affordable fares for public transport, including trains, buses, ferries, and light rail, with a weekly cap of $50 for adults and $25 for children and concession holders.
The information provided in this blog is of a general nature and is provided without considering your specific objectives, financial situation, or needs. It is intended for informational purposes only and should not be relied upon as financial, investment, or other professional advice.
Before making any financial decisions or taking action based on the information presented, you are strongly encouraged to assess its appropriateness in light of your individual circumstances. Red Tree Finance does not intend to provide personalised financial advice, and you should seek independent financial, legal, tax, and other relevant advice tailored to your unique situation.
News
Other blog articles
From budgeting tips to ways to make your money go further, we’ve got it all. Get financially savvy with the Red Tree Finance blog.
We all rely on our cars to get us to and from work, the shops, or simply to get from A to B. And while regular car servicing and maintenance are important measures that keep our cars running smoothly, sometimes unexpected car troubles occur that require professional attention, leaving you with an often costly car repair bill.
Life can throw financial curveballs from many directions, whether it’s unplanned car repairs, emergency medical bills, or even a spontaneous overseas family trip. When cash is tight, many Australians turn to a personal loan to ease the pressure. It's a fixed lump sum you repay with interest over time – problem solved.
Are you looking to build up some quick cash in your account to fund your next adventure or pay off some bills? While cash loans can present as one solution, it’s entirely likely that you’re sitting on a goldmine right at home.