Borrow between $2,350 - $5,000 today.

Apply now Apply now

Tag: <span>Emergency Loans</span>

image

Where to Get Help Paying Your Car Repair Bill

We all rely on our cars to get us to and from work, the shops, or simply to get from A to B. And while regular car servicing and maintenance are important measures that keep our cars running smoothly, sometimes unexpected car troubles occur that require professional attention, leaving you with an often costly car repair bill.

Budgeting 24 August 2026

In this article:

    Calculate your loan repayments

    How much would you like to borrow?

    Simple. Transparent. Tailored to you.

    Loan amount:
    $
    $2,350 $5,000
    Repayment frequency:
    Weekly repayment:

    (Over 12 month loan term)

    $0.00
    • Loan term 12 months
    • Interest & Fees $1,072
    • Total to pay $3,172
    arrow
      image

      We all rely on our cars to get us to and from work, the shops, or simply to get from A to B. And while regular car servicing and maintenance are important measures that keep our cars running smoothly, sometimes unexpected car troubles occur that require professional attention, leaving you with an often costly car repair bill.

      What are the Common Car Repairs You Might Need?

      Costs for car repairs and maintenance can vary greatly depending on what your vehicle specifically requires. Knowing the rough scale of your car repair bill can go a long way towards helping you determine just what kind of assistance you need.

      Among the common repair and replacement jobs your vehicle might require are:

      • Tyres and brakes: typically $150–$1,200+
      • Battery replacement: typically $150–$450
      • Steering and suspension: typically $300–$1,500+
      • Gearbox repairs: typically $200–$5,000+
      • Major engine work: typically $3,000–$11,000+

      Prices can vary significantly for each type of car repair because costs depend on the specific parts, labour time, and complexity involved in getting your vehicle back on the road.

      How to Pay for Car Repairs

      It costs a lot to own a car. Expenses like fuel, insurance (including Comprehensive, Third Party Property Damage, and Third Party Fire and Theft), and vehicle registration (which typically includes Compulsory Third Party insurance) all add up. So when repairs pop up unexpectedly, it’s important to know your options when the time comes to pay your car repair bill.

      We know that repair costs can vary widely depending on the problem, from a few hundred dollars for tyres or brakes, to several thousand for engine work. Knowing the potential scale of the expense helps you decide whether you can cover it from your savings or need extra support.

      With the right options, you can sort out your car repair bill assistance quickly and keep driving without stress hanging over you.

      What Are the Best Ways to Pay Your Car Repair Bill?

      There’s no single way to manage car repair bills, and the right option depends on your circumstances. Some choices give you fast access to funds, while others reduce the cost of repairs or spread payments over time. Here are some of the most practical ways to cover expenses and get back on the road.

      1. Secured Personal Loan

      A secured personal loan gives you access to funds when you put up an asset such as your car or boat as security. Your vehicle must be registered in your name and drivable, and once approved, funds are released fast.

      With a loan up to $5,000 you may be able to cover the full or partial costs of:

      • Servicing, insurance, and registration
      • Mechanical repairs such as brakes, steering, gearbox or engine parts
      • Body repairs and paintwork
      • Extras like mirrors, roof racks, or air conditioning fixes

      2. Community Programs and No Interest Loan Schemes (NILS)

      If you’re in financial hardship, community organisations may provide access to urgent help with your car repair bill. The most common option is the No Interest Loan Scheme (NILS), which lets you borrow up to $2000 for essentials such as car repairs, rego, or servicing without paying interest.

      3. Borrow From Family or Friends

      Another way to cover urgent car repairs is to borrow from family or friends. This option isn’t for everyone, but if it’s available to you, it may offer a way to save on interest payments and get you back on the road quickly.

      If you go down this path, be clear about the details from the start. Agree on the amount, repayment terms, and timeframe, and write everything down so you all have a plan to follow. Having a simple agreement avoids confusion and helps protect your relationship while you repay the money. The National Debt Helpline offers some helpful tips and information for people considering borrowing from friends or family.

      4. Roadside Assistance and Insurance

      If you already hold roadside assistance or comprehensive insurance, check your policy carefully. Many providers include towing or partial repair cover, which can reduce the amount you need to pay yourself. While it won’t cover everything, it can ease the burden of a breakdown.

      Plan for Stress-free Future Car Repairs

      Not every breakdown is avoidable, but there are ways to reduce the impact when it happens:

      • Build an emergency fund: even $20 a week creates a safety net.
      • Keep up with servicing: prevention is always better than cure, and can stop small issues from turning into major ones.
      • Get multiple quotes: prices vary, so compare before you commit.
      • Know your rights: consumer law protects you if parts or repairs fail.
      • Plan for big-ticket items: budget ahead for tyres, brakes, and batteries, as these wear out regularly.

      By putting a little aside for these costs, you can deal with car repair bills on your own terms. And if the unexpected still happens, Red Tree Finance offers quick cash loans to keep moving.

      For more practical tips, see our guide on how to save money on a low income.

      Get Back on the Road With Confidence

      Fixing a broken-down car does not need to slow you down. The car repair bill may be stressful at first, but you may have more options available to you than you might have realised. From dipping into your savings account to borrowing from friends or family, putting your bill on your credit card, or considering a same-day loan, what is most important is getting on top of your bill early to avoid further complications and get back out on the road as soon as you can.

      Frequently Asked Questions

      View all FAQs View all FAQs

      You can cover repair costs in several ways depending on your situation. Savings are always the cheapest solution if you have funds set aside. If not, community programs such as No Interest Loan Schemes (NILS) may help with essential repairs. Another option is a secured personal loan, where you can borrow up to $5000 using your car or another asset as security. This gives you quick access to money so you can get your car back on the road.

      Selling unused items or borrowing from family and friends can also provide fast cash without interest, but a loan gives you a structured and reliable option when time is critical. But if you need funds immediately, a secured personal loan is usually the fastest option. With Red Tree Finance, the application is 100% online, approval happens in hours, and funds are often released the same day once approved.

      A repairable write-off can sometimes be financed, but it depends on the lender’s rules. To qualify for a secured personal loan with Red Tree Finance, your car needs to be registered, drivable, and able to be used as security. If the vehicle is still classified as a write-off, it may not be eligible. In that case, you might need to explore other funding options, such as a different asset for security or alternative financial support programs.

      The information provided in this blog is of a general nature and is provided without considering your specific objectives, financial situation, or needs. It is intended for informational purposes only and should not be relied upon as financial, investment, or other professional advice.

      Before making any financial decisions or taking action based on the information presented, you are strongly encouraged to assess its appropriateness in light of your individual circumstances. Red Tree Finance does not intend to provide personalised financial advice, and you should seek independent financial, legal, tax, and other relevant advice tailored to your unique situation.
      image
      img
      image
      img
      Apply now

      Ready to apply for a loan?

      Apply to borrow up to $5,000 fast. Complete your online application in under 5 minutes.

      image
      image
      image

      What Is A Line Of Credit?

      Life can throw financial curveballs from many directions, whether it’s unplanned car repairs, emergency medical bills, or even a spontaneous overseas family trip. When cash is tight, many Australians turn to a personal loan to ease the pressure. It's a fixed lump sum you repay with interest over time – problem solved.

      Budgeting 19 August 2026

      In this article:

        Calculate your loan repayments

        How much would you like to borrow?

        Simple. Transparent. Tailored to you.

        Loan amount:
        $
        $2,350 $5,000
        Repayment frequency:
        Weekly repayment:

        (Over 12 month loan term)

        $0.00
        • Loan term 12 months
        • Interest & Fees $1,072
        • Total to pay $3,172
        arrow
          image

          Life can throw financial curveballs from many directions, whether it’s unplanned car repairs, emergency medical bills, or even a spontaneous overseas family trip. When cash is tight, many Australians turn to a personal loan to ease the pressure. It’s a fixed lump sum you repay with interest over time – problem solved.

          Understanding Lines of Credit

          So, what is a line of credit (LOC)? At its core, an LOC is a flexible type of loan: a revolving source of funds with a set limit that you can draw upon, repay, and then draw upon again and again when you need to. For some borrowers who use it in the way it’s intended, a line of credit can act as a financial safety net; an open-ended type of loan with a pre-approved limit.

          How A Personal Line Of Credit Works

          A line of credit works as an open-ended revolving facility, a category that also includes credit cards. When a prospective borrower applies for an LOC, they receive a credit limit (if approved), rather than the lump sum they’d receive with a cash loan.

          As the borrower, this arrangement lets you draw on your available funds up to that limit, and because you only pay interest on the outstanding balance you actually draw, you gain a versatile way to manage your fluctuating financial needs.

          Secured vs. Unsecured LOCs

          Lines of credit come as secured or unsecured, depending on the type you apply for.

          Applying for a secured line of credit requires you to put up an asset as collateral, such as a car or your home, just as you would for a secured loan. And like a loan, failure to meet your repayments means that the lender can seize the asset to recover what you owe.

          An unsecured LOC doesn’t require this type of guarantee, but it typically comes with a higher interest rate. You’ll also find that an unsecured line of credit comes with a lower maximum limit due to the greater risk level attached to it.

          Types Of Lines Of Credit

          When you ask “what is a line of credit?” you’ll discover that there are four key types available:

          • Personal line of credit
          • Business line of credit
          • Line of credit home loan
          • Credit card as LOC

          Personal Line Of Credit

          A personal line of credit is the most common type of LOC and is generally what most people apply for when they want flexible, ongoing access to funds. The flexibility and ease of use they offer make them helpful in situations where you may have ongoing or unpredictable expenses. Think home repairs and renovations that might regularly go over your initial budget, or medical expenses that you might pay off in stages. Like a personal loan, potential approval for an LOC is contingent upon income, expenses and credit history checks.

          Business Line Of Credit

          Businesses can apply for a line of credit that serves a similar purpose to a personal LOC. It also enables you to link your business debits and credits to the account.

          Line Of Credit Home Loan

          Also known as a Home Equity Line of Credit (HELOC), this allows homeowners to borrow against the equity in their property. It’s different from a mortgage redraw, which lets you access your own extra repayments rather than a credit limit.

          Credit Card As A Line Of Credit

          Finally, you have a credit card, which allows you to spend, withdraw and make repayments to a credit account with a pre-approved limit.

          Line Of Credit Interest Rates: What You Need To Know

          One important factor to consider when we look at the question “What is a line of credit?” is the matter of interest rates.

          Marketwide in Australia, LOC interest rates often vary depending on whether the product is secured or unsecured, what the lender offers, and the borrower’s individual circumstances, such as credit history. As with any credit product, it’s worth comparing rates and fees carefully before making any decisions.

          The Advantages Of A Line Of Credit

          When it comes to loan options, a personal line of credit may present several advantages to some potential borrowers.

          One Application, Ongoing Access

          A personal line of credit is an ongoing and open-ended loan arrangement. Once you’ve applied and the lender has approved your LOC, you won’t need to keep applying each time you wish to borrow more funds. As long as there is money available in your account, you have funds that you can draw upon.

          Ready When You Want It

          A line of credit can be a convenient financial safety net, giving you quick access to funds during unexpected emergencies or times of fluctuating expenses.

          The Possible Drawbacks Of A Line Of Credit

          While a line of credit can suit many, it won’t necessarily be the right fit for everyone. Here are some potential drawbacks to watch out for.

          Variable Interest Charges

          Interest rates on lines of credit are often variable, which means your monthly repayments can change from month to month.

          Risk Of Overspending

          With easy access to funds, it’s important to stay disciplined and not treat your line of credit like an endless source of money. Some people can fall into the trap of overspending and building up significant amounts of debt.

          Collateral Risks

          If you choose a secured line of credit, you’ll put up an asset, such as your home or car, as collateral. Missing repayments could result in losing that asset, so it’s a serious commitment to consider.

          Alternatives To A Line Of Credit

          While a line of credit has its benefits, it’s worth exploring some other options that might better suit your needs.

          Personal Loans

          A personal loan gives you same-day access to a fixed amount of funds over a fixed term. You can use them for a wide range of purposes, from dental surgery to rental bond payments and even consolidating your existing debts.

          Like an LOC, they do come with establishment fees, interest rates and penalties for late or missed payments. But with a fixed term and a fixed interest rate, you’ll always know what you need to pay and when you need to pay it.

          Home Loan Redraw Facility

          If you’re able to make additional repayments to your home loan, a redraw facility is another option to consider. This feature allows you to access the additional funds you’ve already paid into your mortgage, so your home loan can serve as a flexible source of funds. A redraw facility can be a cost-effective option given that the interest rate on a home loan is typically much lower than that of a personal line of credit or a credit card.

          Line of Credit vs Personal Loan: Which Is Better?

          If you’re asking “What is a line of credit?” because it’s an option you’re considering and comparing against the more familiar fixed-term instant loan, know that there is no single right answer. In the end, it depends on what you need the funds for.

          For a one-off known expense that won’t change, and that you can finalise on a fixed date (or sooner), a loan may be a more suitable option. You get a fixed amount to repay over a fixed term, with consistent repayments.

          For continuous or unpredictable expenses, a line of credit may offer more flexibility as you can draw funds as you need them rather than agreeing to an upfront lump sum. You’ll likely find that costs vary drastically between individual lenders and products, so it’s worth comparing rates, fees, and terms directly rather than assuming one product type is cheaper than the other.

          Make The Smart Choice For Your Financial Needs

          At Red Tree Finance, we know how important it is to build a healthy financial future. That’s why we offer a range of personal loan options designed to help you reach your goals.

          If a line of credit isn’t quite what you’re after, one of our fixed-term personal loans might be the perfect fit.

          Whether you’re looking for a fast loan to help you address an unexpected expense or need a loan to help with the costs of moving house, get in touch with Red Tree Finance to see how we can help you.

          A personal line of credit can be a useful financial tool if you have the discipline to manage it wisely and avoid overspending. That said, whether it’s right for you depends on your current financial situation and individual needs. It’s important to consider your ability to repay and how an ongoing credit arrangement will fit with your budget before making a decision.

          The best option for you will ultimately depend on your financial situation and borrowing needs. A fixed loan offers a set amount with predictable repayments, making it a good choice for specific projects or expenses. In contrast, a revolving line of credit provides ongoing access to funds, which can be good for managing fluctuating costs or emergencies.

          A line of credit can present several disadvantages. Interest rates are usually variable, so your repayments may vary from month to month, and because the credit is ongoing, there’s a risk of overspending if you’re not careful. Plus, if your line of credit is secured, you could risk losing your asset if repayments aren’t kept up.

          The information provided in this blog is of a general nature and is provided without considering your specific objectives, financial situation, or needs. It is intended for informational purposes only and should not be relied upon as financial, investment, or other professional advice.

          Before making any financial decisions or taking action based on the information presented, you are strongly encouraged to assess its appropriateness in light of your individual circumstances. Red Tree Finance does not intend to provide personalised financial advice, and you should seek independent financial, legal, tax, and other relevant advice tailored to your unique situation.
          image
          img
          image
          img
          Apply now

          Ready to apply for a loan?

          Apply to borrow up to $5,000 fast. Complete your online application in under 5 minutes.

          image
          image
          image

          How Much Do You Need For An Emergency Fund?

          Having a financial safety net in place can provide much-needed peace of mind during uncertain times. But you might be wondering how much do you need for an emergency fund? At Red Tree Finance, we understand the importance of being prepared for the unexpected, so we’ve put together a guide to help you understand emergency

          Budgeting 12 August 2025

          In this article:

            Calculate your loan repayments

            How much would you like to borrow?

            Simple. Transparent. Tailored to you.

            Loan amount:
            $
            $2,350 $5,000
            Repayment frequency:
            Weekly repayment:

            (Over 12 month loan term)

            $0.00
            • Loan term 12 months
            • Interest & Fees $1,072
            • Total to pay $3,172
            arrow
              image

              Having a financial safety net in place can provide much-needed peace of mind during uncertain times. But you might be wondering how much do you need for an emergency fund? At Red Tree Finance, we understand the importance of being prepared for the unexpected, so we’ve put together a guide to help you understand emergency funds, how to build and manage them, and how much you need for your own.

              What Is An Emergency Fund?

              In life, unexpected financial emergencies can strike at any moment. From medical bills to car repairs or sudden unemployment, it’s important to ensure you have a financial buffer when these unforeseen circumstances occur. An emergency fund is a dedicated savings account specifically designed to cover unexpected expenses or financial emergencies.

              Unlike other savings goals, such as holidays or home renovations, the primary purpose of an emergency fund is to provide financial stability and security during unforeseen circumstances. It serves as a financial cushion, offering protection against the unexpected and helping individuals avoid falling into debt when faced with unexpected expenses.

              How Much Do I Need In An Emergency Fund?

              Determining the appropriate amount for your emergency fund depends on various factors, including your monthly household expenses, financial obligations, and individual circumstances.

              As a general rule of thumb, financial experts often recommend saving 3 to 6 months worth of living expenses. This buffer can help cover essential costs in the event of a sudden financial setback, providing a safety net to navigate through challenging times.

              Learn more: Saving for an emergency fund

              Where Should You Put The Money For An Emergency Fund?

              When it comes to storing your emergency fund, accessibility are key considerations. Opt for accounts that offer easy access to your funds, such as a high-interest savings account. These accounts typically offer higher interest rates than traditional savings accounts while still allowing you to withdraw funds quickly and without penalties when needed.

              If you have a mortgage with a redraw function or offset account, this is another great option as you can save interest on your mortgage while still having easy access to your emergency funds.

              How Do I Manage An Emergency Fund?

              Building your emergency fund involves committing to regular contributions, periodic reassessments, and disciplined financial habits. Set up automatic transfers to your emergency fund account each pay period to ensure consistent savings growth. Periodically review your fund’s balance and adjust your savings goals as needed to account for changes in expenses or income.

              Additionally, resist the temptation to dip into your emergency fund for non-essential expenses, reserving it exclusively for true emergencies.

              When Is The Right Time To Use My Emergency Fund?

              Knowing when to tap into your emergency fund requires careful consideration and judgement. Reserve your emergency fund for genuine emergencies, such as unexpected medical expenses, major vet bills, or sudden job loss.

              Before accessing your emergency fund, explore alternative options like selling items and consider the urgency and necessity of the expense. Remember, rebuilding your emergency fund should be a top priority after utilising it, ensuring you’re prepared for future unexpected challenges.

              Emergency Loans With Red Tree Finance

              In times of financial uncertainty, having a well-funded emergency fund can provide invaluable peace of mind and security. At Red Tree Finance, we understand the importance of financial preparedness. If you find yourself facing unexpected expenses beyond your emergency fund’s coverage, remember that we offer small personal loans of up to $5000 to help you bridge the gap during challenging times. Apply today or contact us for more information on loan eligibility or rates & fees.

              Frequently Asked Questions

              View all FAQs View all FAQs

              Calculate how much you spend in a month and aim to accumulate an emergency fund equivalent to 3 to 6 months’ worth of your expenses.

              It’s advisable to review your emergency fund savings goal at least once a year or whenever significant changes occur in your financial situation, such as a change in income, expenses, or family circumstances. Adjust your savings target accordingly to ensure your emergency fund remains sufficient to cover unforeseen expenses.

              While reducing debt is important for long-term financial health, using your emergency fund to pay off high-interest debt may leave you vulnerable in the event of an unexpected expense. Focus on building a separate emergency fund while concurrently working towards paying off high-interest debt. By maintaining a balance between debt repayment and emergency savings, you can achieve financial stability without sacrificing your safety net.

              People also read:

              The information provided in this blog is of a general nature and is provided without considering your specific objectives, financial situation, or needs. It is intended for informational purposes only and should not be relied upon as financial, investment, or other professional advice.

              Before making any financial decisions or taking action based on the information presented, you are strongly encouraged to assess its appropriateness in light of your individual circumstances. Red Tree Finance does not intend to provide personalised financial advice, and you should seek independent financial, legal, tax, and other relevant advice tailored to your unique situation.

              image
              img
              image
              img
              Apply now

              Ready to apply for a loan?

              Apply to borrow up to $5,000 fast. Complete your online application in under 5 minutes.

              image
              image
              image

              10 Cheap Ways to Heat A House In Australia

              While most people brace themselves for higher electricity bills in summer when the air conditioner is running around the clock, the cost of heating is often underestimated. Heating and cooling together account for about 40 per cent of household energy use, which means they can have the biggest impact on your budget.

              Budgeting 14 May 2025

              In this article:

                Calculate your loan repayments

                How much would you like to borrow?

                Simple. Transparent. Tailored to you.

                Loan amount:
                $
                $2,350 $5,000
                Repayment frequency:
                Weekly repayment:

                (Over 12 month loan term)

                $0.00
                • Loan term 12 months
                • Interest & Fees $1,072
                • Total to pay $3,172
                arrow
                  image

                  While most people brace themselves for higher electricity bills in summer when the air conditioner is running around the clock, the cost of heating is often underestimated. Heating and cooling together account for about 40 per cent of household energy use, which means they can have the biggest impact on your budget.

                  Why Australian Homes Are Hard to Heat Efficiently

                  Many Australian houses are built with minimal insulation. Unlike homes in Europe, they often lack double glazing or effective sealing. This means heat escapes quickly, leaving rooms cold even while heaters work overtime.

                  Another challenge is draughts. There are often large gaps around doors, windows, and floorboards that allow cold air to creep in, making heaters much less effective. Identifying and blocking these leaks is one of the fastest ways to improve efficiency.

                  If you rent, you might ask your landlord about upgrades such as insulation, weather seals, or solar panels. These changes can reduce costs and improve property value, making them a worthwhile investment for both tenants and owners.

                  What Is the Cheapest Heater to Run in Australia?

                  Not all heaters are the same. Some appliances cost far more to run than others, even if they appear smaller or less powerful. That means cheap doesn’t always mean better.

                  Reverse cycle air conditioners, also known as split systems, are the cheapest option for most Australian households. They generate more heat per unit of electricity than portable heaters, making them consistently efficient. Many models can also be used in summer for cooling, spreading their value across the year.

                  If you’re shopping for a new heater, look closely at the energy rating. Higher-rated appliances may cost more upfront but deliver long-term savings. Choosing efficiency and lifetime value now means lower bills for years to come.

                  Which Heaters Cost the Most to Run?

                  Portable fans and heaters are among the least efficient appliances in Australian homes. They use large amounts of electricity but provide limited warmth, meaning they can add hundreds of dollars to a winter bill.

                  Other expensive options include electric bar radiators. These often heat unevenly and lack efficiency, particularly in larger spaces. You’ll save at the checkout, but you’ll lose out in the long run with higher energy bills.

                  Where possible, replace these appliances with a reverse cycle system or at least choose higher energy-efficient models. If you can’t make the switch right away, limit their use to short bursts and combine them with other low-cost heating methods.

                  Do Higher-Watt Heaters Cost More to Run?

                  Yes. Wattage indicates how much electricity a heater uses. For example, a 3000-watt heater running for three hours uses three times the energy of a 1000-watt unit. While packaging may suggest that more watts means better performance, in reality, it means higher bills.

                  When comparing appliances, balance wattage with efficiency. A lower-wattage heater with a high star rating is usually the best value, providing warmth without the shock of inflated energy costs.

                  10 Cheap Ways to Heat a House in Australia

                  Simple changes can make a big difference to the way you keep your house warm. By combining these 10 habits, you can keep your home warmer for longer and reduce energy costs during the cooler months.

                  1. Reduce the Space You Heat

                  Heating your entire home wastes money, especially if you only use certain rooms throughout the day. Larger open-plan spaces or unused bedrooms can draw heat away from the areas where you actually spend the most time. By focusing only on the rooms you need to heat, you give your heater less work to do and keep your costs down.

                  To make this work, close doors to unused areas and use zoning features on ducted systems. Timers are another smart addition to make sure heaters aren’t left running when no one is home. Even turning the heater off 30 minutes before leaving home lets residual warmth carry you through, reducing costs without sacrificing comfort.

                  2. Install Curtains to Trap Warmth

                  Windows are one of the biggest culprits for heat loss, with up to 40 per cent of a home’s warmth escaping through glass.

                  Layering sheer and blockout curtains or installing blinds on your windows can make a noticeable difference to the insulating properties of a room. If you are renting, try using dowels and command hooks to hang temporary curtains. You’ll be surprised by the difference that even a lightweight curtain makes to the temperature stability inside the room.

                  3. Dress for Warmth Indoors

                  It’s tempting to turn up the heat when you feel cold, but every extra degree adds around 10 per cent to your energy use. That can mean a significant jump in your quarterly bill. Dressing appropriately for the cooler months is one of the simplest ways to stay comfortable without touching the heater.

                  Think of your home as part of your winter outfit. Pull on jumpers, socks, or even an Oodie and add blankets to your couch or bed. By creating warmth through clothing and coverings, you can keep the thermostat lower and still feel cosy. This simple habit change saves money and makes heating a choice, not a necessity.

                  4. Keep Moving to Stay Warm

                  When your body is still, it loses heat faster, so get up and move around to stay warm. Regular movement not only keeps you warm but also boosts circulation and energy levels.

                  Take short 5-10 minute breaks throughout the day to stretch, walk around, or do light household chores. For those working from home, schedule “movement breaks” as you would a meeting. A quick burst of activity can raise your body temperature and make you less reliant on appliances to stay warm. It’s a win-win. You stay warm, save money and keep active in the process.

                  5. Warm Up with Hot Food and Drinks

                  Sometimes the best comfort comes from inside. Hot meals and drinks raise your core body temperature, creating warmth that lingers long after you’ve eaten.

                  Cooking at home has the added benefit of releasing radiant heat into the kitchen and surrounding areas. Soups, teas, and baked dinners not only keep you full but also contribute to a warmer home environment. It’s a simple routine that turns mealtime into an opportunity to cut heating costs.

                  6. Block Draughts and Seal Gaps

                  Even the best heating system struggles if warm air is constantly escaping. Small gaps under doors, around windows or through floorboards can leak more heat than you realise. The result is a home that never feels quite warm enough, no matter how long the heater runs.

                  Draught stoppers, weather seals or even rolled-up towels can make a big difference.. By blocking cold air from entering and warm air from leaving, you make your home instantly more comfortable. This step pairs well with curtains and zoning, giving you a multi-layered defence against heat loss.

                  7. Use Hot Water Bottles or Wheat Bags

                  Leaving an electric blanket on all night might seem like a cosy way to sleep, but it’s both costly and potentially dangerous. A safer and cheaper alternative is a hot water bottle or a wheat bag. They provide concentrated warmth exactly where you need it, without draining electricity.

                  Boil the kettle once, fill your hot water bottle, and you’re set up for a cosy and warm night’s sleep. Wheat bags can be heated in the microwave for a quick, reusable option. These simple solutions keep you cosy through the night without the expense of running appliances.

                  8. Cook Meals to Create Heat

                  In the summer, the oven can often heat your home when you need it the least, but in the cooler months, it becomes an ally. Cooking releases heat into your home, turning everyday meals into a source of comfort.

                  Roasting vegetables, baking bread, or preparing casseroles will warm the kitchen and surrounding rooms. This works best in the evenings, when outdoor temperatures drop and you would otherwise be tempted to crank up the heater.

                  Another benefit is the way cooking brings people together. The smell of bread baking or a roast in the oven can lift the mood of the whole household, making the space feel more inviting and warmer when it’s cold.

                  It’s a delicious, efficient and cosy way to double up on warmth. If you’re looking for cooking ideas, check out our article on family meals under $10.

                  9. Reverse Ceiling Fans in Cooler Months

                  Heat rises, which means a lot of the warmth you pay for shoots up to the ceiling instead of where you need it. Ceiling fans with a reverse setting solve this by pushing warm air back down into the room.

                  Set the blades to spin slowly clockwise. This redistributes heat evenly, making rooms feel warmer without additional energy use. Pairing this trick with zoning and curtains maximises efficiency and keeps heating bills down.

                  10. Follow the Sun Indoors

                  One of the cheapest and most natural forms of heat is sunlight. During the cooler months, harnessing it effectively can reduce your reliance on heaters.

                  Open curtains and blinds during sunny days to let warmth flood in. As the sun sets in the evening, close them again to trap the heat indoors. Position furniture near sunny windows to take full advantage of natural light. It’s a cost-free way that keeps your home warmer and brighter.

                  Take Control of Heating Costs with Red Tree Finance

                  Keeping your home warm and your bills under control is more than comfort. It is about your health and peace of mind. During the cooler months, staying warm is important for families with children, the elderly, or anyone working from home for long periods. Energy-saving tips can go a long way toward lowering costs, but sometimes the unexpected still happens.

                  If you are already facing a larger-than-expected power bill, Red Tree Finance can help. Our loans for bills give you the option to combine repayments into one manageable schedule so you can stay ahead rather than falling behind. You can apply online today or, if you prefer, talk with our customer service team about the best way forward for you.

                  Frequently asked questions

                  View all FAQs View all FAQs

                  Reverse cycle air conditioners, also known as split systems or heat pumps, are the most cost-effective option. They can generate three to four units of heat for every unit of electricity used, making them far cheaper to run than portable heaters or bar radiators. Unlike single-purpose appliances, many models can also cool your home in summer, spreading their value across the year.

                  When shopping for a heater, always check the energy rating. Higher-rated models may cost more upfront, but they deliver savings with every bill. For households that want reliable and efficient warmth during the cooler months, a reverse cycle system is one of the smartest investments.

                  The most common system today is the reverse-cycle air conditioner. These units are popular because they are relatively affordable to run, provide both heating and cooling, and are widely available across the country. In older homes, gas heaters and wood fires are still common, particularly in colder states like Victoria and Tasmania.

                  No matter what system is in place, efficiency often comes down to how it is used. Simple actions like closing doors to unused rooms, sealing draughts and adding insulation can help any heating system perform better while keeping energy bills under control.

                  Australian houses are typically built for hot summers rather than cold winters. Lightweight walls, single-glazed windows and limited insulation mean that heat escapes quickly, leaving homes chilly even when the heater is on. Draughts from gaps in doors and windows also add to the problem, making it harder to stay warm.

                  This design choice is the main reason many households experience higher bills in the cooler months. Improving insulation, using curtains, and applying low-cost heating habits can help offset these design flaws and make homes more comfortable.

                  People also read:

                  The information provided in this blog is of a general nature and is provided without considering your specific objectives, financial situation, or needs. It is intended for informational purposes only and should not be relied upon as financial, investment, or other professional advice.

                  Before making any financial decisions or taking action based on the information presented, you are strongly encouraged to assess its appropriateness in light of your individual circumstances. Red Tree Finance does not intend to provide personalised financial advice, and you should seek independent financial, legal, tax, and other relevant advice tailored to your unique situation.
                  image
                  img
                  image
                  img
                  Apply now

                  Ready to apply for a loan?

                  Apply to borrow up to $5,000 fast. Complete your online application in under 5 minutes.

                  image
                  image
                  image

                  How Much Debt Does The Average Australian Have?

                  Financial debt is a reality for many Australians. Whether it’s getting a mortgage, home renovations, starting a business or covering unexpected expenses, borrowing money has become a financial tool used by many Aussies. There are many ways to handle debt if you feel like it’s getting out of control, like a debt consolidation loan. But

                  Debt Consolidation 22 April 2025

                  In this article:

                    Calculate your loan repayments

                    How much would you like to borrow?

                    Simple. Transparent. Tailored to you.

                    Loan amount:
                    $
                    $2,350 $5,000
                    Repayment frequency:
                    Weekly repayment:

                    (Over 12 month loan term)

                    $0.00
                    • Loan term 12 months
                    • Interest & Fees $1,072
                    • Total to pay $3,172
                    arrow
                      image

                      Financial debt is a reality for many Australians. Whether it’s getting a mortgage, home renovations, starting a business or covering unexpected expenses, borrowing money has become a financial tool used by many Aussies. There are many ways to handle debt if you feel like it’s getting out of control, like a debt consolidation loan. But how much debt does the average Australian have? We’ll explore both consumer and mortgage debt so you can find out where you stand.

                      How much debt does the average Australian have?

                      In Australia, according to an independent Finder study, the average household debt is $261,492, made up of mortgage and consumer debt. Of course, most of that debt is in the form of mortgages, so to get a clearer picture of consumer debt, we need to remove property from the equation.

                      The average consumer debt (excluding mortgages)

                      Consumer debt refers to any type of personal debt that is not connected to a home loan. Consumer debt is usually taken out to purchase goods or services that do not appreciate in value and are often purchased for short-term use. The average Australian consumer debt is:

                      • Credit card debt: $3,306
                      • Personal loans: $8,098
                      • Car loans (can be short or long term): $13,315
                      • Buy now, pay later (BNPL) services: $867

                      It is important to manage your consumer debt responsibly as these types of loans are labelled as “bad debt” by credit reporting bodies. Consumer debt is considered to be bad debt because the goods or services purchased using this debt often depreciate over time and are usually attached to higher interest rates.

                      Creating a budget can help you stay ahead of your repayments and to meet your repayments when they are due. A budget allows you to track how much money you need to have allocated for debt repayments.

                      What is the average mortgage debt?

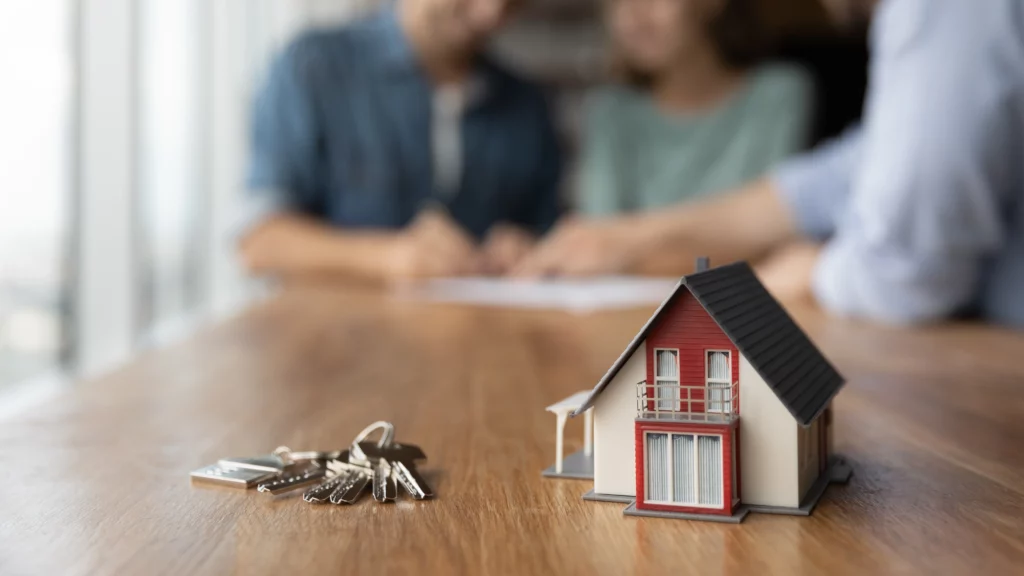
                      Close up of a toy house next to a set of keys with a couple signing the mortgage paperwork in the background

                      According to the latest Australian Bureau of Statistics (ABS) data, the average home loan debt is $665,978. This reflects the ongoing growth in property prices and the larger loans that buyers are taking on to enter the property market.

                      The price of new builds is typically tied in with the current market prices, which means that first-home buyers(or those who are building) have to borrow more, compared to buyers who purchased years ago. The average home loan debt is affected by owners who purchased their properties for a lower purchase price and who may have locked in their interest rates at a lower rate.

                      Can you consolidate multiple loans?

                      If you have multiple smaller consumer loans, such as credit card debt or small cash loans, one way to stay on top of your repayments is with a debt consolidation loan. Debt consolidation combines multiple loans and debts into a single easy-to-meet repayment.

                      Instead of keeping up with multiple due dates and varying amounts, debt consolidation simplifies things by combining all your debts into one single loan and repayment, with the same amount due each repayment cycle.

                      What are some strategies to reduce debt?

                      Happy couple make a budget on a laptop together

                      You can reduce your debt by taking small, manageable steps that help you take back control of your finances. You don’t need to be an expert – just a few smart habits can make a big difference over time such as:

                      • Create a budget to track your income and expenses (such as utility bills), helping you understand where your money is going and where you can cut back.
                      • Pay more than the minimum on your debts when you can, especially those with high interest.
                      • Focus on one debt at a time, using strategies like the snowball (paying off your smallest debt first) or avalanche (paying off your highest interest debt first) methods.
                      • Avoid taking on new debt unless it is essential or an emergency.
                      • Avoid big-ticket purchases where possible, until you have paid off your debts.
                      • Look for extra income, such as freelance work, a side hustle, or selling unused items.
                      • Cut non-essential spending, like dining out, ordering in, or subscription services you rarely use.

                      Take control of your debt with Red Tree Finance

                      By adjusting your habits and putting together a solid plan, you can steadily reduce your debt and gain more control over your financial future. If you’re looking for a way to streamline your debts into one simple repayment, consider a debt consolidation loan. It can be a great way to make sure you never miss a repayment, and it’s possible to pay less interest over the lifetime of the loan. If you have any questions or need more information, feel free to contact our dedicated team.

                      Frequently Asked Questions

                      View all FAQs View all FAQs

                      The estimated average debt of an Australian is approximately $21,413 in personal (consumer) debt. Some examples of common consumer debts include:

                      • Credit card debt
                      • Personal loans
                      • Car loans (can be short or long term)
                      • Buy now, pay later (BNPL) services

                      According to Money.com.au, in 2025, the average Australian has $46,825. This amount does vary between the different generations and is heavily influenced by the older demographics.

                      People also read:

                      The information provided in this blog is of a general nature and is provided without considering your specific objectives, financial situation, or needs. It is intended for informational purposes only and should not be relied upon as financial, investment, or other professional advice.

                      Before making any financial decisions or taking action based on the information presented, you are strongly encouraged to assess its appropriateness in light of your individual circumstances. Red Tree Finance does not intend to provide personalised financial advice, and you should seek independent financial, legal, tax, and other relevant advice tailored to your unique situation.
                      image
                      img
                      image
                      img
                      Apply now

                      Ready to apply for a loan?

                      Apply to borrow up to $5,000 fast. Complete your online application in under 5 minutes.

                      image
                      image
                      image

                      How To Get Help With Medical Bills In Australia

                      When you or a loved one needs urgent medical care, the top priority is getting the proper treatment as soon as possible. Between doctor's visits, prescriptions, scans, hospital stays, and treatment, the costs can add up fast, leaving you with overwhelming medical bills. Even if you have private health insurance coverage, there’s often a gap

                      Budgeting 16 April 2025

                      In this article:

                        Calculate your loan repayments

                        How much would you like to borrow?

                        Simple. Transparent. Tailored to you.

                        Loan amount:
                        $
                        $2,350 $5,000
                        Repayment frequency:
                        Weekly repayment:

                        (Over 12 month loan term)

                        $0.00
                        • Loan term 12 months
                        • Interest & Fees $1,072
                        • Total to pay $3,172
                        arrow
                          image

                          When you or a loved one needs urgent medical care, the top priority is getting the proper treatment as soon as possible. Between doctor’s visits, prescriptions, scans, hospital stays, and treatment, the costs can add up fast, leaving you with overwhelming medical bills. Even if you have private health insurance coverage, there’s often a gap to pay, and certain items may not be included. A medical loan can help you out in an emergency, but if you’re wondering how to get help with medical bills, Red Tree can help. Stressing about expenses can make it harder to recover, so to help you plan for the worst, here are the best ways to finance unexpected medical costs.

                          Medicare support

                          A smiling couple sit in a hospital waiting room together

                          Medicare is Australia’s public healthcare system that covers or contributes towards the costs of many essential medical services, such as emergency care, hospital treatment in a public hospital, prescription medicines, and in-hospital tests and scans.

                          In Australia, Medicare provides a fixed rebate for medical services and GP consultations, as outlined in the Medicare Benefit Schedule (MBS), which reflects what the government deems a ‘reasonable cost.’ However, this rebate has not kept pace with rising healthcare costs. Despite government incentives to help ease the financial burden on patients, costs still increased almost 6% between 2023 and 2024, meaning a 20-minute consultation with your GP would set you back $36.86 on average.

                          Bulk Billing GPs

                          One of the easiest ways to reduce or avoid any out-of-pocket expenses is to visit a bulk billing provider. These clinics bill Medicare directly and accept the scheduled fee as full payment, which means that you will have no expense for your consultation.

                          Private health insurance

                          Private health insurance helps cover healthcare costs not completely paid for by Medicare, such as dental, physio, ambulance and private hospital treatment. It gives you more choice over your care. And since you’ll have access to private hospitals, it can reduce long waiting times for some procedures.

                          This kind of insurance is usually taken out as an adult, or if you earn above the Medicare Levy Surcharge threshold. With private health insurance, you pay a regular premium, and, depending on your coverage, the insurer contributes toward your treatment costs. However, you may still have to pay an excess or gap fee in some cases.

                          Medical loans

                          In the case that you have excessive medical fees that you are unable to pay for, a medical loan can help. A medical loan provides funds upfront so you can get the treatment you need without worrying about the expense. Medical loans can be used for the following:

                          • Specialist appointments
                          • Prescriptions, tests, and scans
                          • Dental work
                          • Laser-eye surgery
                          • Weight loss surgery
                          • Plastic surgery
                          • IVF treatment
                          • Post-accident surgeries

                          Payment plans with hospitals or clinics

                          A dentist smiles down at their patient in the chair as they prepare to examine their mouth

                          Many private hospitals, dentists, and specialists offer payment plans that let you pay for your treatment in installments, making it easier to manage the costs over time. It’s a good idea to ask about any available payment options before your appointment or procedure. Knowing what’s available upfront can take a lot of the financial stress out of the process.

                          Certain dental or orthodontic procedures, like implants or wisdom teeth removal, are typically not covered by Medicare or private health insurance, depending on your level of coverage. These treatments are often available through payment plans or may require you to take out a cash loan.

                          Nonprofit and charity organisations

                          Close up of someone cupping another person's hands in theirs for emotional support

                          A range of nonprofit and charity organisations offer valuable support for those struggling with medical expenses. Groups like the Red Cross, St Vincent de Paul (Vinnies), and the Cancer Council can assist. They can help with things like financial aid to help cover treatment, transportation to and from appointments, and short-term accommodation for patients who need to travel for care.

                          Some non-profit and NDIS organisations also provide food vouchers, emotional support services, or help navigating the healthcare system. Their goal is to ease all of the other factors that may be a burden, so patients can focus on recovery rather than finances.

                          Strategies to prepare for future medical bills

                          Prepare yourself for future medical bills with the following strategies:

                          • Create an emergency fund – aim to have between $2,000 and $5,000 in a separate account that is for medical or non-medical emergencies.
                          • Create a budget – when you do your household budgets, incorporate a small portion of your income into a medical expenses account that will be a safety net for any future medical emergencies.
                          • Consider health insurance – Health insurance can help with any out-of-pocket expenses, significantly leaving a small “gap payment” for you to pay. It is important to review your health insurance policies periodically to make sure that your insurance is meeting your medical needs.

                          Red Tree Finance is here to help

                          At Red Tree Finance, we completely understand that medical expenses can arise unexpectedly. If you’re looking for support and wondering how to get help with medical bills in Australia, our team can help. With our medical loans, you can apply for up to $5,000, with fast, often same-day approval. Focus on your health and well-being without worrying about the upfront costs of your treatment.

                          Frequently Asked Questions

                          View all FAQs View all FAQs

                          Here are several ways to get assistance with medical expenses in Australia, including:

                          • Taking out a personal loan from a financial institution.
                          • Understanding what Medicare will cover for your treatment.
                          • Finding a medical practice that offers bulk billing.
                          • Inquiring if your hospital provides payment plans.
                          • Reaching out to non-profit or charity organisations for support.

                          If you need immediate help, there are services available, such as the National Debt Helpline, that provide assistance with essential services such as food, housing, and bills and offer emotional support. If you need access to funds up to $5,000, a same-day loan from Red Tree Finance can give you access to funds within the same day.

                          If you do not have enough money to afford medication, there are several options for you:

                          • Speak to your doctor and let them know about your situation – they may be able to offer cheaper alternatives.
                          • Apply for the Pharmaceutical Benefits Scheme – this allows you to access subsidised medication.
                          • Ask your pharmacist if they have a discounted medicine program – some pharmacies offer discounts or coupons to reduce the costs of prescription medicine.

                          People also read:

                          Can I Get A Loan If I Already Have One?
                          How To Reduce Debt And Gain Financial Control
                          How To Get Help With Vet Bills

                          The information provided in this blog is of a general nature and is provided without considering your specific objectives, financial situation, or needs. It is intended for informational purposes only and should not be relied upon as financial, investment, or other professional advice.

                          Before making any financial decisions or taking action based on the information presented, you are strongly encouraged to assess its appropriateness in light of your individual circumstances. Red Tree Finance does not intend to provide personalised financial advice, and you should seek independent financial, legal, tax, and other relevant advice tailored to your unique situation.
                          image
                          img
                          image
                          img
                          Apply now

                          Ready to apply for a loan?

                          Apply to borrow up to $5,000 fast. Complete your online application in under 5 minutes.

                          image
                          image
                          image

                          Getting A Quick Loan Using A Car As Collateral

                          Looking for a way to access quick cash? A quick loan using a car as collateral may be a practical way to borrow when you want a simple online application and a fast outcome. Unexpected costs can happen, especially during a cost of living crisis.

                          Loans Advice 10 July 2024

                          In this article:

                            Calculate your loan repayments

                            How much would you like to borrow?

                            Simple. Transparent. Tailored to you.

                            Loan amount:
                            $
                            $2,350 $5,000
                            Repayment frequency:
                            Weekly repayment:

                            (Over 12 month loan term)

                            $0.00
                            • Loan term 12 months
                            • Interest & Fees $1,072
                            • Total to pay $3,172
                            arrow
                              image

                              Looking for a way to access quick cash? A quick loan using a car as collateral may be a practical way to borrow when you want a simple online application and a fast outcome. Unexpected costs can happen, especially during a cost of living crisis.

                              What is a loan that uses your car as collateral?

                              A quick loan using your car as collateral is commonly known as a “secured loan”. With this type of loan, your vehicle is used as security for the funds you borrow, which may help make the process faster and more accessible for some applicants.

                              Because the car supports the loan, some lenders may be able to offer higher borrowing amounts than they would with an unsecured loan. The exact loan amount will depend on the lender’s criteria, the value of the vehicle, and your overall financial situation.

                              How does a secured loan work?

                              When you apply for a loan using your car as collateral, the lender will assess the vehicle’s value and other details about your application. If approved, you can borrow up to a certain percentage of this value. During the loan term, the lender holds a security interest in the car until the loan is repaid.

                              At Red Tree Finance, the process is designed to be simple and online, so you can apply without a lot of back and forth. If your vehicle is in good condition and registered in your name, it may be possible to use it as security for a loan.

                              What is the difference between a secured and unsecured loan?

                              A secured loan uses an asset, such as a car, as security for the loan. An unsecured loan does not use collateral, so the lender relies more heavily on your application details and repayment capacity.

                              That difference can affect the way a loan is assessed, the amount available, and how the loan is structured.

                              Eligibility and requirements for a secured loan

                              To qualify for a quick loan using your car as collateral, you will usually need to meet the lender’s eligibility criteria and provide a few key documents. At Red Tree Finance, you will need:

                              • To be at least 18 years old.
                              • An unencumbered vehicle registered in your name.
                              • Proof of income and expenditure to demonstrate repayment ability.
                              • Valid identification and proof of residence.

                              If you are unsure whether your situation fits, you can check your eligibility before you apply.

                              Applying for a loan using a car as collateral

                              Applying for a quick loan using your car as collateral is straightforward:

                              1. Apply: Fill out our online form with your personal and vehicle details.
                              2. Vehicle valuation: We assess the value of your car to determine the loan amount up to $5000.
                              3. Loan approval: Once approved, you’ll receive the loan amount in your account, typically within 2 business hours.

                              What can I do if I don’t have a car to use as collateral for a loan?

                              If you do not have a car to use as collateral, you can still look at other ways you can boost your funds in other ways:

                              1. Do a household clean out and make some money by selling things you no longer need.
                              2. Get on top of your finances, once and for all, and create a foolproof budgeting system on Excel. Methods like the 50/20/30 rule can be a good place to start.
                              3. Organise your bills and pay them on time.
                              4. Look into ways you can save on bills in the winter.
                              5. Try to reduce your impulse shopping.
                              6. Speak with your bank, insurance companies and telco companies about flexible bill payments to manage your cash flow.

                              Fast funds using your car as collateral

                              Sometimes using your car as collateral for a loan can offer a practical way to access funds without having to sell your vehicle. When you can’t stretch the budget to cover an unexpected expense in one go, a secured personal loan using your car as collateral can help you meet those financial goals and stay afloat.

                              Yes, in some cases you can use your car as collateral for a loan. The vehicle is used as security while the loan is repaid, subject to lender criteria.

                              Yes, if the car is already owned and meets the lender’s requirements, it may be possible to use it as security for a loan. The vehicle usually needs to be registered in your name and free from existing encumbrances.

                              Lenders ask for collateral to reduce their risk on the loan. It gives them an asset tied to the loan agreement if the borrower does not meet repayment obligations.

                              The information provided in this blog is of a general nature and is provided without considering your specific objectives, financial situation, or needs. It is intended for informational purposes only and should not be relied upon as financial, investment, or other professional advice.

                              Before making any financial decisions or taking action based on the information presented, you are strongly encouraged to assess its appropriateness in light of your individual circumstances. Red Tree Finance does not intend to provide personalised financial advice, and you should seek independent financial, legal, tax, and other relevant advice tailored to your unique situation.
                              image
                              img
                              image
                              img
                              Apply now

                              Ready to apply for a loan?

                              Apply to borrow up to $5,000 fast. Complete your online application in under 5 minutes.

                              image
                              image
                              image

                              How To Get Help With Vet Bills

                              When your furry companion needs veterinary care, your priority is ensuring they receive the help they need.However, exams, medications, and surgeries can add up quickly and leave you with significant costs to pay. But don’t worry, we’ve compiled a list of 7 ways to get help with vet bills and reduce vet expenses, so you

                              Financial Help 10 May 2023

                              In this article:

                                Calculate your loan repayments

                                How much would you like to borrow?

                                Simple. Transparent. Tailored to you.

                                Loan amount:
                                $
                                $2,350 $5,000
                                Repayment frequency:
                                Weekly repayment:

                                (Over 12 month loan term)

                                $0.00
                                • Loan term 12 months
                                • Interest & Fees $1,072
                                • Total to pay $3,172
                                arrow
                                  image

                                  When your furry companion needs veterinary care, your priority is ensuring they receive the help they need.However, exams, medications, and surgeries can add up quickly and leave you with significant costs to pay. But don’t worry, we’ve compiled a list of 7 ways to get help with vet bills and reduce vet expenses, so you can focus on your pet’s health rather than the hefty bills. From finding affordable care options and loans for vet bills to preventative measures, these tips can make a real difference in keeping costs down while giving your pet the best care possible.

                                  7 ways to get help with vet bills

                                  Each year you’re likely to spend around $962 on a cat, and $1627 on a dog – and that’s all before vet bills, emergencies, and pricey medications eat through your savings. So, here are 7 ways to get help with vet bills:

                                  1. Pet insurance

                                  One of the safest ways to cut costs on your next vet visit is by securing pet insurance. This means you won’t need to cover the whole cost yourself.

                                  Instead, you will get some help from your insurer. And just like human health insurance, it will generally cover accidents and illnesses. However, each pet health insurance company will come with different features, terms and conditions, so be sure to carefully assess your options before deciding on one. Luckily, there are plenty of helpful websites that will let you compare each company’s plan.

                                  2. Low-cost vet care

                                  Another way to get help with vet bills is opting for low-cost vet clinics around Australia. Although sometimes it can take longer to get an appointment, the lower vet costs will be worth the wait! Some of the best low-cost vet clinics around Australia include:

                                  how to get help with vet bills - low-cost vet care

                                  3. Charitable organisations

                                  Reaching out to a charity to get help with vet bills can feel stressful, however, there are a wide range of different organisations that are willing to give you financial assistance and support your furry friend.

                                  You will need to apply for help and your result will be based on your income. If you have a low income and need money fast, you may be entitled to receive financial assistance.

                                  Some great charitable organisations you can turn to for help include:

                                  4. Loan for vet bills

                                  Small personal loans are one of the best options when it comes to getting yourself out of a tough financial situation. Luckily, there are plenty of good loan companies (like Red Tree Finance) that can help you pay for your vet bills in Australia.

                                  They’re also super easy to apply for online from any device and you can use your vehicle as collateral. Plus, you can get the money in your bank account the very same day.

                                  5. Crowdsource funding

                                  Another great way to get vet fee assistance is crowdsource funding, which is a collective effort of raising money through friends, family, and generous strangers.

                                  Crowdsourcing can actually be a highly effective way to cover the cost of your vet bills. All you need to do is set up a campaign on an official crowdsourcing website and you should be able to get your bills covered in no time! Some great crowdsourcing websites include:

                                  how to get help with vet bills - crowdsource funding

                                  6. Buy now, pay later

                                  Many veterinary clinics nowadays offer buy now and pay later options. This means you can get your vet assistance and pay your bill in instalments over time. Some popular buy now and pay later options available to most vet clinics include:

                                  Be aware of buy now, pay later options as they can sometimes interfere with your credit score.

                                  7. Sell your unused items online

                                  If you’re not interested in applying for any payment plans with your veterinary clinic, then a simple way to get some quick cash is by selling your valuable items you no longer have use for. There’s always someone to find use for your old items, whether they’re clothes, electronics, collectables, furniture, toys or crafts. A great place to start is by listing your items up on Facebook Marketplace, Gumtree, eBay or Etsy. And, soon you will have the funds to cover your pet’s medical expenses.

                                  how to get help with vet bills - sell your unused items online

                                  Finance your next vet visit with Red Tree Finance

                                  If you’re in need of medical assistance for your beloved pet, consider getting an instant loan with Red Tree Finance.

                                  You can easily apply in less than 5 minutes and receive up to $5000. Our team works quickly to give you a decision within 2 business hours so you can get a same day loan and avoid prolonged stress. Apply for a loan today and leave the financial stress to us!

                                  If you have any questions or want more information on applying for a loan for vet bills, please don’t hesitate to contact us today.

                                  Aside from the above list of ways to save on your vet bills. We also recommend being up front about your budget and contacting different vet clinics to assess all your options. You can also try asking if they offer discounts for any services and whether they provide free routine check ups.

                                  For human healthcare in Australia, Medicare and the PBS subsidise our health costs. Unfortunately, there is no Medicare system for pets. This means pet owners are required to pay the entirety of the vet bills, which is why the cost of veterinary bills tends to be so expensive.

                                  A visit to the veterinary clinic will most commonly have some sort of out-of-pocket costs, whether that’s a small or large payment. However, many vet clinics are now offering payment plans to help pet owners with hefty bills. If you are facing issues that make it difficult to pay for your pet’s medical care, then we recommend calling the RSPCA welfare line on 1300 4 777 2 for more advice.

                                  People also read:

                                  The information provided in this blog is of a general nature and is provided without considering your specific objectives, financial situation, or needs. It is intended for informational purposes only and should not be relied upon as financial, investment, or other professional advice.

                                  Before making any financial decisions or taking action based on the information presented, you are strongly encouraged to assess its appropriateness in light of your individual circumstances. Red Tree Finance does not intend to provide personalised financial advice, and you should seek independent financial, legal, tax, and other relevant advice tailored to your unique situation.
                                  image
                                  img
                                  image
                                  img
                                  Apply now

                                  Ready to apply for a loan?

                                  Apply to borrow up to $5,000 fast. Complete your online application in under 5 minutes.

                                  image
                                  image
                                  Apply now Apply now